Browse our range of reports and publications including performance and financial statement audit reports, assurance review reports, information reports and annual reports.
Performance audit (Auditor-General Report No. 34 of 2004–05)
Published: Wednesday 9 March 2005
Published
Given the importance of customer feedback to Centrelink's business, the ANAO considered it timely to conduct a series of performance audits relating to Centrelink's customer feedback systems, particularly in relation to its delivery of the services then provided on behalf of FaCS. The overarching objective of this series of ANAO performance audits of Centrelink's customer feedback systems was to assess whether Centrelink has effective processes and systems for gathering, measuring, reporting and responding effectively to customer feedback, including in relation to customer satisfaction with Centrelink services and processes.
Entity
Centrelink
Performance audit (Auditor-General Report No. 32 of 2004–05)
Published: Wednesday 9 March 2005
Published
Given the importance of customer feedback to Centrelink's business, the ANAO considered it timely to conduct a series of performance audits relating to Centrelink's customer feedback systems, particularly in relation to its delivery of the services then provided on behalf of FaCS. The overarching objective of this series of ANAO performance audits of Centrelink's customer feedback systems was to assess whether Centrelink has effective processes and systems for gathering, measuring, reporting and responding effectively to customer feedback, including in relation to customer satisfaction with Centrelink services and processes.
Entity
Centrelink
Performance audit (Auditor-General Report No. 36 of 2004–05)
Published: Wednesday 9 March 2005
Published
Given the importance of customer feedback to Centrelink's business, the ANAO considered it timely to conduct a series of performance audits relating to Centrelink's customer feedback systems, particularly in relation to its delivery of the services then provided on behalf of FaCS. The overarching objective of this series of ANAO performance audits of Centrelink's customer feedback systems was to assess whether Centrelink has effective processes and systems for gathering, measuring, reporting and responding effectively to customer feedback, including in relation to customer satisfaction with Centrelink services and processes.
Entity
Centrelink
Performance audit (Auditor-General Report No. 33 of 2004–05)
Published: Wednesday 9 March 2005
Published
Given the importance of customer feedback to Centrelink's business, the ANAO considered it timely to conduct a series of performance audits relating to Centrelink's customer feedback systems, particularly in relation to its delivery of the services then provided on behalf of FaCS. The overarching objective of this series of ANAO performance audits of Centrelink's customer feedback systems was to assess whether Centrelink has effective processes and systems for gathering, measuring, reporting and responding effectively to customer feedback, including in relation to customer satisfaction with Centrelink services and processes.
Entity
Centrelink
Performance audit (Auditor-General Report No. 29 of 2008–09)
Published: Thursday 23 April 2009
Published
The objective of this performance audit of construction projects on the AusLink National Network was to assess the effectiveness of the administration by DITRDLG in working with the States to deliver the outcomes expected by the Government and the broader community. To inform the audit assessment, the methodology included examination of both Australian Government and State Government records as well as site inspections in relation to 21 projects being delivered in three States (New South Wales (NSW), Queensland and Tasmania). DITRDLG and the respective State road transport authorities were consulted in the selection of projects to be examined in detail.
Entity
Department of Infrastructure, Transport, Regional Development and Local Government
Performance audit (Auditor-General Report No. 20 of 2003–04)
Published: Friday 19 December 2003
Published
The objective of the audit was to assess the Australian Agency for International Development's (AusAid) planning for, and management of, the delivery of aid to East Timor. The audit examined Australia's emergency and humanitarian response following the crisis in East Timor in 1999; AusAID's post-crisis strategy for assisting East Timor; coordination with overseas donors; and financial contributions to multilateral reconstruction assistance. Australia's bilateral assistance, comprising shorter-term transitional assistance and medium-term development assistance, was also examined.
Entity
Australian Agency for International Development (AusAID)
Performance audit (Auditor-General Report No. 41 of 2011–12)
Published: Thursday 14 June 2012
Published
The audit objective was to assess the effectiveness of DEEWR's administration of the National Partnership Agreement on Literacy and Numeracy (LNNP). The three high-level audit criteria used to form a conclusion examined the extent to which DEEWR:
- established sound administrative and payment arrangements consistent with government policy, including through its negotiation of bilateral agreements, implementation plans and reform targets;
- properly managed administrative and payment arrangements; and
- effectively monitored and reported on delivery and outcomes.
Entity
Department of Education, Employment and Workplace Relations
Performance audit (Auditor-General Report No. 1 of 2009–10)
Published: Tuesday 4 August 2009
Published
In two letters dated 19 and 22 June 2009, the Prime Minister requested a performance audit of a range of matters relating to representations to the Treasury regarding automotive finance arrangements for car dealers. In response to these requests, the Auditor-General decided that ANAO would undertake a performance audit under section 18 of the Auditor-General Act 1997 (Auditor-General Act). The audit objective, based on the matters raised in the Prime Minister's correspondence and in the Parliament, was to examine and report on:
- any representations to the Treasury since October 2008 from all sources regarding automotive finance arrangements for car dealers, including any made in relation to John Grant Motors;
- the nature of these representations;
- the manner in which the representations were responded to by officials, having regard to any relevant standards and procedures; and
- any related administrative matters that came to attention.
Entity
Department of the Treasury; Department of the Prime Minister and Cabinet
Performance audit (Auditor-General Report No. 19 of 2003–04)
Published: Wednesday 17 December 2003
Published
The objective of the audit was to assess whether the property management function, including the management of leases, was being performed efficiently and was providing an effective level of support for the delivery of the organisation's services (outputs). The audit evaluated property management policies and practices across the following dimensions:
- planning and control;
- business processes and practices; and
- information and performance management.
Within each of these areas, a series of desirable proceses and controls (described as the evaluation criteria) were developed to assist in the assessment of each organisation's performance.
Entity
Australian Communications Authority; Australian Film, Television and Radio School; Civil Aviation Safety Authority; Department of Employment and Workplace Relations; National Library of Australia; Department of Finance and Administration
Performance audit (Auditor-General Report No. 49 of 2004–05)
Published: Thursday 2 June 2005
Published
The objectives of the audit were to:determine whether entities had established effective internal control frameworks and processes to mitigate the risks associated with FBT obligations and transactions;assess whether the internal control frameworks and processes supported the payment of FBT and the reporting of reportable fringe benefit amounts (RFBAs) on employee payment summaries in accordance with the legislation;identify sound and better practices in the administration, management and operation of systems for collecting, collating, calculating, reporting and remitting FBT; and as necessary, recommend improvements in the controls and practices relating to the administration of FBT in the audited entities.
Entity
Commonwealth Scientific and Industrial Research Organisation; Department of Defence; Australian Taxation Office
Performance audit (Auditor-General Report No. 33 of 2003–04)
Published: Wednesday 3 March 2004
Published
The audit reviewed the ATO's collection and management of activity statement information. The audit paid particular regard to:
- the environment into which activity statements were introduced;
- taxpayer concerns with activity statement administration;
- the mechanisms the ATO uses to capture and process activity statements;
- the change processes the ATO uses to change and test activity statement IT systems; and
- the management methodology used to report on, and assess the performance of, activity statement related systems and processes.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 32 of 2009–10)
Published: Wednesday 28 April 2010
Published
The objective of the audit was to assess the effectiveness of OPO's management of the overseas owned estate. In particular, the audit examined whether:
- sound arrangements are in place to effectively plan and oversight the management of the overseas estate;
- OPO effectively manages owned property on a day-to-day basis;
- the condition of the overseas owned estate is adequately maintained by structured and systematic repair and maintenance arrangements; and
- OPO has appropriate information to facilitate the effective management of the owned estate, and appropriately consults with stakeholders.
Entity
Department of Foreign Affairs and Trade
Performance audit (Auditor-General Report No. 2 of 2021–22)
Published: Wednesday 8 September 2021
Published
The audit objective was to assess the effectiveness of the Australian Security Intelligence Organisation's workforce planning to support key activities.
Entity
Australian Security Intelligence Organisation
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 28 of 2015–16)
Published: Thursday 28 April 2016
Published
The objective of the audit was to assess the Department of Agriculture and Water Resources' establishment and administration of the Farm Finance and Drought Concessional Loans programs.
Entity
Department of Agriculture and Water Resources
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 35 of 2005–06)
Published: Tuesday 28 March 2006
Published
The objective of the audit was to assess the ATO's administration of activity statement HRRs. Specifically the audit sought to: examine aspects of ATO governance relevant to its administration of activity statement HRRs. This includes: ATO planning, the integration between Lines to administer HRRs; corporate risk management processes; and performance management; assess the ATO's methodology and practice to identify and, if necessary, correct activity statement HRRs; and identify and assess the Information Technology (IT) and manual systems, processes and controls used by the ATO to process HRRs resulting from the lodgement of activity statements.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 23 of 2009–10)
Published: Tuesday 23 February 2010
Published
The objective of the audit was to assess the effectiveness of Customs and Border Protection's performance in managing and coordinating enforcement operations against illegal foreign fishing in Australia's northern waters. The audit focused on Customs and Border Protection's role within the whole of government policy coordination framework; the effectiveness of its intelligence support for operational planning and policy and strategy development; its performance in planning, prioritising and administering effective enforcement operations; and its performance in measuring and reporting on the effectiveness of the program.
Entity
Australian Customs and Border Protection Service
Performance audit (Auditor-General Report No. 36 of 2007–08)
Published: Thursday 29 May 2008
Published
The objective of the audit was to assess the Tax Office's strategies to address tax haven compliance risks. Particular emphasis was given to the Tax Office's:
- management arrangements relating to the administration of tax haven compliance risks;
- risk management framework for the identification and evaluation of compliance risks, specifically the activities of the Offshore Compliance Program (OCP); and
- risk mitigation strategies.
The audit did not include an examination of cases related to the promoters of tax haven related schemes nor the criminal use of tax havens.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 18 of 2004–05)
Published: Thursday 16 December 2004
Published
The Therapeutic Goods Administration (TGA), a division of the Commonwealth Department of Health and Ageing, is responsible for the regulation of the manufacture and supply of therapeutic goods. The objective of the audit was to assess the TGA's regulation of non-prescription medicinal products. In particular, it reviewed the TGA's systems, procedures and resource management processes used to approve new manufacturers, monitor ongoing manufacturer and product compliance with mandated requirements, and manage non-compliance. The audit made 26 recommendations designed to improve the transparency, quality and reliability of regulatory decisions taken by the TGA and improve its accountability mechanisms by enhancing its management information systems.
Entity
Department of Health and Ageing
Performance audit (Auditor-General Report No. 31 of 2009–10)
Published: Thursday 22 April 2010
Published
The audit scope covered the management of the AusLink R2R Standard Program and the AusLink R2R Supplementary Program. The scope did not include management of the Nation Building Roads to Recovery Program, which has only recently commenced. The audit objectives were to:
- assess the effectiveness of the management of the AusLink Roads to Recovery Program;
- assess the delivery of the program and management of the funding, including the extent to which the program has provided additional (rather than substitute) funding for land transport infrastructure; and
- identify opportunities for improvements to the management of the program.
Entity
Department of Infrastructure, Transport, Regional Development and Local Government
Performance audit (Auditor-General Report No. 6 of 2007–08)
Published: Tuesday 11 September 2007
Published
The objective of this audit was to examine Australia's preparedness to respond to a human influenza pandemic and an outbreak of avian influenza in domestic poultry. The audit assessed:
- the whole of government arrangements for an influenza pandemic;
- action taken by DAFF to implement the recommendations from Exercise Eleusis, which tested the response arrangements for avian influenza;
- DoHA's planning for, and execution of, Exercise Cumpston, which tested the preparedness and response to an influenza pandemic; and
- the establishment, management and deployment arrangements of the National Medical Stockpile.
Entity
Department of Health and Ageing; Department of Agriculture, Fisheries and Forestry
Performance audit (Auditor-General Report No. 46 of 2008–09)
Published: Thursday 25 June 2009
Published
The objectives of this audit were to:
- assess the current status of BCM and EM arrangements in Centrelink and identify opportunities for improvement; and
- review Centrelink's response to the recommendations.
Entity
Centrelink
Performance audit (Auditor-General Report No. 13 of 2011–12)
Published: Tuesday 22 November 2011
Published
The objective of the audit was to assess the effectiveness of DIT’s and Centrelink’s1 administration of TFES.
[1] From 1 July 2011, Centrelink became a master program within DHS.
Entity
Department of Infrastructure and Transport, Department of Human Services
Performance audit (Auditor-General Report No. 33 of 2011–12)
Published: Tuesday 22 May 2012
Published
The objective of the audit was to assess the effectiveness of DFAT's implementation of biometric technology to meet international requirements for enhanced passport security. In particular, the audit examined whether:
- Australian ePassports meet international requirements, and coordination with Australian stakeholders is effective;
- Australian biometric passport technology is fit for purpose and has enhanced passport security;
- personal data on the passport microchip is secure and DFAT maintains an appropriate focus on both protecting privacy and client satisfaction; and
- arrangements are in place to evaluate the effectiveness of the ePassport and to monitor risks.
Entity
Department of Foreign Affairs and Trade
Performance audit (Auditor-General Report No. 6 of 2019–20)
Published: Monday 5 August 2019
Published
The objective of the audit was to examine whether selected entities implemented agreed ANAO performance audit, the Joint Committee of Public Accounts and Audit, and other parliamentary committee recommendations.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 23 of 2007–08)
Published: Thursday 21 February 2008
Published
The objective of the audit was to assess whether selected regulatory agencies have cost recovery procedures and practices which comply with the Government's guidelines. To address this objective, the audit assessed the management of cost recovery against the following criteria:
- regulatory agencies have clear and consistent cost recovery procedures to identify their activities and costs, and set fees and levies;
- regulatory agencies have effectively implemented their cost recovery procedures;
- regulatory agencies regularly monitor and review their cost recovery activities; and
- regulatory agencies regularly report on their cost recovery.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 24 of 2008–09)
Published: Thursday 5 March 2009
Published
The objective of the audit was to assess the effectiveness of the procurement and contracting associated with:
- the design, development and delivery of government advertising campaigns by Commonwealth departments; and
- the operation of the Central Advertising System (CAS).
Entity
Department of the Prime Minister and Cabinet; Department of Finance and Deregulation; Department of Education, Employment and Workplace Relations; Department of Health and Ageing; Attorney-General's Department
Performance audit (Auditor-General Report No. 25 of 2010–11)
Published: Wednesday 2 February 2011
Published
The audit examined the effectiveness of DEEWR's: administrative framework for the program; management of the application, assessment and funding processes; and monitoring of and reporting on the program's performance.
In order to form an opinion against the audit objective, the ANAO primarily conducted fieldwork and documentation reviews at DEEWR's central office. A stratified random sample (in order to provide for representation from states, territories and school sectors) of 74 applications from Rounds 1 and 2 was also selected for detailed examination. Through this sample, the ANAO sought to determine whether funding applications had been assessed in accordance with the established assessment criteria and that quality assurance mechanisms for the assessment process were effective.
Entity
Department of Education, Employment and Workplace Relations
Performance audit (Auditor-General Report No. 1 of 2012–13)
Published: Tuesday 21 August 2012
Published
The objective of the audit was to assess the effectiveness of the Department of Resources, Energy and Tourism’s administration of the Renewable Energy Demonstration Program (REDP), including progress towards achieving the programʹs objectives.
The audit examined whether the department had established effective arrangements to:
- implement REDP, including governance arrangements;
- assess applications for REDP funding assistance and recommend projects to the Minister for funding approval;
- negotiate funding agreements for approved projects; and
- monitor progress towards the achievement of the REDP objective.
Entity
Department of Resources, Energy & Tourism
Performance audit (Auditor-General Report No. 12 of 2007–08)
Published: Thursday 1 November 2007
Published
The objective of the audit was to assess the effectiveness of the Tax Office's compliance approach for high risk income tax refunds in the individuals and micro enterprises market segments. The audit examined three key areas:
management and organisational arrangements relating to high risk income tax refund processes;
processes and procedures for identifying high risk income tax refunds, and the processes and tools used to evaluate and verify taxpayers' entitlements to income tax refunds; and
information technology systems, processes and controls supporting the processing of income tax returns and refunds.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 6 of 2008–09)
Published: Tuesday 30 September 2008
Published
The objective of the audit was to assess whether Customs has implemented effective measures to control IUU fishing in the Southern Ocean. The audit examined Customs' management and coordination of enforcement operations in the Southern Ocean, with particular emphasis on:
- the approach to assessing and reporting SOMPR program performance, and whether outcomes are being met;
- coordination with other stakeholder agencies to meet program outcomes;
- the operational planning framework, management of human and physical resources and contract management; and
- the management of the deployment and operation of program maritime assets.
Entity
Australian Customs Service
Performance audit (Auditor-General Report No. 27 of 2006–07)
Published: Wednesday 21 February 2007
Published
This audit focuses on the Australian Defence Force's (ADF) Air Combat fleet's logistics support, regular maintenance and structural refurbishment. These activities are collectively referred to as fleet in-service support. The current Defence White Paper states that Air Combat is the most important single capability for the defence of Australia.
The audit objective was to assess the effectiveness of the Air Combat fleet's in-service support arrangements to provide capability for air combat operations. Capital equipment acquisition projects covered by this report are limited to the Hornet and F-111 structural refurbishment projects, which aim to ensure these aircraft remain serviceable until their withdrawal from service.
Entity
Department of Defence; Defence Materiel Organisation
Performance audit (Auditor-General Report No. 4 of 2006–07)
Published: Tuesday 12 September 2006
Published
The objective of the audit was to review the operation of the ATO's Tax Agent and Business Portals. In conducting the audit the ANAO examined three key areas: governance – the governance arrangements supporting ongoing management of the Portals; portals development, user satisfaction and realisation of expected benefits – the ATO's processes for involving users in developing the Tax Agent and Business Portals, assessing user satisfaction, and evaluating business benefits arising from uptake of the Portals; and information technology (IT) security and user access controls – the ATO's IT security environment and user access controls supporting the operation of the Tax Agent and Business Portals.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 6 of 2010–11)
Published: Tuesday 21 September 2010
Published
The objective of the audit was to assess the implementation of the Australian Taxation Office's Client Contact – Work Management – Case Management system (CWC). The audit examined four key areas that included:
- progress of the CWC against the endorsed Change Program business case;
- improvements to the productivity and efficiency of tax administration as a result of the implementation of the CWC;
- improvements to client experiences when dealing with the Tax Office as a result of the implementation of the CWC; and
- effects of the CWC implementation, including additional benefits achievable beyond its current capacity to further improve tax administration.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 46 of 2019–20)
Published: Thursday 25 June 2020
Published
Implementation of ANAO and Parliamentary Committee Recommendations — Education and Health Portfolios
The audit objective was to examine whether selected entities in the Health and Education portfolios implemented the Joint Committee of Public Accounts and Audit and other parliamentary inquiry report recommendations and agreed ANAO performance audit recommendations.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 11 of 2010–11)
Published: Thursday 30 September 2010
Published
The objective of the audit was to assess how well agencies had implemented the CPGs and relevant FMA legislation when undertaking Direct Source procurement.
The audit examined whether selected agencies had developed a sound procurement framework; appropriately classified procurement methods when meeting external reporting requirements; implemented the CPGs and relevant legislation when Direct Sourcing; and established effective procurement monitoring and review arrangements.
The ANAO selected four FMA Act agencies to provide a cross-section of the 104 agencies that reported procurement activity in AusTender in
2008–09. The agencies selected for audit were:
- the Department of Families, Housing, Community Services and Indigenous Affairs (FaHCSIA);
- the Department of Innovation, Industry, Science and Research (Innovation);
- the Department of Veterans' Affairs (DVA); and
- the Australian Crime Commission (ACC).
The ANAO examined a stratified random sample of 645 procurements valued at $10 000 and over, across the four agencies. More detailed testing was undertaken for the 285 Direct Source procurements in the sample.
Entity
Across Agencies
Insights: Audit lessons
Published: Monday 29 June 2020
Published
This edition of Audit Insights summarises key messages from Australian National Audit Office (ANAO) performance audits about the management of conflicts of interest by Australian Government entities in relation to procurement activity and grants programs.
Contact
Please direct enquiries about audit insights through our contact page.
Performance audit (Auditor-General Report No. 39 of 2009–10)
Published: Monday 24 May 2010
Published
The objective of this audit was to examine the effectiveness of Medicare Australia's administration of the PBS. In assessing the objective, the audit considered three key areas:
- Medicare Australia's relationship with the PBS policy agency (DoHA) and service delivery policy agency (Department of Human Services (DHS));
- the management arrangements and processes underpinning Medicare Australia's delivery of the PBS (including the means by which Medicare Australia gains assurance over the integrity of the PBS); and
- how Medicare Australia undertakes its three main responsibilities relating to the delivery of the PBS, namely: approving pharmacies; approving authority prescriptions; and processing PBS claims.
Entity
Medicare Australia; Department of Human Services; Department of Health and Ageing
Performance audit (Auditor-General Report No. 13 of 2010–11)
Published: Thursday 28 October 2010
Published
The Civil Aviation Safety Authority (CASA) is responsible for regulating aviation safety in Australia, the safety of Australian aircraft operating overseas as well as for regulating and administering Australia's airspace. In September 2008, the Senate Committee on Rural and Regional Affairs and Transport presented a report on the Administration of the Civil Aviation Safety Authority and related matters. That report made three recommendations, one of which requested an Australian National Audit Office (ANAO) audit of CASA's implementation and administration of the regulation of aircraft operators' Safety Management Systems (SMS'). ANAO agreed to this request with the objective of the audit being to assess CASA's implementation and administration of an SMS approach to regulating aircraft operators.
An SMS is a systematic approach to managing safety, which encompasses organisational structures, accountabilities, policies and procedures. Amendments to the Convention on International Civil Aviation (commonly referred to as the Chicago Convention) made in 2006 require that contracting states regulate the SMS' of aircraft operators. As a contracting state to the Chicago Convention, Australia is required to mandate that aircraft operators implement an SMS.
Entity
Civil Aviation Safety Authority
Performance audit (Auditor-General Report No. 20 of 2010–11)
Published: Tuesday 14 December 2010
Published
The objective of the audit was to assess the effectiveness of the Tax Office's administration of the wine tax.
Four key areas were examined in the audit: governance arrangements; interpretative assistance and advice; compliance approaches for Australian entities; and administering the rebate for New Zealand wine producers.
The ANAO conducted fieldwork in the Tax Office's Adelaide office between May and September 2010 and also held discussions with representatives from Customs, the Department of the Treasury (Treasury) and New Zealand Inland Revenue. The ANAO also consulted with representatives of wine producers, wholesalers, retailers, tax agents and key industry associations, seeking their views on elements of the Tax Office's administration of the wine tax.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 3 of 2008–09)
Published: Tuesday 23 September 2008
Published
The objective of the audit was to assess the effectiveness of the management and administration of the Communications Fund, including an assessment of:
- the development and implementation of appropriate investment strategies; and
- the robustness of the governance structures and controls relating to investment activities.
Entity
Department of Broadband, Communications and the Digital Economy; Department of Finance and Deregulation
Performance audit (Auditor-General Report No. 38 of 2005–06)
Published: Thursday 4 May 2006
Published
The objective of this audit was to form an opinion on the Australian Research Council's (ARC's) management of research grants. To achieve this, ANAO centred the audit around the following aspects of ARC's grants administration: governance and structure, particularly the roles and responsibilities of those parties involved in administering ARC's grants (Chapter 2); the processes for assessing and selecting ARC grants (Chapter 3);post-award management of grants under the Funding Agreements (Agreements) between ARC and those universities that receive and administer the ARC grants to researchers (Chapter 4); and ARC's monitoring of its grant programs for management, performance improvement and reporting (Chapter 5). In its assessment, ANAO considered ARC's compliance with relevant sections of the Australian Research Council Act 2001 (ARC Act) and the Financial Management and Accountability Act 1997 (FMA Act). The assessment also took account of the ANAO's Better Practice Guides, particularly the Better Practice Guide—Administration of Grants. The audit focused mainly on ARC's administration of Discovery Projects, the largest scheme in ARC's National Competitive Grants Program (NCGP).
Entity
Australian Research Council
Request for audit
Responded: Tuesday 27 June 2017
Response provided
The Auditor-General responded on 27 June 2017 to correspondence from Mr Andrew Wilkie MP dated 26 May 2017, requesting that the Auditor-General conduct an audit of Centrelink's automated debt recovery programs.
Contact
Please direct enquiries relating to requests for audit through our contact page.
Performance audit (Auditor-General Report No. 19 of 2006–07)
Published: Thursday 25 January 2007
Published
The objective of this audit was to determine whether Health adequately assessed the State and Territory Governments' compliance with their obligations under the terms of the AHCAs. In conducting the audit, ANAO addressed the following criteria:
- if Health assessed whether the States and Territories were adhering to the AHCAs clause 6 principles that all eligible persons had equitable access to free public health and emergency services on the basis of clinical need within an appropriate period;
- if Health assessed whether the States and Territories were increasing their own source funding at the rate specified in the AHCAs; and
- if Health assessed whether the States and Territories were meeting the performance reporting requirements set out in the AHCAs.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 20 of 2009–10)
Published: Wednesday 3 February 2010
Published
The objective of the audit was to examine key aspects of the NBN RFP process, including:
- the background to and conduct of the RFP process;
- management of key risks associated with the process and outcome; and
- stakeholder consultations.
Entity
Department of Broadband, Communications and the Digital Economy
Performance audit (Auditor-General Report No. 19 of 2011–12)
Published: Tuesday 20 December 2011
Published
The objective of the audit was to assess the development of Defence’s oversight and management of its portfolio of ICT investments and projects. In particular, the audit examined Defence’s:
- governance, strategic processes and decision-making structures that set out, prioritise and coordinate the integrated ICT reform portfolio and programs;
- ICT risk management and capacity to identify and plan to achieve the benefits of its SRP ICT stream reforms (including methodologies to measure the realisation of savings and non-savings benefits);
- level of portfolio and program management maturity; and
- the impact of improvement efforts on Defence’s ability to deliver the ICT services capacity required to support the SRP.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 52 of 2006–07)
Published: Thursday 28 June 2007
Published
This is the first of two audit reports concerning the Tax Office's administration of SMSFs pursuant to the provisions of the Superannuation Industry (Supervision) Act 1993.
This audit report examines the efficiency and effectiveness of the Tax Office's approach to regulating and registering self managed superannuation funds. Specifically the ANAO examined the:
- Environment in which SMSFs operate, including the Tax Office's regulatory roles and responsibilities;
- Tax Office's governance of its SMSF regulatory role; and
- Systems, processes and controls the Tax Office uses to register SMSFs, and enforce the lodgement of fund income tax and regulatory returns.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 41 of 2006–07)
Published: Thursday 31 May 2007
Published
The objective of the audit was to assess the efficiency and the effectiveness of DEWR's administrative oversight for the WfD programme. The components of administration examined included whether:
- the operation of the WfD programme was guided by sound business planning including risk assessment;
- DEWR effectively and efficiently managed, monitored and reported the performance of CWCs in meeting contractual obligations;
- adequate support was provided to DEWR contract managers and account managers to assist in the delivery of WfD outcomes;
- there was evaluation of the performance of CWCs in delivering WfD objectives on behalf of the department;
- DEWR measures the effectiveness of WfD against programme objectives; and
- DEWR had implemented agreed recommendations from the previous WfD audit, where current and relevant.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 34 of 2020–21)
Published: Monday 12 April 2021
Published
The audit objective was to examine whether the Department of Defence implemented a selection of agreed parliamentary committee recommendations and ANAO performance audit recommendations.
Entity
Department of Defence
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 39 of 2004–05)
Published: Wednesday 13 April 2005
Published
The objective of the audit was to assess the ATO's administration of the Surcharge. Specifically, the audit sought to: report on the environment into which the Surcharge was introduced, including the legislative intent behind the Surcharge, and the current Surcharge environment; examine and report on aspects of Surcharge governance; assess the systems, processes and controls the ATO uses to: match Member Contributions Statements (MCS) data with income tax return data using Tax File Numbers (TFNs); process Surcharge information; and issue Surcharge liability assessments. assess the mechanisms the ATO uses to assess, classify, manage and rectify existing Surcharge exceptions, and prevent future exceptions from occurring; and examine the mechanisms and strategies the ATO uses to provide assurance that members and holders of contributions are complying with their Surcharge obligations.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 48 of 2003–04)
Published: Thursday 27 May 2004
Published
The objective of the performance audit was to report to Parliament our assessment as to how well the ATO manages and uses the AIIR data in taxation administration. The ANAO considered the following four key areas in addressing the audit objective. 1. Governance arrangements within the ATO, focussing on whole of ATO and whole-of-government aspects of the AIIR data, as distinct from solely business line applications. 2. Receipt of AIIR data and how well the ATO facilitates the collection of complete and valid AIIR data from investment bodies 3. Management of AIIR data through the construction by the ATO of valid entity records by using the AIIR data in conjunction with existing ATO client identification master files. 4: Use of the AIIR data on a systematic basis to inform active compliance activities.
Entity
Australian Taxation Office
Insights: Audit lessons
Published: Friday 28 June 2024
Published
This edition of Audit Lessons is targeted at those responsible for administering or overseeing grants programs. The aim of Audit Lessons is to communicate lessons from our audit work and to make it easier for people working within the Australian public sector to apply those lessons.
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 10 of 2006–07)
Published: Tuesday 31 October 2006
Published
The objective of the report is to review the effectiveness of remediation activities put in place by Defence and the DMO to improve the performance of SDSS following the delivery in July 2003 of the SDSS Upgrade Project, with specific attention to the SDSS Get Well Programme. The audit reviewed the outcomes of the Get Well Programme, and assessed how effectively a segment of the Defence supply chain (of which SDSS is one key component) was meeting selected maritime end user capability and reporting requirements. In order to achieve this, the audit reviewed three key maritime combatant forces: COLLINS Class submarines; Adelaide Class Guided Missile Frigates (FFGs); and ANZAC Class Frigates. The ANAO notes that these three capabilities account for some 50 per cent of the Navy's total forecast expenditure for 2006–07.
Entity
Department of Defence; Defence Materiel Organisation
Insights: Audit practice
Published: Wednesday 25 October 2017
Published
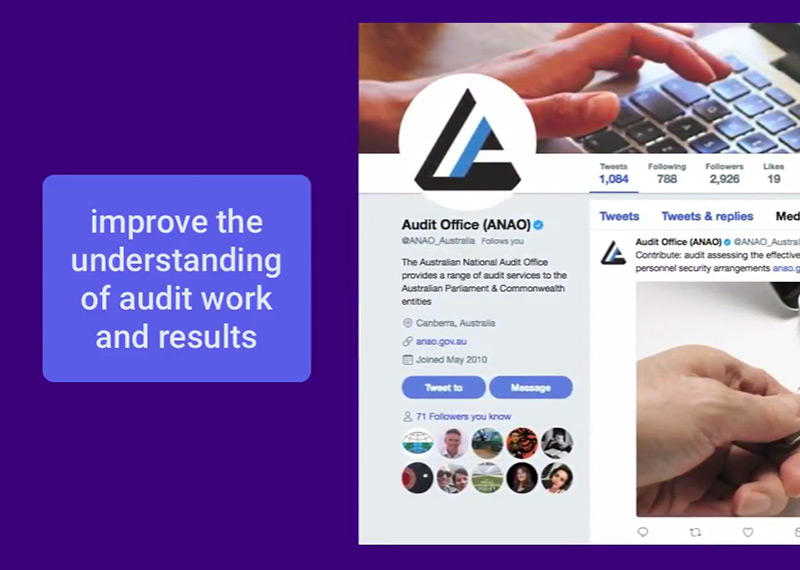
Effective, engaging and accessible communication remains an ongoing focus for the Australian National Audit Office (ANAO), given the important role that we play in providing assurance to the Parliament of Australia, and improving public sector administration.
In this edition of audit insights we discuss our external communication and engagement activities including website email subscriptions, our draft annual audit work program, contribute to an audit, our transparency and accountability initiatives, and social media.
Contact
Please direct enquiries relating to Audit insights through our contact page.
Events and seminars
Updated: Monday 15 May 2023
Updated
The Australian National Audit Office and the ACT Audit Office, sponsored by the Australasian Council of Auditors-General (ACAG), hosted IMPACT 2023, the International Meeting of Performance Audit Critical Thinkers. The meeting was held 19–20 April 2023 in Canberra, Australia.
Contact
If you have any questions, please do not hesitate to contact us.
Performance audit (Auditor-General Report No. 24 of 2007–08)
Published: Tuesday 26 February 2008
Published
The audit objective was to determine whether DIAC's biometrics program had appropriate:
- business review processes (including a business case);
- authorisation;
- business and IT governance arrangements; and
- IT project management and systems development arrangements.
Entity
Department of Immigration and Citizenship
Performance audit (Auditor-General Report No. 21 of 2009–10)
Published: Thursday 4 February 2010
Published
The objective of this audit was to assess whether the WSA program has been administered effectively by the NWC/DEWHA, as relevant, and is achieving its stated program objective. Specifically, the ANAO examined whether:
- funding proposals have been assessed and approved in a fair, consistent manner and in accordance with applicable criteria, program guidelines and better practice;
- appropriate funding arrangements have been established with proponents, having regard to the size of the grant, the type of entity involved and the nature of the project; and
- DEWHA (and previously the NWC) is actively monitoring whether proponents are complying with their obligations, and grant payments are made only in accordance with funding agreements.
More broadly, the audit examined DEWHA's strategy for evaluating and reporting on the long-term benefits of the program.
Entity
Department of the Environment, Water, Heritage and the Arts; National Water Commission
Performance audit (Auditor-General Report No. 36 of 2010–11)
Published: Thursday 14 April 2011
Published
The audit objective was to assess the effectiveness of CRS Australia’s delivery of Disability Management Services. In assessing CRS Australia’s performance, the ANAO examined whether:
- services are delivered in accordance with CRS Australia’s operating procedures, which incorporate the Disability Services Standards and the requirements of the DEEWR MOU;
- CRS Australia has an effective client feedback (including complaints) system, which is used to identify and address business risks and areas for improving service delivery; and
- sound governance arrangements (including performance monitoring and reporting) are in place to monitor service delivery.
The audit did not specifically examine issues and information relating to the commercial nature of the business, such as profitability levels and competitive neutrality arrangements.
Entity
Department of Human Services
Performance audit (Auditor-General Report No. 10 of 2008–09)
Published: Tuesday 2 December 2008
Published
The objective of this audit was to assess whether the Scheme is being administered effectively by the department. The ANAO focussed on Program Year 1 of the Scheme, 2005–06, and examined DIISR's arrangements for:
- assessing the eligibility of entities to receive grants;
- assessing entities' claims for eligible expenditure;
- adhering to the funding limits for the Scheme when calculating and paying claims, and managing any debts that arise;
- and evaluating and reporting on whether the statutory objective of the Scheme is being met.
The audit did not examine the other components of the 2005–2015 industry assistance package; nor did it examine any of the programs delivered under the previous assistance package (2000–2005).
Entity
Department of Innovation, Industry, Science and Research
Performance audit (Auditor-General Report No. 27 of 2005–06)
Published: Monday 30 January 2006
Published
Parliamentary Committees, particularly Senate Estimates Committees, have for many years taken an interest in the use of consultants by Australian government agencies. In this context, and having regard to the extent of expenditure by FMA Act agencies on consultants, the objective of this audit was to assess the accuracy and completeness of Australian government agencies' reporting of expenditure on consultants.
Entity
across agency
Events and seminars
Published: Tuesday 28 August 2018
Published
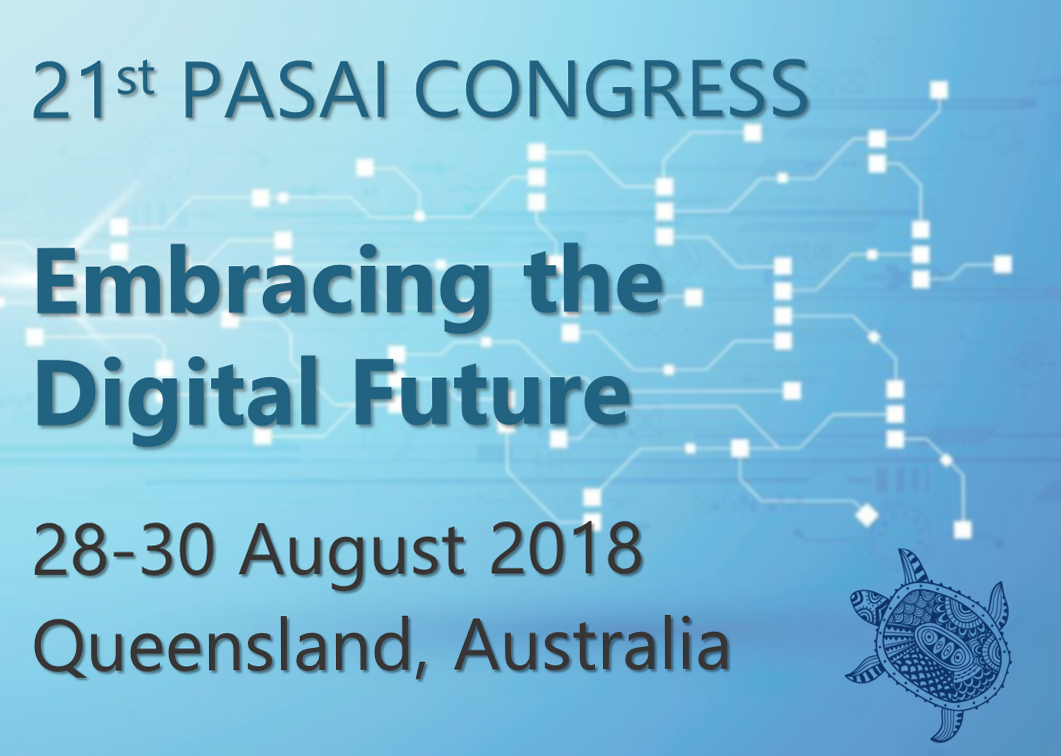
The Australian National Audit Office (ANAO) is hosting the 21st Pacific Association of Supreme Audit Institutions (PASAI) Congress 28–30 August 2018.