Browse our range of reports and publications including performance and financial statement audit reports, assurance review reports, information reports and annual reports.
Speeches and papers
Published: Monday 30 October 1995
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented to the Institute of Internal Auditors, Annual Directors' Forum, Canberra
Performance audit (Auditor-General Report No. 18 of 2000–01)
Published: Thursday 30 November 2000
Published
The audit assessed the management by ISR and, in particular, by AusIndustry of the implementation of the changes arising from the Government's December 1997 policy statement in Investing for Growth. This statement required ISR to separate administration of policy from the delivery of products and to improve its service to customers through a ‘one stop shop' approach and by streamlining its processes. The audit focussed in particular on the overall strategic management of the change process by AusIndustry; the detailed implementation of the new service delivery arrangements, notably the separation of policy and product delivery; and the implementation of the enhanced customer focus.
Entity
Department of Industry, Science and Resources
Speeches and papers
Published: Saturday 26 June 2004
Published
Mr P.J. Barrett (AO) - Auditor-General for Australia, an Occasional Paper
Performance audit (Auditor-General Report No. 46 of 2005–06)
Published: Wednesday 14 June 2006
Published
The objective of this follow-up audit was to review FaCSIA's progress in implementing the recommendations of Audit Report No.17 1999–2000. The focus was whether FaCSIA had maintained or improved its oversight, coordination and administration of the CSHA for both the 1999 CSHA and the 2003 CSHA, in line with the recommendations and findings identified in the previous ANAO audit.
Entity
Department of Families Community Services and Indigenous Affairs
Speeches and papers
Published: Friday 12 March 2004
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented to the Institute of Chartered Accountants of India
Speeches and papers
Published: Wednesday 26 April 2000
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented an Occasional Paper
Performance audit (Auditor-General Report No. 12 of 2000–01)
Published: Tuesday 3 October 2000
Published
The objective of the follow-up audit was to report on the action taken by the Australian Customs Service to address the recommendations of the 1996 Audit Report. The audit also reviewed key areas of the Passenger Movement Charge administration identified in the 1996 audit, including the appropriateness of formal arrangements between the ACS and Regular Public Transport airlines and assessed the proposed arrangements being developed by the ACS. The arrangements with RPT airlines were a particular focus in the follow-up report (as they were in the 1996 Audit Report), because of the significance of that category of carrier in revenue terms
Entity
Australian Customs Service
Performance audit (Auditor-General Report No. 16 of 2001–02)
Published: Friday 5 October 2001
Published
The Government introduced the Defence Reform Program (DRP) in 1997 to enable Defence's resources to be focused more efficiently and effectively on its core functions. The objective of the audit was to assess Defence's management and implementation of DRP and the extent to which it achieved savings for reinvestment in the operational capabilities of the ADF.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 24 of 2007–08)
Published: Tuesday 26 February 2008
Published
The audit objective was to determine whether DIAC's biometrics program had appropriate:
- business review processes (including a business case);
- authorisation;
- business and IT governance arrangements; and
- IT project management and systems development arrangements.
Entity
Department of Immigration and Citizenship
Performance audit (Auditor-General Report No. 3 of 2000–01)
Published: Monday 31 July 2000
Published
This audit is a follow-up to ANAO Audit Report No.31 1995-96 Environmental Management of Commonwealth Land: Site Contamination and Pollution Prevention (‘the original audit'). The objectives of the follow-up audit were to determine: the extent to which Defence has implemented the agreed recommendations contained in the original audit (relating to its environmental management and the management of unexploded ordnance (UXO) on non-Commonwealth land) and; the effectiveness of the implemented recommendations in improving the environmental management of Commonwealth land.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 45 of 1998–99)
Published: Wednesday 2 June 1999
Published
The audit is a follow-up to Audit Report 12, 1995-96 Risk Management by Commonwealth Consumer Product Safety Regulators. The objectives of this follow-up audit were to determine the extent to which ANZFA had implemented the agreed recommendations contained in the 1995 Audit Report, and to determine the effectiveness of the implemented recommendations in improving food safety regulation.
Entity
Australian New Zealand Food Authority
Performance audit (Auditor-General Report No. 40 of 2006–07)
Published: Wednesday 30 May 2007
Published
The previous audit made ten recommendations to improve Centrelink's review and appeals system. Centrelink agreed to all recommendations. The objective of this follow-up audit was to review Centrelink's progress in implementing the recommendations of Audit Report No.35, Centrelink's Review and Appeals System 2004-05.
Entity
Centrelink
Performance audit (Auditor-General Report No. 7 of 2004–05)
Published: Monday 9 August 2004
Published
The objective of the follow-up audit was to assess how well the ATO has implemented the recommendations of Audit Report No.3 of 2001-2002, The Australian Taxation Ofiice's Administration of Taxation Rulings. As part of the audit we also considered the ATO's progress in addressing the JCPAA's suggestions resulting from its review of Report No.3 of 2001-2002.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 34 of 2002–03)
Published: Monday 24 March 2003
Published
This audit followed up the ANAO's 1999 performance audit report on the Commonwealth's planning and response mechanisms to deal with exotic and new endemic pest and emergencies in the animal and plant sectors (Audit Report No 9 1999-2000 Managing Pest and Disease Emergencies). The previous audit made nine recommendations to improve planning and response strategies for emergencies; better coordination; diagnostic support; and appropriate monitoring and surveillance. The objective of the follow-up audit was to assess AFFA's implementation of the recommendations, and whether implementation of these recommendations, or appropriate alternative measures, has improved the Commonwealth's planning and response strategies for pest and disease emergencies. The ANAO also observed and assessed relevant parts of the September 2002 foot and mouth disease simulation, Exercise Minotaur.
Entity
Agriculture Fisheries and Forestry - Australia Department of Agriculture
Performance audit (Auditor-General Report No. 42 of 2004–05)
Published: Tuesday 19 April 2005
Published
The objective of this audit was to assess the extent to which the recommendations and major findings of the ANAO's 1999 audit of Commonwealth Debt Management have been addressed, and the impact of any changes.
Entity
Australian Office of Financial Management
Performance audit (Auditor-General Report No. 8 of 2003–04)
Published: Monday 20 October 2003
Published
The audit is a follow-up of ANAO Audit Report No.33 of 1997-98, which assessed the effectiveness and efficiency of the Commonwealth's management of the Great Barrier Reef and made seven recommendations for improvement. The objective of the follow-up audit was to assess the extent to which the Great Barrier Reef Marine Park Authority, which is responsible for advising the Commonwealth on the care and developement of the Marine Park, has implemented the recommendations of the earlier audit.
Entity
The Great Barrier Reef Marine Park Authority
Performance audit (Auditor-General Report No. 23 of 2009–10)
Published: Tuesday 23 February 2010
Published
The objective of the audit was to assess the effectiveness of Customs and Border Protection's performance in managing and coordinating enforcement operations against illegal foreign fishing in Australia's northern waters. The audit focused on Customs and Border Protection's role within the whole of government policy coordination framework; the effectiveness of its intelligence support for operational planning and policy and strategy development; its performance in planning, prioritising and administering effective enforcement operations; and its performance in measuring and reporting on the effectiveness of the program.
Entity
Australian Customs and Border Protection Service
Performance audit (Auditor-General Report No. 10 of 2008–09)
Published: Tuesday 2 December 2008
Published
The objective of this audit was to assess whether the Scheme is being administered effectively by the department. The ANAO focussed on Program Year 1 of the Scheme, 2005–06, and examined DIISR's arrangements for:
- assessing the eligibility of entities to receive grants;
- assessing entities' claims for eligible expenditure;
- adhering to the funding limits for the Scheme when calculating and paying claims, and managing any debts that arise;
- and evaluating and reporting on whether the statutory objective of the Scheme is being met.
The audit did not examine the other components of the 2005–2015 industry assistance package; nor did it examine any of the programs delivered under the previous assistance package (2000–2005).
Entity
Department of Innovation, Industry, Science and Research
Potential topic
Potential topic: 2027-29
Potential
The ANAO could assess the Department of Foreign Affairs and Trade’s design and administration of the Partnerships for Infrastructure (P4I) program. This could include the performance of the Commonwealth partners contracted to implement the program. P4I is Australia’s flagship infrastructure development in Southeast Asia. Funded through Australia’s development program, it works with eight Southeast Asian countries and ASEAN to manage and deliver new infrastructure worth over AUD $50 billion annually. P4I was initially implemented by EY, Adam Smith International, The Asia Foundation and Ninti One. P4I is transitioning to a new phase of the program which will involve new contracts.
Entity
Department of Foreign Affairs and Trade
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 60 of 2001–02)
Published: Thursday 20 June 2002
Published
In 1999-2000, the ANAO conducted an audit in Centrelink to determine whether its planning, monitoring and costing arrangements provided a sound basis to underpin its delivery of quality, cost effective customer services. The report of that audit, Audit Report No. 43 1999-2000 Planning and Monitoring for Cost Effective Service Delivery, Staffing and Funding Arrangements, was tabled in Parliament in May 2000. The objective of this follow-up audit was to assess whether Centrelink had implemented a comprehensive costing system as a basis for planning productivity improvements and accounting for its expenditure of purchaser funds. The ANAO examined Centrelink's current costing system to determine if it reflected the design and implementation characteristics that were outlined in Audit Report No. 43.
Entity
Centrelink
Performance audit (Auditor-General Report No. 36 of 2007–08)
Published: Thursday 29 May 2008
Published
The objective of the audit was to assess the Tax Office's strategies to address tax haven compliance risks. Particular emphasis was given to the Tax Office's:
- management arrangements relating to the administration of tax haven compliance risks;
- risk management framework for the identification and evaluation of compliance risks, specifically the activities of the Offshore Compliance Program (OCP); and
- risk mitigation strategies.
The audit did not include an examination of cases related to the promoters of tax haven related schemes nor the criminal use of tax havens.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 24 of 2002–03)
Published: Friday 20 December 2002
Published
The ANAO assessed agencies' progress in implementing the seven recommendations of Audit Report No.47 of 1998-99, Energy Efficiency in Commonwealth Operations. The Objectives of the follow-up audit were to
(i) asses the extent to which selected Commonwealth agencies have implemented the recommendations of Report No. 47 of 1998-1999, taking account of any changed circumstances or new administrative issues identified as impacting upon implementation of these recommendations; and
(ii) offer continued assurance to the Parliament on the management of Commonwealth agencies' compliance with the Commonwealth energy efficiency requirements, and to identify areas of better practice in energy management by those agencies.
Entity
Across Agency
Performance audit (Auditor-General Report No. 30 of 2006–07)
Published: Wednesday 14 March 2007
Published
The objectives of this follow-up audit were to:
- examine the ATO's implementation of the ten recommendations in The Australian Taxation Office's Management of its Relationship with Tax Practitioners (Audit Report No.19, 2002–03), having regard to any changed circumstances, or new administrative issues, affecting implementation of those recommendations; and
- identify scope for improvement in the ATO's management of its relationship with tax practitioners.
Follow up audits are recognised as an important element of the accountability processes of Commonwealth administration. Parliament looks to the Auditor General to report, from time to time, on the extent to which Commonwealth agencies have implemented recommendations of previous audit reports. Follow up audits keep Parliament informed of progressive improvements and current challenges in areas of Commonwealth administration that have previously been subject to scrutiny through performance audits.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 21 of 2016–17)
Published: Monday 17 October 2016
Published
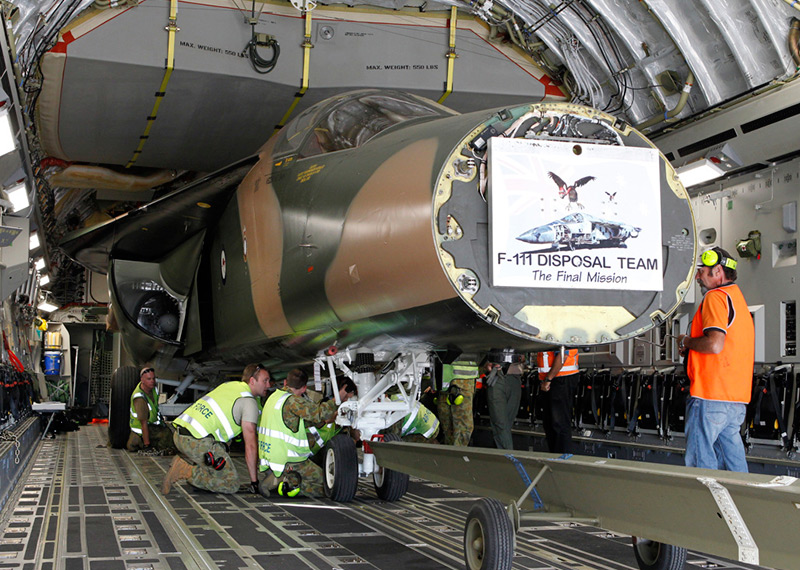
The audit objective was to assess Defence’s implementation of the five recommendations in ANAO Report No.19 2014-15 Management of the Disposal of Specialist Military Equipment and the related recommendation in JCPAA Report 449 Review of Auditor-General's Reports Nos. 1-23 (2014-15).
Entity
Department of Defence
Contact
Please direct enquiries relating to reports through our contact page.
Speeches and papers
Published: Friday 13 October 1995
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented to the International Consortium on Governmental Financial Management - Washington
Performance audit (Auditor-General Report No. 4 of 2000–01)
Published: Monday 14 August 2000
Published
This report summarises audit and other related activities of the Australian National Audit Office in the period January to June 2000.
Entity
Audit Activity Report
Speeches and papers
Published: Monday 8 October 2001
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented at the Third ACAG Conference, Canberra
Performance audit (Auditor-General Report No. 2 of 2003–04)
Published: Wednesday 13 August 2003
Published
The Audit Activity Report: January to June 2003 summarises the activity and outputs of the Australian National Audit Office for the second half of the 2002-03 reporting year. The Report outlines the key findings of performance and financial control audits, and summarises audits tabled and better practice guides published during January to June 2003.
Entity
Australian National Audit Office; Parliament
Performance audit (Auditor-General Report No. 42 of 2005–06)
Published: Thursday 25 May 2006
Published
The follow-up audit assessed the extent to which the Australian Taxation Office (ATO), Department of Health and Ageing (Health), and Medicare Australia had implemented the six recommendations from Audit Report No.47 2001–02, Administration of the 30 Per Cent Private Health Insurance Rebate. The audit also looked at: the implementation of some of the major suggestions for improvement in the original audit; and the current validity of some of the positive major findings from that audit. The audit found that the ATO, Health and Medicare Australia have acted upon the recommendations contained in Audit Report No.47 2001–02 and, overall, the administration of the Rebate is currently being undertaken effectively.
Entity
Australian Taxation Office; Department of Health and Ageing; Medicare Australia
Performance audit (Auditor-General Report No. 23 of 2004–05)
Published: Friday 21 January 2005
Published
The Audit Activity Report: July to December 2004 summarises the activity and outputs of the Australian National Audit Office for the first half of the 2004-05 reporting year. The Report outlines the key findings of performance and financial control audits, and summarises audits tabled and better practice guides during July to December 2004.
Entity
Audit Activity Report