Browse our range of reports and publications including performance and financial statement audit reports, assurance review reports, information reports and annual reports.
Performance audit (Auditor-General Report No. 14 of 2003–04)
Published: Friday 28 November 2003
Published
The Survey of Fraud Control Arrangements in APS agencies was conducted to identify improvements made by agencies since the 1999 survey, and in response to the revised Commonwealth Fraud Control Guidelines released in May 2002. Its objective was to assess the key aspects of fraud control arrangements in place across the APS against the Commonwealth Fraud Control Guidelines 2002.
Entity
Across Entities
Performance audit (Auditor-General Report No. 25 of 2005–06)
Published: Tuesday 24 January 2006
Published
The audit objective was to examine the effectiveness and efficiency of ASIC's implementation of Australian financial services licences. In particular, the audit examined ASIC's planning for the introduction of financial services licences; the roles of the Department of the Treasury (Treasury) and ASIC in defining the effective scope of licensing; ASIC's assessment and processing of licence applications; and ASIC's supervision of licensees.
Entity
Australian Securities and Investment Commission
Performance audit (Auditor-General Report No. 27 of 2003–04)
Published: Tuesday 10 February 2004
Published
The primary objective of the audit was to assess FaCS' management of the Internet portals for which it had responsibility as lead agency, www.youth.gov.au, www.community.gov.au, and www.families.gov.au. The ANAO also included in the audit a website directed towards youth. The source which provided many of the services expected of a portal. The audit considered governance structures for the portals; measurement of efficiency and effectiveness; and control factors, such as change management,security, and legal issues.
Entity
Department of Family and Community Services
Performance audit (Auditor-General Report No. 29 of 2010–11)
Published: Wednesday 16 February 2011
Published
The objective of the audit was to examine the effectiveness of the AFP's approach to its management of the implementation of NPIs.
Entity
Australian Federal Police
Performance audit (Auditor-General Report No. 43 of 2011–12)
Published: Tuesday 19 June 2012
Published
The objective of the audit was to assess the effectiveness of FaHCSIA's management of the Australian Government's responsibilities under the NPARSD. In this respect the ANAO considered whether:
- planning processes enabled effective establishment of the remote service delivery model;
- implementation of the key elements of the remote service delivery model effectively addressed the quality and timing requirements of the NPARSD; and
- performance measurement systems were developed to enable the parties to the agreement to assess whether the NPARSD objectives are being met.
Entity
Department of Families, Housing, Community Services and Indigenous Affairs
Performance audit (Auditor-General Report No. 40 of 1999–2000)
Published: Wednesday 26 April 2000
Published
Tactical fighter operations (TFOs) form the basis of Australia's current military capability to ensure air superiority. Air superiority over the Australian territory and maritime approaches is an essential element in Australia's defence strategy. The audit objectives were to:
- assess whether the resources used to provide the F/A-18 tactical fighter force operational capability are managed cost-effectively; and
- identify areas for improvement in the coordination, planning and practices employed in administration of tactical fighter operations.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 18 of 2010–11)
Published: Wednesday 8 December 2010
Published
The objective of the audit was to assess the administrative effectiveness of FaHCSIA's management of the GBM initiative, and the extent to which the initiative has contributed to improvements in community engagement and government coordination in the Northern Territory.
The audit focused on FaHCSIA's management of the GBM initiative under the NTER. The audit scope did not include additional functions assigned to some GBMs in the Northern Territory under the National Partnership Agreement on Remote Service Delivery (the National Partnership Agreement), or to Australian Government staff with similar roles and functions supporting the implementation of the National Partnership Agreement in Queensland and Western Australia.
Entity
Department of Families, Housing, Community Services and Indigenous Affairs
Performance audit (Auditor-General Report No. 51 of 2012–13)
Published: Monday 24 June 2013
Published
The objective of the audit was to assess the effectiveness of the Australian Taxation Office’s management of its property portfolio.
Entity
Australian Taxation Office
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 22 of 2005–06)
Published: Thursday 22 December 2005
Published
The objective of the audit was to assess and report on the progress being made by agencies subject to the Financial Management & Accountability Act 1997 and entities subject to the Commonwealth Authorities & Companies Act 1997: in realising value for money from the procurement process, with a specific focus on buildings, services and products using whole of life cycle assessments; and in the consideration and management of environmental impacts in specifications and contracts. The emphasis of the audit was on green office procurement and sustainable business practices and the value for money within this context. As such, the audit report provides a status report on the implementation of ESD within the office environment of the Australian Government. The audit used a survey approach in conjunction with selected audit investigations to obtain information across 71 agencies and entities selected on the basis of materiality in procurement and coverage across large, medium and small organisations. The agencies selected represented approximately 35 per cent of all government bodies and over 95 per cent of all procurement spending noted on the Department of Finance and Administration (Finance) database on contracts.
Entity
across agency
Performance audit (Auditor-General Report No. 61 of 2001–02)
Published: Tuesday 25 June 2002
Published
This benchmarking study across 14 agencies examined how line managers plan for and manage their staff and how the human resource (HR) function supports them to do that. People management was categorised into nine, practice areas, to enable comparisons between the participating agencies. The study also assessed each people management practice area against four criteria: quality, HR integration, effectiveness & efficiency and business contribution.
Entity
Across Agency
Performance audit (Auditor-General Report No. 30 of 2005–06)
Published: Tuesday 28 February 2006
Published
The objective of the audit was to assess the ATO's strategies to address tax evasion in the cash economy, with emphasis on: the ATO's strategic focus; aspects of governance, management processes and compliance activities; and responses to the ANAO Report No.35 2001–02 ATO Progress in Addressing the Cash Economy.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 36 of 2007–08)
Published: Thursday 29 May 2008
Published
The objective of the audit was to assess the Tax Office's strategies to address tax haven compliance risks. Particular emphasis was given to the Tax Office's:
- management arrangements relating to the administration of tax haven compliance risks;
- risk management framework for the identification and evaluation of compliance risks, specifically the activities of the Offshore Compliance Program (OCP); and
- risk mitigation strategies.
The audit did not include an examination of cases related to the promoters of tax haven related schemes nor the criminal use of tax havens.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 11 of 2006–07)
Published: Thursday 9 November 2006
Published
The objective of this audit was to assess DAFF's management of the contractual arrangements in place to deliver the National Food Industry Strategy. The audit assessed: implementation of the Strategy; financial management;assessment and selection of grants and projects; management of grants and projects; monitoring and verification of contract services; and performance management. The Australian National Audit Office (ANAO) examined a number of FIG applications and projects, one food centre of excellence and a major project under the Food Market Development programme. The audit did not examine the Food Chain programme or DAFF's administration of the Strategy's government-to-government activities.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 35 of 2002–03)
Published: Wednesday 26 March 2003
Published
The audit reviewed the Australian Customs Service (Customs) fraud control arrangements. The audit objective was to assess whether Customs has implemented appropriate fraud control arrangements consistent with the Commonwealth's Fraud Control Guidelines and the administrative effectiveness of these arrangements.
Entity
Australian Customs Service
Performance audit (Auditor-General Report No. 4 of 2009–10)
Published: Tuesday 15 September 2009
Published
The objective of this audit was to determine whether selected Australian Government organisations had effective processes for managing the annual leave entitlements of their staff, and whether systems and controls over the processing of annual leave were working as intended. In addressing this objective, the audit also assessed progress being made by the audited organisations in implementing the recommendations in ANAO Audit Report No.16 2005-06.
Entity
Australian Bureau of Statistics; Australian Taxation Office; Department of Broadband, Communications and the Digital Economy
Performance audit (Auditor-General Report No. 39 of 2005–06)
Published: Thursday 11 May 2006
Published
The objectives of the audit were to provide assurance that Artbank was effectively meeting its charter of: acquiring art by contemporary artists; expanding the number of public places that Artbank's collection is rented and displayed; and managing its collection and rental scheme. The audit also examined Artbank's governance arrangements, and its programmes for marketing, client development, performance management, budgeting, debt management and also sought client feedback on Artbank's operations via a survey.
Entity
Agriculture Fisheries and Forestry Australia; Department of Communications Information Technology and the Arts
Performance audit (Auditor-General Report No. 24 of 1997–98)
Published: Monday 15 December 1997
Published
The objective of the audit was to review the efficiency, economy and administrative effectiveness of departmental activities leading to the letting of the contract with SPCL and its subsequent administration. This included, among other things, an examination of action taken to protect the Commonwealth's interests and the adequacy of relevant departmental guidelines and processes. A primary aim of the audit was to identify the facts of the particular case, including any administrative inadequacies that led to unnecessary financial exposure for the Commonwealth and less than satisfactory outcomes. In particular, the audit aimed to identify elements of better practice that could be followed under similar circumstances or programs in the future.
Entity
Department of Education, Training and Youth Affairs
Speeches and papers
Published: Friday 18 May 2007
Published
Mr Ian McPhee - Auditor-General for Australia, presented at the Queensland Regional Heads Forum
Speeches and papers
Published: Friday 13 June 2003
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, address to the ACT Chapter of the Australasian Institute of Risk Management
Performance audit (Auditor-General Report No. 44 of 2011–12)
Published: Tuesday 19 June 2012
Published
The objective of the audit was to assess the effectiveness of the Department of Health and Ageing's support for improved access to integrated GP and primary healthcare services through its administration of the Primary Care Infrastructure Grants (PCIG) program.
Entity
Department of Health and Ageing
Performance audit (Auditor-General Report No. 36 of 2000–01)
Published: Friday 18 May 2001
Published
The objective of the audit was to form an opinion on ATSIC's management of the Municipal Services component of the Community Housing and Infrastructure Program (CHIP). The audit examined how effectively ATSIC specifies and implements its role, the adequacy with which it identifies relative needs for support from the program among Indigenous communities, and how it leverages improved outcomes from other potential funding sources.
Entity
Aboriginal and Torres Strait Islander Commission
Performance audit (Auditor-General Report No. 52 of 2005–06)
Published: Thursday 29 June 2006
Published
The audit objectives were to examine the extent to which selected TSB2 and TSI Response programs: are achieving or had achieved their objectives; and had been administered effectively by DCITA according to better practice principles. To evaluate this aspect, the audit assessed DCITA's compliance with the better practice principles outlined in the Administration of Grants Better Practice Guide (May 2002) produced by the Australian National Audit Office (ANAO). There are 19 separate principles covered under the broad areas of: Planning for effective grant programs; Selecting projects; Managing and monitoring funding deeds; and Evaluating and reporting grant program performance.
Entity
Department of Communications, Information Technology and the Arts
Performance audit (Auditor-General Report No. 36 of 2013–14)
Published: Thursday 5 June 2014
Published
The audit objective was to assess the effectiveness of the Parliamentary Budget Office in conducting its role since being established in July 2012.
Entity
Parliamentary Budget Office
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 49 of 2010–11)
Published: Tuesday 21 June 2011
Published
The objective of the audit was to assess the effectiveness of the ATO’s administration of the Fuel Tax Credits Scheme. Particular emphasis was given to the Fuel Scheme’s governance and reporting arrangements, risk management strategies and compliance management program.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 40 of 2001–02)
Published: Monday 8 April 2002
Published
The audit was undertaken following advice from the Joint Committee of Public Accounts and Audit (JCPAA) to the Auditor-General that assurance that ABC programming adequately reflects the ABC's Charter was an audit priority of Parliament. The objective of the audit is to provide Parliament with this assurance. The focus of the audit was on the governance arrangements of the ABC Board and management that enable the ABC to demonstrate the extent to which it is achieving its' Charter obligations, and other related statutory requirements, efficiently and effectively. The scope of the audit was as follows:
- Review the ABC's corporate governance framework against better practice models. The ANAO had regard to the ABC's unique role as a national public broadcaster established as a budget funded Commonwealth statutory authority subject to the Commonwealth Authorities and Companies Act 1997.
- Examine the ABC Board's approach to the interpretation of the Charter requirements of the ABC and the setting of strategic directions, and management's administrative arrangements for implementing the strategic directions established by the Board.
- Examine the ABC's performance information framework, the development, documentation and use of performance measures in relation to targets and/or objectives, the monitoring and reporting of performance and its' inter-relationship with the corporate planning and budgetary processes, particularly in relation to the strategic directions set by the Board.
The audit did not examine the overall management of the ABC. In keeping with the audit scope, the audit examined ways in which the ABC aligns its' strategic directions with its' Charter requirements for programs broadcast on radio, television and on-line and assures itself, and Parliament, about the achievement of its' Charter obligations. Further, the audit did not examine the operations of ABC Enterprises or symphony orchestras that operate as ABC-owned subsidiary companies.
Entity
Australian Broadcasting Corporation
Performance audit (Auditor-General Report No. 44 of 2003–04)
Published: Tuesday 27 April 2004
Published
The audit examined ATSIS' implementation of recommendations from Audit Report No.39, 1998-1999 National Aboriginal Health Strategy - Delivery of Housing and Infrastructure to Aboriginal and Torres Strait Islander Communities (the previous audit). In addition to assessing ATSIS' progress in implementing the recommendations of the previous audit, this follow-up audit examined ATSIS' performance reporting of the NAHS program, and concluded that the current level of aggregation of performance reporting makes it difficult to identify the particular contribution that the NAHS Program makes in improving services to Indigenous communities.
Entity
Aboriginal and Torres Strait Islander Services
Performance audit (Auditor-General Report No. 33 of 2008–09)
Published: Wednesday 20 May 2009
Published
The objective of the audit was to assess the effectiveness of the Tax Office's administration of the PRRT. The Australian National Audit Office (ANAO) identified four key areas for review: general administration; compliance; promoting certainty in administering the PRRT; and governance arrangements.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 17 of 2003–04)
Published: Thursday 4 December 2003
Published
An ANAO audit of AQIS' cost-recovery systems was conducted in 2000-01 (Audit Report No 10, 2000-01), following a request from the Joint Committee of Public Accounts and Audit (JCPAA). That audit aimed to assess the efficiency and effectiveness of the management of AQIS' cost-recovery systems, and provide assurance to Parliament that cost-recoverable programs were identifying and recovering the full costs of services provided, without cross-subsidisation. The ANAO made six recommendations for improving the efficiency and effectiveness of AQIS cost-recovery systems. The JCPAA, at a subsequent hearing, made a further three recommendations. The objective of the follow-up audit was to assess AQIS' implementation of the ANAO and the JCPAA recommendations. The audit also aimed to determine whether implementation of these recommendations, or alternative actions taken to address the issues leading to the recommendations, had improved AQIS' management of its cost-recovery processes.
Entity
Australian Quarantine and Inspection Service
Performance audit (Auditor-General Report No. 43 of 2003–04)
Published: Friday 23 April 2004
Published
The objective of the audit was to provide assurance to Parliament concerning the adequacy of Defence preparedness management systems and to identify possible areas for improvement. The audit focused on the systems and processes that Defence uses to manage preparedness. We did not review the preparedness levels of specific capabilities, nor did we cover capital acquisition processes. The audit included coverage of: - preparedness systems architecture; - control and direction of preparedness; - coordination among contributors to preparedness; and - performance management and preparedness.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 33 of 2011–12)
Published: Tuesday 22 May 2012
Published
The objective of the audit was to assess the effectiveness of DFAT's implementation of biometric technology to meet international requirements for enhanced passport security. In particular, the audit examined whether:
- Australian ePassports meet international requirements, and coordination with Australian stakeholders is effective;
- Australian biometric passport technology is fit for purpose and has enhanced passport security;
- personal data on the passport microchip is secure and DFAT maintains an appropriate focus on both protecting privacy and client satisfaction; and
- arrangements are in place to evaluate the effectiveness of the ePassport and to monitor risks.
Entity
Department of Foreign Affairs and Trade
Major projects report (Auditor-General Report No. 9 of 2008–09)
Published: Thursday 27 November 2008
Published
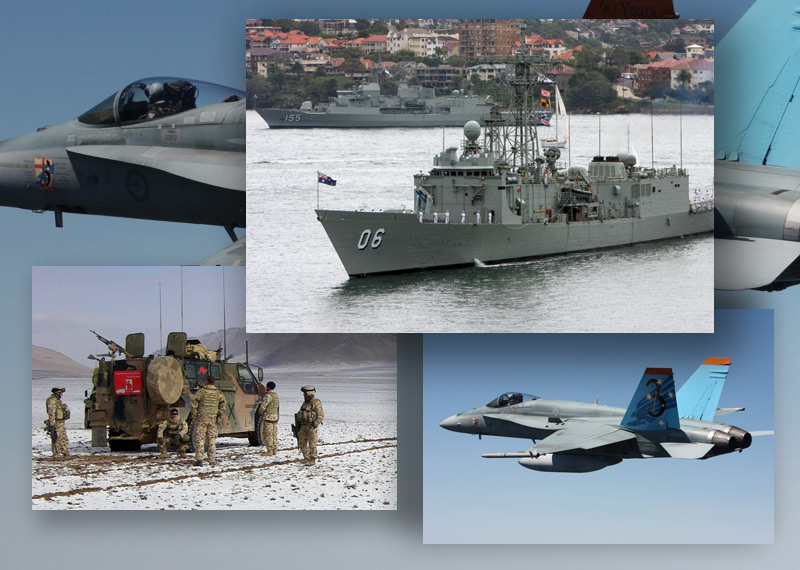
This first Assurance Report on the status of selected Defence equipment acquisition projects, which has the support of the Parliament and the Government, represents a substantial step towards improving transparency and public accountability in major Defence procurement projects. It is the pilot of an annual Defence Materiel Organisation (DMO) Major Projects Report, and was developed in conjunction with the DMO. It covers the cost, schedule and capability progress achieved by nine DMO projects, which had an approved budget totalling $13.535 billion as at 30 June 2008.
This report is organised into three parts. Part 1 comprises an ANAO overview and Auditor–General's Foreword. Part 2 comprises the Major Projects Report prepared by DMO, including an overview reflecting DMO's perspective on their business and on the nine projects included in the. Part 3 incorporates the Auditor-General's Review Report, the statement by the CEO DMO, and the information prepared by DMO in the form of standardised Project Data Summary Sheets covering each of the nine pilot projects.
In the next 12 months, the ANAO will review 15 DMO projects planned for inclusion in the 2008-09 DMO Major Projects Report, with the number of projects rising to 30 projects in subsequent years. The ANAO will also work with DMO to refine the approach adopted for providing assurance on each project's progress toward achieving Final Operational Capability. The ANAO will also consider the inclusion of an analysis of each project's emerging trends, as appropriate, to complement DMO's intention to provide improved analysis of project management performance regarding all projects included in the Major Projects Report.
Entity
Defence Materiel Organisation
Performance audit (Auditor-General Report No. 19 of 2005–06)
Published: Thursday 1 December 2005
Published
The objective of this audit was to assess the effectiveness of the actions taken by AQIS and BA to strengthen the administration of quarantine. The audit focussed on progress in implementing the recommendations from the previous ANAO audit, and recommendations made in the JCPAA's inquiry. (The audit did not address four JCPAA recommendations that were either not supported by the Government, or were policy matters for the Government to consider. See Appendix 1.)
Entity
Department of Agriculture Fisheries and Forestry; Biosecurity Australia
Performance audit (Auditor-General Report No. 35 of 2010–11)
Published: Wednesday 30 March 2011
Published
The objective of the audit was to assess the effectiveness of DFAT's management of the overseas leased estate. In particular, the audit examined whether DFAT:
- has effective governance, reporting and funding arrangements in place to support the sound management and oversight of the overseas leased estate;
- effectively manages overseas leased chancery and residential property on a day-to-day basis; and
- manages relationships with landlords and attached agencies effectively and adequately consults with stakeholders.
Entity
Department of Foreign Affairs and Trade
Speeches and papers
Published: Monday 7 October 2002
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented at the 18th Commonwealth Auditors-General Conference, Malaysia
Performance audit (Auditor-General Report No. 5 of 2003–04)
Published: Thursday 11 September 2003
Published
This report relates to the fourth audit of Financial Management and Accountability Act 1997 (FMA Act) agencies' compliance with the Order of the Senate for Departmental and Agency Contracts, (the Senate Order) to list, on the Internet, contract details for the reporting period 4 February 2002 to 3 February 2003. The audit was conducted in accordance with the Senate Order request for the Auditor-General to undertake twice-yearly examinations of agency contracts listed on the Internet, and to report whether there had been any inappropriate use of confidentiality provisions. The objectives of the audit were to assess agency performance in relation to compiling the Internet listings required by the Senate Order and the appropriateness of the use of confidentiality provisions in Commonwealth contracts.
Entity
Australian Federal Police (AFP);; Australian Greenhouse Office (AGO);; Department of Defence (Defence);; Department of Employment and Workplace Relations (DEWR);; Department of Family and Community Services (FaCS);1 and; National Capital Authority (NCA)
Performance audit (Auditor-General Report No. 23 of 2011–12)
Published: Tuesday 7 February 2012
Published
The objective of the audit was to assess the effectiveness of the Department of Climate Change and Energy Efficiency’s implementation and administration of the National Greenhouse and Energy Reporting Scheme.
Entity
Department of Climate Change and Energy Efficiency
Performance audit (Auditor-General Report No. 54 of 2011–12)
Published: Wednesday 27 June 2012
Published
The objective of the audit was to assess the effectiveness of the ATO’s administration of external debt collection arrangements.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 12 of 2002–03)
Published: Monday 21 October 2002
Published
The IIF program is designed to redress the low level of provision in Australia of high risk venture capital for small new technology - based companies commercialising research and development. The objective of the audit was to determine whether the IIF program was being effectively managed by the Industry Research and Development (IR&D) Board and the Department of Industry, Tourism and Resources to achieve the program objectives. The audit focused on corporate governance arrangements for program administration, the selection process to award licences, the safeguards to protect the Commonwealth's financial interests, management of licence agreements, and program performance management. The audit also examined program results to date from available data.
Entity
Department of Industry, Tourism and Resources; Industry Research and Development Board
Performance audit (Auditor-General Report No. 25 of 2004–05)
Published: Tuesday 1 February 2005
Published
The audit examined the relationship between the strategic guidance and capabilities provided by Army, through analysis of the Army capability management and reporting framework. The objectives of the audit were to: Assess Army capability management and reporting processes; determine whether these processes efficiently and effectively manage resources to provide Army capability; and accurately indicate the capability provided by Army.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 6 of 2000–01)
Published: Wednesday 23 August 2000
Published
The objective of the audit was to assess the framework and systems that DHAC has in place to prevent, control, monitor, detect and investigate fraud. The ANAO concluded that DHAC had taken appropriate steps to protect Commonwealth resources under its administration from fraudulent misappropriation by developing a sound fraud control framework, the effectiveness of which is illustrated by the relatively low incidence of reported fraud in the department over the last few years. The framework also includes key elements for preventing and dealing with fraud in line with the Commonwealth's Fraud Control Policy.
Entity
Department of Health and Aged Care
Performance audit (Auditor-General Report No. 58 of 2002–03)
Published: Thursday 26 June 2003
Published
This was a follow-up of Audit Report No. 29 2000-01, Review of Veterans' Appeals Against Disability Compensation Entitlement Decisions. That audit examined the Department of Veterans' Affairs (DVA's) and the Veterans' Review Board's (VRB's) management of the review of decisions for disability compensation. The objective of this audit was to assess the extent to which DVA and the VRB had implemented the four recommendations of Report No.29 2000-01, taking into account any changed circumstances, or new administrative issues, affecting implementation of these recommendations.
Entity
Department of Veterans' Affairs; Veterans' Review Board
Performance audit (Auditor-General Report No. 33 of 2013–14)
Published: Thursday 29 May 2014
Published
The objective of this audit was to determine whether Australian Government entities were implementing effective strategies to support increased Indigenous employment.
Entity
Across Agencies
Contact
Please direct enquiries relating to reports through our contact page.
Speeches and papers
Published: Friday 23 August 2002
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented at the Forum of Commonwealth Agencies Seminar, Sydney, NSW
Speeches and papers
Published: Thursday 28 February 2002
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, Address to University of Canberra Students - Graduate Certificate in Performance Audit
Performance audit (Auditor-General Report No. 51 of 1999–2000)
Published: Thursday 29 June 2000
Published
The objective of the audit was to examine program management in the Training and Youth Division of the Department of Education, Training and Youth Affairs. In broad terms, the audit focused on the management frameworks at both Divisional and program level. Three of the Division's programs were selected for more detailed review as follows:
- Workplace English Language and Literacy;
- Literacy and Numeracy; and
- Support for New Apprentices.
Entity
Department of Education, Training and Youth Affairs
Performance audit (Auditor-General Report No. 19 of 2003–04)
Published: Wednesday 17 December 2003
Published
The objective of the audit was to assess whether the property management function, including the management of leases, was being performed efficiently and was providing an effective level of support for the delivery of the organisation's services (outputs). The audit evaluated property management policies and practices across the following dimensions:
- planning and control;
- business processes and practices; and
- information and performance management.
Within each of these areas, a series of desirable proceses and controls (described as the evaluation criteria) were developed to assist in the assessment of each organisation's performance.
Entity
Australian Communications Authority; Australian Film, Television and Radio School; Civil Aviation Safety Authority; Department of Employment and Workplace Relations; National Library of Australia; Department of Finance and Administration
Performance audit (Auditor-General Report No. 6 of 2002–03)
Published: Thursday 29 August 2002
Published
The ANAO reviewed arrangements for the development of the department's fraud policy, fraud risk assessment and fraud control plan within the core functional areas of the department that are responsible for these activities. The audit also examined the operational procedures and guidelines that were in place to implement the departments' fraud policy. The objective of the audit was to assess whether DVA has implemented appropriate fraud control arrangements in line with the Fraud Control Policy of the Commonwealth and whether these arrangements operate effectively in practice.
Entity
Department of Veterans' Affairs
Performance audit (Auditor-General Report No. 15 of 2005–06)
Published: Tuesday 15 November 2005
Published
The objective of the audit was to assess the Commonwealth's administration of the grants component of the R&D Start program. Lessons for the new Commercial Ready program have been identified in the audit. Accordingly, recommendations arising from this audit are directed, when appropriate, to the Commercial Ready program. As most financial assistance is in the form of grants, the loans component of the program was excluded from the audit.
Entity
Department of Industry Tourism and Resources; Industry Research and Development Board
Performance audit (Auditor-General Report No. 48 of 1997–98)
Published: Monday 22 June 1998
Published
The objective of the audit was to assess the efficiency, effectiveness and accountability of data management by government agencies. The audit focused mainly on data collected by departments and agencies from non-departmental organisations and institutions.
Entity
Across Agency
Speeches and papers
Published: Tuesday 2 December 1997
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented at the launch of Comcare/ANAO Better Practice Guide
Performance audit (Auditor-General Report No. 10 of 2003–04)
Published: Monday 27 October 2003
Published
As part of its 2001 inquiry into the recruitment and retention of Australian Defence Force (ADF) personnel, the Senate Foreign Affairs, Defence and Trade References Committee reviewed Defence's contract with Manpower Services (Australia) Pty Ltd for trialling the outsourcing of recruiting services to the ADF. In its subsequent report, the Committee commented that the original contractual arrangements deserved further scrutiny by the ANAO. The objective of the audit was to examine Defence's management of the contractual arrangements for the provision of recruiting services to the ADF. In examining the management of the contract, the ANAO looked at the evaluations conducted at the end of each contractual phase, roles and responsibilities associated with ADF recruiting, and Defence's monitoring of contractual performance and management of risks associated with ADF recruiting.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 49 of 2002–03)
Published: Tuesday 17 June 2003
Published
The audit reviewed the Australian Maritime Safety Authority's management of the navigation aids network, which is an important factor in shipping safety. The objectives of the audit were to determine whether AMSA's management of the network provides for the strategic needs of marine navigation in Australian waters, and whether AMSA's management was efficient and effective. The audit focused on AMSA's strategic planning, the management of revenue and expenditure to support the network, its contract management practices, and its accountability and performance reporting arrangements.
Entity
Australian Maritime Safety Authority
Speeches and papers
Published: Thursday 12 August 1999
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented at the Health Insurance Commission Senior Management Group
Performance audit (Auditor-General Report No. 36 of 2003–04)
Published: Thursday 25 March 2004
Published
The audit assessed the Commonwealth's administration of the two major elements of the Dairy Industry Adjustment Package; the Dairy Structural Adjustment Program (DSAP) and the supplementary Dairy Assitance Program (SDA). The audit addressed the implementation and delivery of the programs, governance arrangements and the management of the Dairy Structural Adjustment Fund.
Entity
Department of Agriculture Fisheries and Forestry; Dairy Adjustment Package
Performance audit (Auditor-General Report No. 35 of 1998–99)
Published: Monday 19 April 1999
Published
The audit objective was to determine the DVA's performance in the economy, efficiency and administrative effectiveness of the delivery of income support payments to veterans and war widows. It was found that overall, DVA is paying the correct pension to the correct people in a timely fashion within the required accuracy levels.
Entity
Department of Veterans' Affairs
Performance audit (Auditor-General Report No. 36 of 1998–99)
Published: Wednesday 28 April 1999
Published
The objective of the audit was to assess key aspects of the Australian Taxation Office's administration of the PAYE system in relation to employers' remittances and to identify opportunities for improvement. The audit focussed on four areas:
- remittance monitoring, especially managing late remittances;
- follow-up action for end of year reconciliation, including discrepancies;
- handling compliance intelligence gained from the public; and
- ATO compliance projects.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 30 of 2008–09)
Published: Wednesday 29 April 2009
Published
The objective of the audit was to assess the arrangements for oversighting the Action Plan and whether the Plan's new measures have been administered effectively to deliver the intended results.
Entity
Attorney-General's Department; Department of Immigration and Citizenship; Australian Federal Police; Department of Families, Housing, Community Services and Indigenous Affairs
Performance audit (Auditor-General Report No. 43 of 2001–02)
Published: Tuesday 23 April 2002
Published
To improve educational outcomes for Indigenous Australians, two main forms of assistance administered by the Commonwealth, namely the Indigenous Education Strategic Initiatives Programme (IESIP) and the Indigenous Education Direct Assistance programmes (IEDA), are currently available. The objective of the audit was to assess whether the department had efficiently and effectively managed the development and implementation of the IESIP agreements for the 2001 to 2004 quadrennium.
Entity
Department of Education Science and Training
Performance audit (Auditor-General Report No. 33 of 1997–98)
Published: Monday 23 February 1998
Published
The objective of this audit was to assess the efficiency and effectiveness of the Commonwealth's management of the Great Barrier Reef as implemented by the Authority. This audit was undertaken because of the environmental significance of the Great Barrier Reef Region; its growing economic importance; recent changes to the Authority's budget arrangements; and because the Authority had not been subject to a performance audit since its establishment approximately 20 years ago.
Entity
Great Barrier Reef Marine Park Authority
Performance audit (Auditor-General Report No. 49 of 2001–02)
Published: Monday 13 May 2002
Published
The audit reviewed Commonwealth National Parks involving total assets of $105 million with net operating costs of $41.77 million. Nineteen Commonwealth reserves are declared comprising six terrestrial national parks, one botanic garden and twelve marine parks and reserves totalling some 23 million hectares across Australia, its external territories and Commonwealth marine areas. The objective of the audit was to examine and report on the adequacy of the planning, management and reporting systems which support the Director of National Parks in the achievement of required functions under relevant legislation and agreed outputs and outcomes.
Entity
Department of the Environment and Heritage