Browse our range of reports and publications including performance and financial statement audit reports, assurance review reports, information reports and annual reports.
Events and seminars
Published: Friday 17 July 2026
Published
An Audit Committee Chairs Forum was held on Friday 17 July 2026. This communique summarises key messages, discussion themes and practical considerations for audit and risk committees arising from the forum.
Contact
For any enquiries, please contact External.Relations@anao.gov.au
Insights: Audit practice
Published: Thursday 26 April 2018
Published
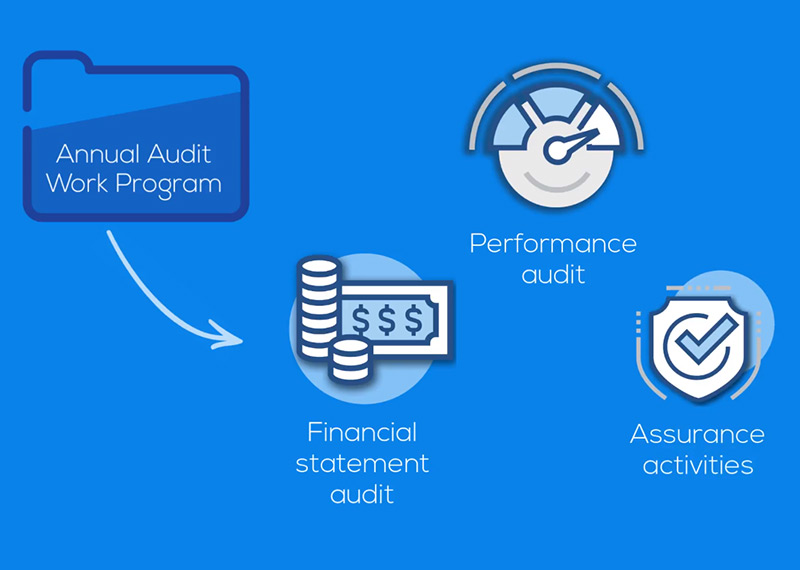
The Auditor-General publishes an annual audit work program in July each year, which takes regard of the priorities of the Parliament as outlined in the Auditor-General Act. The purpose of the program is to inform the Parliament, government sector entities and the public of the audits we propose to deliver throughout the financial year. The program covers financial statement and performance audits, and other assurance activities.
Contact
Please direct enquiries relating to audit insights through our contact page.
Performance audit (Auditor-General Report No. 66 of 2001–02)
Published: Friday 28 June 2002
Published
The audit followed-up the ANAO's original audit report into the aviation safety regulatory activities of the Civil Aviation Safety Authority (CASA) (Audit Report No.19 1999-2000 Aviation Safety Compliance). The objective of the follow-up audit were to determine, in respect of issues addressed by the original audit recommendations, whether CASA has made satisfactory progress to improve its aviation safety surveillance and compliance activities; and whether the introduction of new strategies for further improvement is being appropriately managed.
Entity
Civil Aviation Safety Authority
Performance audit (Auditor-General Report No. 32 of 2001–02)
Published: Thursday 14 February 2002
Published
This follow-up Audit reviewed the Department of Health and Ageing's implementation of the recommendations of Audit Report No. 36, 1999-2000, Home and Community Care. The objective of the follow-up audit was to assess the extent to which the Department had implemented the nine recommendations of Audit Report No. 36, 1999-2000. The audit examined areas relating to funding, guidance, fees, coordination with other aged and disability care programs, acquittals, accountability and data requirements, and records management.
Entity
Department of Health and Ageing
Performance audit (Auditor-General Report No. 28 of 2003–04)
Published: Thursday 12 February 2004
Published
The report summarises performance audit, financial statement audit and other related activities for the ANAO for the period July to December 2003. The key issues arising from performance audits tabled in this period are summarised against the ANAO themes. The report also summarises financial audits and other financial audit activities conducted by the ANAO during the period July to December 2003. It discusses significant issues such as the: consolidated financial statements and the final budget outcome; harmonisation of Australian Generally accepted accounting practices and Government Finance Statistics; adoption of International Financial Reporting Standards; timing for Financial Statements Preparation; and the audit of the CFS 2002-03.
Entity
ANAO
Performance audit (Auditor-General Report No. 12 of 2000–01)
Published: Tuesday 3 October 2000
Published
The objective of the follow-up audit was to report on the action taken by the Australian Customs Service to address the recommendations of the 1996 Audit Report. The audit also reviewed key areas of the Passenger Movement Charge administration identified in the 1996 audit, including the appropriateness of formal arrangements between the ACS and Regular Public Transport airlines and assessed the proposed arrangements being developed by the ACS. The arrangements with RPT airlines were a particular focus in the follow-up report (as they were in the 1996 Audit Report), because of the significance of that category of carrier in revenue terms
Entity
Australian Customs Service
Performance audit (Auditor-General Report No. 31 of 2002–03)
Published: Wednesday 5 March 2003
Published
This audit followed up the ANAO's 2000 performance audit report on retention of military personnel (Audit Report No.35 1999-2000 Retention of Military Personnel), which focused on examining whether ADF personnel management practices to retain personnel were commensurate with the cost of recruiting and training new personnel, or whether more cost- effective steps could be taken to reduce the separation rates of desirable personnel. The objective of the follow-up audit was to assess Defence's implementation of recommendations made in the original audit report and their effectiveness in helping Defence control the flow of trained personnel from the Services.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 23 of 2018–19)
Published: Thursday 17 January 2019
Published
The objective of this audit was to assess the extent to which the Department of Agriculture and Water Resources (Agriculture) has addressed the recommendations from ANAO Audit Report No. 46 of 2011–12, Administration of the Northern Australia Quarantine Strategy (NAQS).
Entity
Department of Agriculture and Water Resources
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 13 of 2002–03)
Published: Wednesday 23 October 2002
Published
This benchmarking study was a follow on from ANAO Report No. 14 of 2000-01, Benchmarking the Internal Audit Function, which was published in October 2000. The objective of the study was to obtain and report qualitative and quantitative data on aspects of the internal audit function and compare the public sector internal audit results with equivalent international data to identify better practices and highlight areas for improvement.
Entity
Across Agency
Performance audit (Auditor-General Report No. 7 of 2001–02)
Published: Thursday 9 August 2001
Published
The report summarises the audit and other related activities of the ANAO in the period January to June 2001. Key issues arising from performance audits tabled in this period are summarised against ANAO themes of:
- corporate governance including human resource management, financial management, and performance information;
- service delivery including the impact of e-government;
- procurement and contract management; and
- information technology.
Appendix 1 of the Activity Report provides a short summary of each of the performance audits tabled between 1 January 2001 and 30 June 2001.
Entity
NO-DEPTS-LISTED
Events and seminars
Published: Wednesday 30 October 2024
Published
The Australian National Audit Office, in partnership with the Australian Capital Territory Audit Office hosted the 12th Meeting of the Pacific Association of Supreme Audit Institution’s (PASAI) Regional Working Group on Environmental Auditing. The meeting was held from 17-19 September 2024 in Canberra, Australia.
Contact
For any enquiries, please contact External.Relations@anao.gov.au
Performance audit (Auditor-General Report No. 6 of 2001–02)
Published: Thursday 9 August 2001
Published
This follow-up audit reviewed the operations of the Australian Fisheries Management Authority (AFMA) which is responsible for ensuring the sustainable use and efficient management of Commonwealth fisheries resources. The objective of this follow-up audit was to assess the extent to which AFMA addressed the issues that gave rise to the recommendations of ANAO Report No.32 1995-96, and the related recommendations of the House of Representatives Standing Committee Report 1997, that were supported by the Government.
The follow-up audit focussed on the key issues identified in the recommendations and grouped these in the themes of:
- strategic and performance management;
- management of the advisory process;
- implementation of fisheries management methods;
- managing AFMA's environmental responsibilities as they relate to Commonwealth fisheries
management; - compliance, monitoring and enforcement responsibilities; and
- management of information and research.
Entity
Australian Fisheries and Management Authority
Parliamentary briefing (48th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
JCPAA’s review of Auditor-General reports
Parliamentary briefing (48th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Australasian Council of Auditors General Independence of the Australasian Auditors General Report 2025
Parliamentary briefing (48th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Audit reports included in the Inquiry into the management of client privacy in the Australian public sector
Parliamentary briefing (48th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Audit reports included in the Inquiry into the administration of the Age Pension
Parliamentary briefing (48th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Audit reports included in the Inquiry into Defence’s Procurement of Infantry Fighting Vehicles (Land 400 Phase 3)
Parliamentary briefing (48th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Private briefing to the JCPAA on the audit reports included in the inquiry into the 2023-24 and 2024-25 Major Projects Reports
Parliamentary briefing (48th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Draft 2026–27 Annual Audit Work Program
JCPAA’s review of Auditor-General reports
Parliamentary briefing (48th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Private briefing to the JCPAA on the audit reports included in the inquiry into the National Disability Insurance Scheme.
Parliamentary briefing (48th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Introduction to Commonwealth Financial Statements Auditing and principal matters arising from the 2023–24 audits
Parliamentary briefing (48th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Auditor-General Report No.27 of 2024–25: Sport Integrity Australia’s Management of the National Anti-Doping Scheme
Auditor-General Report No.44 of 2024–25: Conduct of Procurements Relating to Two New Child Sexual Abuse-related National Services
Parliamentary briefing (47th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
ANAO 2025-26 Budget Submission
Parliamentary briefing (47th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Defence Major Projects Report 2024–25 Proposed Guidelines and Project Selection.
Parliamentary briefing (47th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Auditor-General Report No.21 2023–24 Management of the Australian War Memorial’s Development Project
Auditor-General Report No.36 2023–24 Procurement of My Health Record
Auditor-General Report No.37 2023–24 Administration of the Adult Migrant English Program contracts
Auditor-General Report No.47 2023–24 Defence's management of contracts for the supply of munitions: Part 1
Auditor-General Report No.1 2024–25 Defence's Procurement and Implementation of the myClearance System
Parliamentary briefing (47th Parliament)
Briefing date
Recipient
Joint Committee on Public Accounts and Audits
Topic
Private briefing to the JCPAA on the audit reports included in the Inquiry into the administration of Commonwealth regulations
Parliamentary briefing (47th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Auditor-General Report No.42 2021–22 Procurement of Delivery Partners for the Entrepreneurs’ Programme
Auditor-General Report No.5 2022–23 Digital Transformation Agency’s Procurement of ICT-Related Services
Auditor-General Report No.39 2021–22 Overseas Crisis Management and Response
Parliamentary briefing (47th Parliament)
Briefing date
Recipient
Joint Committee on Public Accounts and Audits
Topic
2022–23 Defence Major Projects Report
Commonwealth Financial Statements 2022–23
Public sector IT procurements and projects, namely:
- Auditor-General Report No.7 2023–24 Establishment of the Workforce Australia Services Panel, on the digital employment services system
- Auditor-General Report No.20 2023–24 Design and Implementation of the Australian Apprenticeships Incentive System
- Auditor-General Report No.12 2023–24 Administration of the Parliamentary Expenses Management System
Parliamentary briefing (47th Parliament)
Briefing date
Recipient
Joint Committee on Public Accounts and Audits
Topic
Review of Auditor-General reports
Parliamentary briefing (47th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
ANAO 2024–25 Budget Submission
Parliamentary briefing (47th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Inquiry into Policy and Program Design and Implementation
Parliamentary briefing (47th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Defence Major Projects Report 2023-24 Proposed Guidelines and Project Selection
Parliamentary briefing (47th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Inquiry into probity and ethics in the Australian Public Sector
Parliamentary briefing (47th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
Defence Major Projects Report 2020–21 and 2021–22
Parliamentary briefing (47th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
2022–23 Defence Major Projects Report guidelines and proposed project selections
Parliamentary briefing (47th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit
Topic
ANAO October 2022–23 budget submission and the Auditor-General’s batch reports
Performance audit (Auditor-General Report No. 17 of 2003–04)
Published: Thursday 4 December 2003
Published
An ANAO audit of AQIS' cost-recovery systems was conducted in 2000-01 (Audit Report No 10, 2000-01), following a request from the Joint Committee of Public Accounts and Audit (JCPAA). That audit aimed to assess the efficiency and effectiveness of the management of AQIS' cost-recovery systems, and provide assurance to Parliament that cost-recoverable programs were identifying and recovering the full costs of services provided, without cross-subsidisation. The ANAO made six recommendations for improving the efficiency and effectiveness of AQIS cost-recovery systems. The JCPAA, at a subsequent hearing, made a further three recommendations. The objective of the follow-up audit was to assess AQIS' implementation of the ANAO and the JCPAA recommendations. The audit also aimed to determine whether implementation of these recommendations, or alternative actions taken to address the issues leading to the recommendations, had improved AQIS' management of its cost-recovery processes.
Entity
Australian Quarantine and Inspection Service
Audit manual
Updated: Thursday 20 August 2026
Updated
The Performance Audit Services Group (PASG) volume of the ANAO Audit Manual applies to the performance audit activity performed by PASG in collaboration with the Systems Assurance and Data Analytics (SADA) group. Relevant policies and guidance from the PASG volume are also applied to assurance reviews performed by PASG. Policies and guidance in the PASG volume address the planning, execution and reporting stages of the performance audit process.
Contact
Please direct enquiries through our contact page.
Audit manual
Updated: Thursday 20 August 2026
Updated
The Performance Statements Audit Services Group (PSASG) volume of the ANAO Audit Manual applies to the performance statements audit activity performed by PSASG.
Contact
Please direct enquiries through our contact page.
Audit manual
Updated: Thursday 20 August 2026
Updated
The shared content volume of the ANAO Audit Manual applies to all assurance activity performed by the ANAO, including financial statements and performance auditing. The shared volume addresses key matters affecting compliance with the Auditor-General Act 1997 and other aspects of the ANAO’s legislative framework. It sets out the main requirements of the ANAO’s overall system of quality control in accordance with ASQC1 Quality Control for Firms that Perform Audits and Reviews of Financial Reports and Other Financial Information, Other Assurance Engagements and Related Services Engagements.
Contact
Please direct enquiries through our contact page.
Corporate
Published: Monday 11 December 2023
Published
Quality in the delivery of the ANAO’s audit services is critical in supporting the integrity of our audit reports and maintaining the confidence of the Parliament and public sector entities. The ANAO corporate plan is the ANAO’s primary planning document. It outlines our purpose; the dynamic environment in which we operate; our commitment to building capability; and the priorities, activities and performance measures by which we will be held to account. The ANAO quality management framework and plan complements the corporate plan. It describes the ANAO’s system of quality management and reflects the ANAO’s responses to identified quality risks.
The ANAO Quality Management Framework is the ANAO’s established system of quality management to provide the Auditor-General with reasonable assurance that the ANAO complies with the ANAO Auditing Standards and applicable legal and regulatory requirements, and reports issued by the ANAO are appropriate in the circumstances.
This audit quality report sets out the Auditor-General’s evaluation on the implementation and operating effectiveness of the ANAO Quality Management Framework. The report:
- provides transparency in respect of the processes, policies, and procedures that support each element of the ANAO Quality Management Framework;
- outlines ANAO performance against benchmarks on audit quality indicators; and
- outlines the ANAO’s performance against the quality assurance strategy and deliverables set out in the Quality Management Framework and Plan 2022–23.
Contact
Please direct enquiries through our contact page.
Corporate
Published: Friday 1 November 2024
Published
Quality in the delivery of the ANAO’s audit services is critical in supporting the integrity of our audit reports and maintaining the confidence of the Parliament and public sector entities. The ANAO Corporate Plan is the ANAO's primary planning document. It outlines our purpose; the dynamic environment in which we operate; our commitment to building capability; and the priorities, activities and performance measures by which we will be held to account. The ANAO Quality Management Framework and Plan complements the Corporate Plan. It describes the ANAO’s system of quality management and reflects the ANAO's responses to identified quality risks.
The ANAO Quality Management Framework is the ANAO’s established system of quality management to provide the Auditor-General with reasonable assurance that the ANAO complies with the ANAO Auditing Standards and applicable legal and regulatory requirements, and reports issued by the ANAO are appropriate in the circumstances.
This Audit Quality Report sets out the Auditor-General’s evaluation on the implementation and operating effectiveness of the ANAO Quality Management Framework. The report:
- provides transparency in respect of the processes, policies, and procedures that support each element of the ANAO Quality Management Framework;
- outlines ANAO performance against benchmarks on audit quality indicators; and
- outlines the ANAO’s performance against the quality assurance strategy and deliverables set out in the Quality Management Framework and Plan 2023–24.
Contact
Please direct enquiries through our contact page.
Corporate
Published: Monday 20 October 2025
Published
Quality in the delivery of the ANAO’s audit services is critical in supporting the integrity of our audit reports and maintaining the confidence of the Parliament and public sector entities. The ANAO Corporate Plan is the ANAO’s primary planning document. It outlines our purpose; the dynamic environment in which we operate; our commitment to building capability; and the priorities, activities and performance measures by which we will be held to account. The ANAO Quality Management Framework and Plan complements the Corporate Plan. It describes the ANAO’s system of quality management and reflects the ANAO’s responses to identified quality risks.
The ANAO Quality Management Framework is the ANAO’s established system of quality management to provide the Auditor-General with reasonable assurance that the ANAO complies with the ANAO Auditing Standards and applicable legal and regulatory requirements, and reports issued by the ANAO are appropriate in the circumstances.
This Audit Quality Report sets out the Auditor-General’s evaluation on the implementation and operating effectiveness of the ANAO Quality Management Framework. The report:
- provides transparency in respect of the processes, policies, and procedures that support each element of the ANAO Quality Management Framework;
- outlines ANAO performance against benchmarks on audit quality indicators; and
- outlines the ANAO’s performance against the quality assurance strategy and deliverables set out in the Quality Management Framework and Plan 2024-25.
Contact
Please direct enquiries through our contact page.
Audit manual
Updated: Thursday 20 August 2026
Updated
The Financial Statements Audit Services Group (FSASG) volume of the ANAO Audit Manual applies to the financial statement audit activity performed by FSASG in collaboration with the Systems Assurance and Data Analytics (SADA) group. Relevant policies and guidance from the FSASG volume are also applied to other assurance work performed by FSASG. Policies and guidance in the FSASG volume address the planning, execution and reporting stages of the financial statement audit process.
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 45 of 2003–04)
Published: Thursday 29 April 2004
Published
The objective of the current audit was to assess Army's progress in implementing the ANAO recommendations and to examine and assess any developments in relation to AIRN since the 1999?2000 audit report and the 2001 JCPAA report. Army updated AIRN policy in 2001 and 2004, and the ANAO has assessed, where appropriate, the implementation of the 1999?2000 audit recommendations for these two policy reissues.
Entity
Department of Defence
Request for audit
Responded: Friday 26 April 2019
Response provided
The Auditor-General responded on 26 April 2019 to correspondence from Dr Kerryn Phelps AM, MP and co-signatories dated 10 April 2019, requesting that the Auditor-General conduct an investigation to examine campaign advertising.
Contact
Please direct enquiries relating to requests through our contact page.
Financial statement audit (Auditor-General Report No. 22 of 2024–25)
Published: Thursday 6 February 2025
Published
This report complements the Interim Report on Key Financial Controls of Major Entities financial statement audit report published in June 2024. It provides a summary of the final results of the audits of the Consolidated Financial Statements for the Australian Government and the financial statements of Australian Government entities for the period ended 30 June 2024.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Financial statement audit (Auditor-General Report No. 24 of 2017–18)
Published: Wednesday 20 December 2017
Published
This report complements the Interim Report on Key Financial Controls of Major Entities financial statement audit report published in June 2017. It provides a summary of the final results of the audits of the Consolidated Financial Statements for the Australian Government and the financial statements of Australian Government entities for the period ended 30 June 2017.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Financial statement audit (Auditor-General Report No. 14 of 2021–22)
Published: Tuesday 14 December 2021
Published
This report complements the Interim Report on Key Financial Controls of Major Entities financial statement audit report published in June 2021. It provides a summary of the final results of the audits of the Consolidated Financial Statements for the Australian Government and the financial statements of Australian Government entities for the period ended 30 June 2021.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Financial statement audit (Auditor-General Report No. 20 of 2019–20)
Published: Tuesday 17 December 2019
Published
This report complements the Interim Report on Key Financial Controls of Major Entities financial statement audit report published in June 2019. It provides a summary of the final results of the audits of the Consolidated Financial Statements for the Australian Government and the financial statements of Australian Government entities for the period ended 30 June 2019.
Contact
Please direct enquiries through our contact page.
Financial statement audit (Auditor-General Report No. 8 of 2022–23)
Published: Wednesday 14 December 2022
Published
This report complements the Interim Report on Key Financial Controls of Major Entities financial statement audit report published in June 2022. It provides a summary of the final results of the audits of the Consolidated Financial Statements for the Australian Government and the financial statements of Australian Government entities for the period ended 30 June 2022.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Financial statement audit (Auditor-General Report No. 19 of 2018–19)
Published: Monday 17 December 2018
Published
This report complements the Interim Report on Key Financial Controls of Major Entities financial statement audit report published in June 2018. It provides a summary of the final results of the audits of the Consolidated Financial Statements for the Australian Government and the financial statements of Australian Government entities for the period ended 30 June 2018.
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 50 of 1999–2000)
Published: Thursday 29 June 2000
Published
The objective of this follow-up audit was to assess whether Defence had taken appropriate action on recommendations made in the ANAO's 1995 audit report on Management Audit Branch (MAB), which is responsible for internal audit in Defence, and to assess whether the internal audit function in Defence could be improved.
Entity
Department of Defence
Speeches and papers
Published: Monday 30 October 1995
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented to the Institute of Internal Auditors, Annual Directors' Forum, Canberra
Speeches and papers
Published: Saturday 26 June 2004
Published
Mr P.J. Barrett (AO) - Auditor-General for Australia, an Occasional Paper
Speeches and papers
Published: Wednesday 26 April 2000
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented an Occasional Paper
Speeches and papers
Published: Tuesday 17 September 2002
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented at the House of Representatives Occasional Seminar Series
Speeches and papers
Published: Friday 12 March 2004
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented to the Institute of Chartered Accountants of India
Speeches and papers
Published: Friday 16 November 2007
Published
Mr Ian McPhee - Auditor-General for Australia, presented at the CPA Congress
Speeches and papers
Published: Saturday 2 November 2002
Published
Presentation by Mr Alan Greenslade - Executive Director, to the Industry, Research and Develoment Board