Browse our range of reports and publications including performance and financial statement audit reports, assurance review reports, information reports and annual reports.
Corporate
Published: Thursday 6 July 2023
Published
The ANAO Corporate Plan 2023–24 outlines how we intend to deliver against our purpose over the next four years (2023–24 to 2026–27). The corporate plan is the ANAO’s primary planning document – it outlines our purpose; the dynamic environment in which we operate; our commitment to building capability; and the priorities, activities and performance measures by which we will be held to account. The corporate plan is complemented by the annual audit work program, which reflects the ANAO’s audit strategy for the coming year.
This corporate plan was updated on 26 March 2024:
- organisational structure changes — ‘Professional Services and Relationships Group’ to ‘Professional Services Group’
- Measure 3 — change type from ‘Efficiency / Qualitative’ to ‘Efficiency / Quantitative’
- Measure 15, reporting mechanism 4 — replaced text to reflect updated JCPAA feedback process
- Measure 16, reporting mechanism 3 — replaced references to ‘insights’ with ‘lessons’
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 23 of 1999–2000)
Published: Monday 20 December 1999
Published
The objectives of this audit were to improve: the accountability of the Australian Taxation Office to Parliament and the Government by the provision of advice that follows up on the ATO's implementation of the previous ANAO Report; and on the recommendations of the then Joint Committee of Public Accounts arising from its consideration of that Report and the efficiency, effectiveness and equity of debt collection by the ATO.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 20 of 1995–96)
Published: Thursday 2 May 1996
Published
The objective of the audit was to examine the efficiency and administrative effectiveness of the scheme in light of rapidly increasing expenditure and a history of administrative difficulties and deficiencies.
Entity
Australian Customs Service
Request for audit
Responded: Monday 1 April 2019
Response provided
The Auditor-General responded on 18 March 2019 to correspondence from the Hon. Shayne Neumann MP dated 19 February 2019 and 14 March 2019. The Auditor-General further responded on 1 April 2019. The correspondence from Mr Neumann requested that the Auditor-General conduct an audit into the circumstances surrounding the Department of Home Affairs' procurement of garrison support and welfare services in Papua New Guinea.
Contact
Please direct enquiries relating to requests for audit through our contact page.
Other report (Auditor-General Report No. 19 of 2017–18)
Published: Wednesday 6 December 2017
Published
Procurement is a significant public sector activity worth $47.4 billion in 2016–17. This information report seeks to provide greater transparency on procurement activity in the Australian public sector. This information report is neither an audit nor an assurance review and presents no conclusions or opinions. The report presents in a variety of ways, including tables and figures, publicly available data from public sector procurement activity.
Contact
Please direct enquiries through our contact page.
Corporate
Published: Thursday 20 November 2025
Published
Integrity is a core value of the Australian National Audit Office (ANAO) — critical in sustaining the confidence of Parliament, strengthening public trust in government and delivering quality audit products. Maintaining strong institutional integrity is essential to the operations and reputation of the ANAO.
The ANAO Integrity Framework provides an overarching structure to the integrity control system, supporting our institution’s integrity. The Framework serves to assist in ethical decision-making and risk, fraud and misconduct management.
Beyond its control system, the ANAO maintains an enduring focus on promoting integrity as a value that is embedded in our work and culture. The ANAO recognises that integrity demands quality not only in our products but also in the behaviours of our people.
The ANAO Integrity Advisor supports the effective and ongoing application of the Integrity Framework by providing advice to staff regarding integrity matters. The Integrity Advisor is responsible for increasing integrity awareness across the organisation and for reporting annually to the ANAO Executive Board of Management on actions taken under the Framework. The Auditor-General publishes the ANAO Integrity Report to provide increased transparency of the measures we undertake to maintain a high-integrity culture in the ANAO.
Contact
Please direct enquiries through our contact page.
Request for audit
Responded: Friday 20 March 2020
Response provided
The Auditor-General responded on 20 March 2020 to correspondence from Senator Larissa Waters dated 25 February 2020, requesting that the Auditor-General consider the process followed in approving the Adani Carmichael Coal Mine and Rail Project when conducting the audit Referrals, assessments and approvals of controlled actions under the Environment Protection and Biodiversity Conservation Act 1999.
Contact
Please direct enquiries relating to requests for audit through our contact page.
Potential topic
Potential topic: 2027-29
Potential
The ANAO could assess whether the Department of Veterans’ Affairs (DVA) has controls and processes to ensure payments to veterans and their dependants are accurate and timely. The audit could examine the integrity of payment calculations, and the adequacy of verification and quality assurance mechanisms by considering how DVA monitors error rates, addresses payment discrepancies, and manages risks that could impact the financial wellbeing of veterans and the proper use of public funds.
Entity
Department of Veterans' Affairs
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 3 of 2002–03)
Published: Wednesday 31 July 2002
Published
HMAS Cerberus is a Navy base situated south-east of Melbourne, Victoria. As a major Navy training establishment, it conducts initial recruit training, and specialist category training in areas such as communications and engineering. The Australian Defence Force (ADF) Schools of Catering and Physical Training are situated there, as is a major health centre for operational and training needs. The health centre and other facilities at HMAS Cerberus were re-developed several years ago. In August 2001, the then Minister for Defence announced that, in response to continuing concern over facilities management at HMAS Cerberus, he had asked the Australian National Audit Office (ANAO) to conduct an independent investigation. The ANAO agreed to review these matters. The objective of the audit was to examine facilities management issues at HMAS Cerberus with a view to clarifying those of concern and ensuring that lessons would be learned from them to assist Defence facilities management generally.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 58 of 2001–02)
Published: Monday 17 June 2002
Published
The audit sought to assess the efficiency of Defence property management; provide assurance that probity and compliance requirements are being met; and make practical recommendations for enhancing property operations. It focused on Infrastructure Division's property management, with recognition that other areas manage certain property service contracts, such as those for electricity supply and cleaning.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 30 of 1997–98)
Published: Thursday 18 December 1997
Published
The objectives of the audit were to:
- assist OGIT in the timely identification and correction of any deficiencies in the evaluation process;
- provide advice to the Parliament, the Government and other interested parties on the probity of the evaluation process; and
- test for adherence to legislative and other specified requirements, such as in industry development.
Entity
Office of Government Information Technology
Performance audit (Auditor-General Report No. 40 of 2000–01)
Published: Monday 28 May 2001
Published
The Department of Immigration and Multicultural Affairs (DIMA), administers the Commonwealth's settlement programs, which seek to assist migrants and refugees to participate in Australian society. Provision of English language training to newly arrived migrants and refugees has been a long standing and significant part of this settlement support, with some 1.5 million new arrivals assisted in this way since 1948. The objective of the audit was to examine DIMA's management of the Adult Migrant English Program Contracts, focusing on performance outcomes; strategic contract management and coordination; program expenditure, with emphasis on contract funding arrangements; and whether contract monitoring and performance information adequately support effective program management. The ANAO made six audit recommendations aimed at improving program performance management and reporting; strategic management and coordination; management of financial risks; and monitoring of contractor performance, which were all accepted by DIMA.
Entity
Department of Immigration and Multicultural Affairs
Performance audit (Auditor-General Report No. 45 of 1999–2000)
Published: Wednesday 31 May 2000
Published
The Commonwealth has significant foreign exchange risk exposures including $A8.4 billion of foreign currency transactions with the Reserve Bank of Australia in 1998-99. Under the Financial Management and Accountability Act and its associated Regulations, all agencies are required to assess and, where possible, manage, foreign exchange risk. The audit reviewed four agencies that have substantial foreign currency payment exposures namely:
- the Department of Defence;
- the Australian Agency for International Development;
- the Department of Foreign Affairs and Trade; and
- the Department of Finance and Administration.
The objective of the audit was to identify and assess the efficiency and cost effectiveness of the management of foreign exchange risk across the selected agencies, also to identify opportunities to improve the management of foreign exchange risk, including any associated potential financial savings that could accrue to the Commonwealth.
Entity
Department of Defence; Australian Agency for International Development; Department of Foreign Affairs and Trade; Department of Finance and Administration
Request for audit
Responded: Friday 24 July 2020
Response provided
The Auditor-General responded on 12 May 2020 to correspondence from Ms Zali Steggall OAM, MP dated 23 April 2020, requesting that the Auditor-General consider an audit of the Australian Government’s Underwriting New Generation Investment (UNGI) program. The Auditor-General provided a follow-up response to Ms Steggall OAM, MP on 24 July 2020.
Contact
Please direct enquiries relating to requests through our contact page.
Performance audit (Auditor-General Report No. 19 of 1998–99)
Published: Tuesday 8 December 1998
Published
The objective of the audit was to form an opinion on the administrative effectiveness and efficiency of DHAC's processes for planning the Commonwealth's Aged and Community Care program, in particular, on the questions of how well the planning process has contributed to realising the program objectives of achieving an equitable distribution of places between regions, and selecting suitable service providers.
Entity
Department of Health and Aged Care
Request for audit
Responded: Tuesday 8 September 2026
Response provided
The Auditor-General responded on 8 September 2026 to correspondence from seven parliamentarians, dated 12 August 2026, to undertake a performance audit of the Afghanistan Locally Engaged Employee (LEE) and High-Risk Women programs, covering the period from 2013 to 2025. The request was made jointly by Senator David Pocock, Dr Helen Haines MP, Senator Jacqui Lambie, Ms Nicolette Boele MP, Senator David Shoebridge, Senator Fatima Payman and Mr Andrew Wilkie MP.
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 9 of 1995–96)
Published: Tuesday 21 November 1995
Published
The purpose of the audit was to determine:
- whether the planning and implementation of the DSS Teleservice project has been adequate to ensure successful operations;
- the efficiency and administrative effectiveness of Teleservice Centre management practices;
- whether Teleservice Centres have been successful in delivering the anticipated improvements to client service; and
- what opportunities might be available for improvement in the operation of the Centres.
An important aim of the audit was to ascertain with DSS what value could be added by identifying more administratively effective and efficient means of managing and operating their Teleservice Centre network. In addition, the ANAO considered that the experience gained and lessons learned from the introduction of Teleservice operations by DSS could improve the planning and implementation of major technology-based operational and client service initiatives in the future, both in DSS and the Australian Public Service (APS) generally.
In carrying out the audit, the ANAO undertook an extensive examination of the Teleservice environment including:
- examining the experience and practices of private sector call centre operations;
- reviewing the DSS Teleservice network, involving detailed discussions with departmental officers, examining files and data and observing Teleservice Centre operations; as well as
- consulting a range of community groups and government agencies familiar with DSS's Teleservice Centre services.
Entity
Department of Social Security
Performance audit (Auditor-General Report No. 1 of 2016–17)
Published: Wednesday 31 August 2016
Published
The audit objective was to examine whether Airservices Australia has effective procurement arrangements in place, with a particular emphasis on whether consultancy contracts entered into with International Centre for Complex Project Management (ICCPM) in association with the OneSKY Australia project were effectively administered.
Entity
Airservices Australia
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 29 of 1995–96)
Published: Wednesday 19 June 1996
Published
The objectives of the audit were to examine and report on the economy, efficiency and administrative effectiveness of AEM's management and administration of the Commonwealth-owned commercial office estate. The ANAO addressed 22 recommendations to AEM, which will remain relevant in the context of the major administrative changes that the Commonwealth's property management function is currently undertaking.
Entity
Australian Estate Management
Potential topic
Potential topic: 2027-29
Potential
The ANAO could assess how the Fair Work Commission (FWC) is managing its responsibilities under the Fair Work Act 2009 and the Fair Work (Registered Organisations) Act 2009. The audit would examine the FWC’s governance, systems and processes for handling its overall workload and regulatory functions, including its approach to managing case volumes and its oversight of federally registered organisations.
Entity
Fair Work Commission
Contact
Please direct enquiries through our contact page.
Potential topic
Potential topic: 2027-29
Potential
The ANAO could assess the effectiveness of implementation of recommendations made by both the 2024 ANAO performance audit into Australian Office of Financial Management’s (AOFM) management of government debt and the 2026 independent review of the AOFM.
The AOFM is Australia’s sovereign debt manager. Its role is to finance the operations of the Australian Government through issue of debt securities and cash management. The AOFM also implements government initiatives which relate to the Australian securitisation market.
Entity
Department of the Treasury
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 15 of 2000–01)
Published: Thursday 9 November 2000
Published
The objectives of the audit were to examine:
- the effectiveness of agencies' implementation of the current GBEs governance framework;
- the extent to which agencies and GBEs comply with the Governance Arrangements and legislative requirements; and
- whether the GBE monitoring system provides an effective level of accountability to Ministers and to the Parliament.
Entity
Across Agency
Performance audit (Auditor-General Report No. 34 of 1999–2000)
Published: Thursday 16 March 2000
Published
In late 1996, the Government announced its commitment to establish new facilities for the National Museum of Australia and the Australian Institute of Aboriginal and Torres Strait Islander Studies on Acton Peninsula in Canberra. The objectives of the audit were to examine the project's compliance with the Commonwealth Procurement Guidelines for the procurement of public works and effectiveness of the project's management.
Entity
Department of Communications, Information Technology and the Arts
Performance audit (Auditor-General Report No. 38 of 2000–01)
Published: Thursday 24 May 2001
Published
The audit's main objectives were to:
- examine the guidance on the use of confidentiality clauses in contracts and agencies' use of such clauses;
- develop criteria to assist agencies in determining what information in a contract is confidential; and
- assess the effectiveness of the existing accountability and disclosure arrangements for Commonwealth contracts.
Entity
Across Agency
Performance audit (Auditor-General Report No. 49 of 1999–2000)
Published: Thursday 29 June 2000
Published
The objective of the audit was to form an opinion on the adequacy of the Indigenous Land Corporation's (ILC's) operations and performance in: assisting Aboriginal persons and Torres Strait Islanders to acquire land; and assisting Aboriginal persons and Torres Strait Islanders to manage indigenous-held land; so as to provide economic, environmental, social or cultural benefits for Aboriginal persons and Torres Strait Islanders.
Entity
Across Agency
Performance audit (Auditor-General Report No. 7 of 1997–98)
Published: Tuesday 21 October 1997
Published
The objective of this follow-up audit was to assess whether the department had taken appropriate action in response to the recommendations in Audit Report No.35 1993-94, titled The Compliance Function, Department of Immigration and Ethnic Affairs. The recommendations of the 1993-94 report, which formed the criteria for the audit, were primarily concerned with compliance after entry to Australia had been gained.
Entity
Department of Immigration and Multicultural Affairs
Annual report
Published: Wednesday 14 September 2016
Published
This annual report documents the performance of the Australian National Audit Office (ANAO) in the financial year ending 30 June 2016. It addresses all applicable obligations under the Public Governance, Performance and Accountability Act 2013 and the Auditor-General Act 1997, the performance measures set out in the outcome and programs framework in the ANAO’s 2015–16 Portfolio Budget Statements and the ANAO’s 2015–19 Corporate Plan and annual reporting requirements set out in other legislation.
Contact
Please direct enquiries relating to annual reports through our contact page.
Performance audit (Auditor-General Report No. 37 of 1996–97)
Published: Wednesday 18 June 1997
Published
The objective of the audit was to provide assurance about the Australian Taxation Office's risk management approach and to add value to its administration by analysing the economy, efficiency, administrative effectiveness, equity and accountability of the related processes employed within the organisation. The ANAO reviewed the formal risk management process that the ATO uses to deal with all sources of risk for the organisation.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 14 of 2015–16)
Published: Monday 14 December 2015
Published
The objective of the audit was to assess whether appropriate steps were taken to protect the Commonwealth’s interests and obtain value for money in respect to the:
- approval of $1.5 billion in Commonwealth funding for stage one of the East West Link project, and the June 2014 payment of $500 million of this funding; and
- approval of $1.5 billion in Commonwealth funding for stage two of the East West Link project, and the June 2014 payment of $1 billion of this funding.
Entity
Department of Infrastructure and Regional Development; Infrastructure Australia; Department of the Treasury; Department of the Prime Minister and Cabinet; and Department of Finance.
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 4 of 1998–99)
Published: Monday 10 August 1998
Published
The objective of the audit was to evaluate the efficiency and effectiveness of Austrade's management of customer services to Australian exporters, with particular reference to:
- performance as a customer-focused organisation;
- achievement of quality customer service through its client service initiatives; and
- measurement and evaluation of its customer service performance.
Entity
Australian Trade Commission
Corporate
Published: Thursday 28 March 2024
Published
The Australian National Audit Office Enterprise Agreement 2024–2027 was approved by the Fair Work Commission (FWC) on 22 March 2024 and operates from 29 March 2024. The agreement will nominally expire on 28 February 2027. The signatories page of this agreement is available on the FWC website.
Contact
Please direct enquiries through our contact page.
Request for audit
Responded: Tuesday 8 September 2026
Response provided
On 9 September 2026, the Auditor-General received follow-up correspondence from the Hon Dan Tehan MP. The correspondence will be considered in the ongoing development and implementation of the ANAO’s work program.
The Auditor-General responded on 8 September 2026 to follow-up correspondence from the Hon Dan Tehan MP dated 18 August 2026.
The Auditor-General responded on 19 June 2026 to correspondence from the Hon Dan Tehan MP dated 29 May 2026, requesting that the Auditor-General conduct an audit of the Cheaper Home Batteries Program.
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 18 of 1995–96)
Published: Wednesday 10 April 1996
Published
The ANAO conducted a project audit of Competitive Employment, Training and Placement services, part of the Disability Services Program administered by the then Department of Human Services and Health, primarily because of parliamentary concerns relating to these services. Under the Administrative Arrangements Order of 11 March 1996, the Disability Services Program is now administered by the Department of Health and Family Services.
Entity
Department of Health and Family Services
Performance audit (Auditor-General Report No. 25 of 2014–15)
Published: Thursday 5 March 2015
Published
The audit objective was to assess the effectiveness of the development and administration of the Fifth Community Pharmacy Agreement (5CPA), and the extent to which the 5CPA has met its objectives.
Entity
Department of Health; Department of Human Services; Department of Veterans' Affairs
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 47 of 2000–01)
Published: Thursday 7 June 2001
Published
Quarantine policies and operations are the responsibility of the Department of Agriculture, Fisheries and Forestry - Australia (AFFA). The objective of this audit was to assess AFFA's management of plant and animal quarantine services, and the implementation and impact of the Government Response (1997) to the Quarantine Review Committee Report. The audit in particular assessed the setting of quarantine priorities through assessing and managing risk; management of the continuum of quarantine operations; and management of Import Risk Analyses to deliver and review quarantine policies. Stakeholder consultation and advisory processes were also assessed in addressing these issues. A key issue examined was the effectiveness of AFFA quarantine operations in international mail and airports preventing the entry of quarantinable material. The ANAO made eight recommendations aimed at improving operational risk based resource allocation; pre-border management of quarantine risk; the effectiveness of quarantine operations at the Australian border; and priority setting and transparency of the IRA process. AFFA agreed to all eight ANAO recommendations.
Entity
Agriculture Fisheries and Forestry - Australia Department of Agriculture
Performance audit (Auditor-General Report No. 43 of 2001–02)
Published: Tuesday 23 April 2002
Published
To improve educational outcomes for Indigenous Australians, two main forms of assistance administered by the Commonwealth, namely the Indigenous Education Strategic Initiatives Programme (IESIP) and the Indigenous Education Direct Assistance programmes (IEDA), are currently available. The objective of the audit was to assess whether the department had efficiently and effectively managed the development and implementation of the IESIP agreements for the 2001 to 2004 quadrennium.
Entity
Department of Education Science and Training
Performance audit (Auditor-General Report No. 13 of 2000–01)
Published: Wednesday 4 October 2000
Published
The audit examined a range of issues in relation to the development of certified agreements in the APS with particular emphasis on the link between improved pay and conditions and increased productivity, and the funding of agreements. The objectives of the audit were to:
- provide an overview of the range of wage outcomes included in the first round of APS certified agreements;
- identify the administrative arrangements agencies have in place to measure any improvements in productivity that were linked to pay increases;
- determine how agencies funded their certified agreements;
- review the reporting and accountability arrangements agencies have in place to monitor progress and to evaluate the outcomes of their certified agreements;
- determine the extent to which agencies complied with the employment terms and conditions outlined in their certified agreements that contributed to paying for their agreement or measuring and/or assessing improvements in productivity; and
- examine the role of central coordinating agencies in reviewing agencies' certified agreements.
Entity
Across Agency
Performance audit (Auditor-General Report No. 7 of 1996–97)
Published: Tuesday 17 September 1996
Published
The objective of the audit was to determine whether:
- councils essentially met their objectives as stated in the IT Acquisition Council Guidelines;
- council members substantially fulfilled their roles and responsibilities, including providing advice regarding relevant government policy; and
- councils add value and assurance in meeting accountability requirements to the acquisition process.
Entity
Across Agency
Annual report
Published: Thursday 29 August 2024
Published
This annual report documents the performance of the Australian National Audit Office (ANAO) in the financial year ended 30 June 2024. The report addresses all applicable obligations under the Public Governance, Performance and Accountability Act 2013; the Public Governance, Performance and Accountability Rule 2014; the Auditor-General Act 1997; the performance measures set out in the outcome and programs framework in the ANAO’s Portfolio Budget Statements 2023–24 and in the ANAO Corporate Plan 2023–24; and annual reporting requirements set out in other relevant legislation.
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 60 of 2002–03)
Published: Friday 27 June 2003
Published
Closing the books processes sometimes referred to as 'month-end or year-end processing' are those processes undertaken by organisations in order to generate periodic financial information. This audit focused on the monthly closing the books processes undertaken at six of the material Commonwealth organisations, in order to provide some generic conclusions on the operation and effectiveness of these periodic processes in the Commonwealth and to identify opportunities for improvement.
Entity
Across Agency
Performance audit (Auditor-General Report No. 22 of 2001–02)
Published: Tuesday 4 December 2001
Published
Personnel security, including the security clearance process, is a valuable and essential element of managing the risk inherent in allowing Commonwealth and other personnel access to sensitive information. This audit was designed to review security clearance and vetting policies and practices in a number of Commonwealth organisations and to consider if organisations were managing these processes effectively and efficiently and in accordance with Commonwealth policy, as outlined in the Protective Security Manual.
Entity
Across Agency
Performance audit (Auditor-General Report No. 47 of 2001–02)
Published: Tuesday 7 May 2002
Published
The 30 per cent Private Health Insurance Rebate is a financial incentive for individuals to purchase health insurance cover. The rebate provides for a reimbursement or discount of 30 per cent of the cost of private health insurance. It is available to all Australians who are eligible for Medicare and have private health insurance. The objective of the audit was to determine the effectiveness of Commonwealth Government agencies administration of the rebate.
Entity
Australian Taxation Office; Department of Finance and Administration; Department of Health and Aged Care; Department of the Treasury; Health Insurance Commission
Performance audit (Auditor-General Report No. 11 of 1999–2000)
Published: Tuesday 21 September 1999
Published
In November 1998, the Minister for Communications wrote to the Auditor-General requesting an assessment of the actual costs of Phase 1 digital conversion for the ABC and SBS, the sources of funds applied and the efficiency with which the funds had been used before the government considered further funding. The purpose of this limited scope performance audit was to assess a range of financial issues associated with the ABC and SBS conversion to digital broadcasting.
Entity
Australian Broadcasting Corporation; Special Broadcasting Service Corporation
Performance audit (Auditor-General Report No. 34 of 2016–17)
Published: Tuesday 24 January 2017
Published
The objective of this audit was to assess the effectiveness of the Department of Agriculture and Water Resources' implementation of the new biosecurity legislative framework.
Entity
Department of Agriculture and Water Resources
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 41 of 1999–2000)
Published: Friday 28 April 2000
Published
The Commonwealth has significant involvement in national emergency management arrangements through its roles in planning, coordination between agencies, operational response, financial support, education and training, public awareness and research activities. The objectives of this performance audit were to identify the Commonwealth's current emergency management arrangements; to provide assurance to Parliament concerning the adequacy of the arrangements; and to highlight areas for improvement.
Entity
Across Agency
Performance audit (Auditor-General Report No. 50 of 2001–02)
Published: Thursday 16 May 2002
Published
The Shadow Minister for Health and Ageing, Mr Stephen Smith, wrote to the Auditor-General on 11 March 2002 formally requesting an investigation into certain matters in relation to the 'Co-Location of National General Practice Organisations', a message detailed in the Health Portfolio Additional Estimates Statements 2001-02. The Federal President of the Australian Medical Association (AMA) Limited wrote to the Auditor-General on 11 March 2002, requesting a comprehensive audit of funding decisions by the Minister for Health and Ageing. The Australian National Audit Office has undertaken a preliminary examination of relevant papers relating to the 'GP House' matter. The preliminary examination focussed on whether or not due process was followed in making the decision to transfer funds between Outcomes. The preliminary examination also considered the procedures adopted by the Department of Health and Aged Care in developing the funding proposal, the advisory role played by the Department of Finance and Administration and specific advice provided by both departments to their Ministers. The examination further considered the disclosure of the related budget measure.
Entity
Department of Finance and Administration; Department of Health and Aged Care
Performance audit (Auditor-General Report No. 16 of 2002–03)
Published: Monday 4 November 2002
Published
A Business Support Process audit of the administration of grants in small to medium organisations was undertaken across six Commonwealth organisations to assess whether agencies had implemented appropriate risk management strategies for grant programs; evaluate whether grants had been administered in accordance with the appropriate legislation, Commonwealth guidance, and other accepted internal controls; and to recommend improvements in the controls and practices relating to grants administration.
Entity
Across Agency
Performance audit (Auditor-General Report No. 6 of 1997–98)
Published: Monday 20 October 1997
Published
The objective of the audit was to review the efficiency and administrative effectiveness of the Commercial Compliance Branch's risk management processes and to establish whether the approach provided a sound foundation for the development and application of risk management across the Australian Customs Service. The ANAO also examined the wider risk management context across ACS in order to appreciate how risk management processes in the Branch related to the agency as a whole.
Entity
Australian Customs Service
Annual report
Published: Thursday 26 August 2021
Published
This annual report documents the performance of the Australian National Audit Office (ANAO) in the financial year ended 30 June 2021. The report addresses all applicable obligations under the Public Governance, Performance and Accountability Act 2013; the Public Governance, Performance and Accountability Rule 2014; the Auditor-General Act 1997; the performance measures set out in the outcome and programs framework in the ANAO’s Portfolio Budget Statements 2020–21 and the ANAO Corporate Plan 2020–21; and annual reporting requirements set out in other relevant legislation.
Contact
Please direct enquiries relating to annual reports through our contact page.
Annual report
Published: Monday 28 September 2020
Published
This annual report documents the performance of the Australian National Audit Office (ANAO) in the financial year ended 30 June 2020. The report addresses all applicable obligations under the Public Governance, Performance and Accountability Act 2013; the Public Governance, Performance and Accountability Rule 2014; the Auditor-General Act 1997; the performance measures set out in the outcome and programs framework in the ANAO's Portfolio Budget Statements 2019–20 and the ANAO Corporate Plan 2019–20; and annual reporting requirements set out in other relevant legislation.
Contact
Please direct enquiries relating to annual reports through our contact page.
Annual report
Published: Tuesday 23 September 2025
Published
This annual report documents the performance of the Australian National Audit Office (ANAO) in the financial year ended 30 June 2025. The report addresses all applicable obligations under the Public Governance, Performance and Accountability Act 2013; the Public Governance, Performance and Accountability Rule 2014; the Auditor-General Act 1997; the performance measures set out in the outcome and programs framework in the ANAO’s Portfolio Budget Statements 2024–25 and in the ANAO Corporate Plan 2024–25; and annual reporting requirements set out in other relevant legislation.
Contact
Please direct enquiries through our contact page.
Annual report
Recent
Published: Tuesday 22 September 2026
Published
This annual report documents the performance of the Australian National Audit Office (ANAO) in the financial year ended 30 June 2026. The report addresses all applicable obligations under the Public Governance, Performance and Accountability Act 2013; the Public Governance, Performance and Accountability Rule 2014; the Auditor-General Act 1997; the performance measures set out in the outcome and programs framework in the ANAO’s Portfolio Budget Statements 2025–26 and in the ANAO Corporate Plan 2025–26; and annual reporting requirements set out in other relevant legislation.
Contact
Please direct enquiries through our contact page.
Annual report
Published: Thursday 25 August 2022
Published
This annual report documents the performance of the Australian National Audit Office (ANAO) in the financial year ended 30 June 2022. The report addresses all applicable obligations under the Public Governance, Performance and Accountability Act 2013; the Public Governance, Performance and Accountability Rule 2014; the Auditor-General Act 1997; the performance measures set out in the outcome and programs framework in the ANAO’s Portfolio Budget Statements 2021–22 and the ANAO Corporate Plan 2021–22; and annual reporting requirements set out in other relevant legislation.
Contact
Please direct enquiries through our contact page.
Potential topic
Potential topic: 2027-29
Potential
The ANAO could assess whether the Department of Veterans’ Affairs (DVA) has effective procurement and contract management practices that comply with the Commonwealth Procurement Rules and achieve value for money. The audit could examine the planning, competitive processes, and probity controls in procurement activities, as well as the robustness of contract management arrangements to monitor performance, manage risks, and ensure deliverables meet agreed standards. It could also consider how DVA maintains transparency, supports accountability, and mitigates risks of fraud or non-compliance in the use of public funds.
Entity
Department of Veterans' Affairs
Contact
Please direct enquiries through our contact page.
Other report (Auditor-General Report No. 27 of 2019–20)
Published: Wednesday 11 March 2020
Published
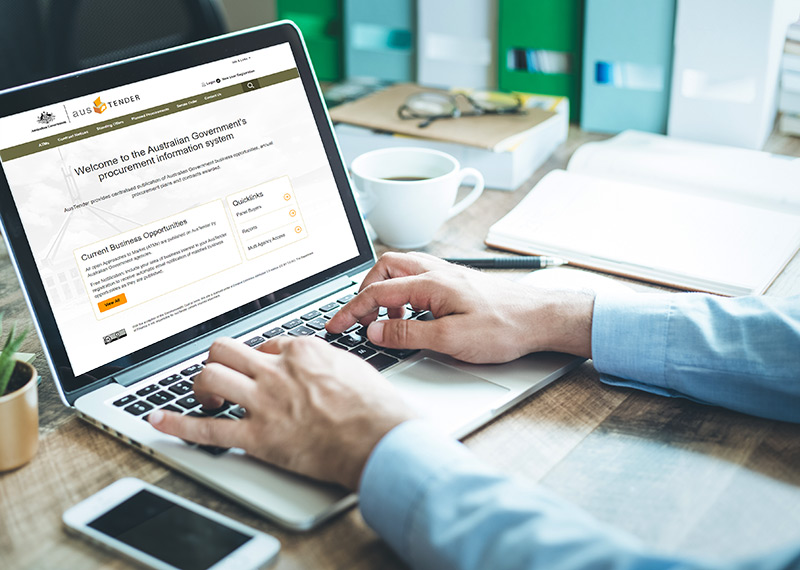
This information report seeks to provide greater transparency on procurement activity in the Australian public sector. This information report is neither an audit nor an assurance review and presents no conclusions or opinions. The report is presented in a variety of ways, including tables and figures, publicly available data from public sector procurement activity recorded in AusTender.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 54 of 2002–03)
Published: Monday 23 June 2003
Published
The audit examined the management of computer software assets at four Commonwealth bodies. It focused on the capitalisation of software for the purposes of annual financial reporting. The specific objectives were to: determine whether the selected bodies had established effective internal control frameworks for the capitalisation of externally acquired and internally developed software; and assess whether software costs were capitalised in accordance with organisational policy, accounting standards and relevant legislation.
Entity
Across Agency
Major projects report (Auditor-General Report No. 12 of 2022–23)
Published: Thursday 9 February 2023
Published
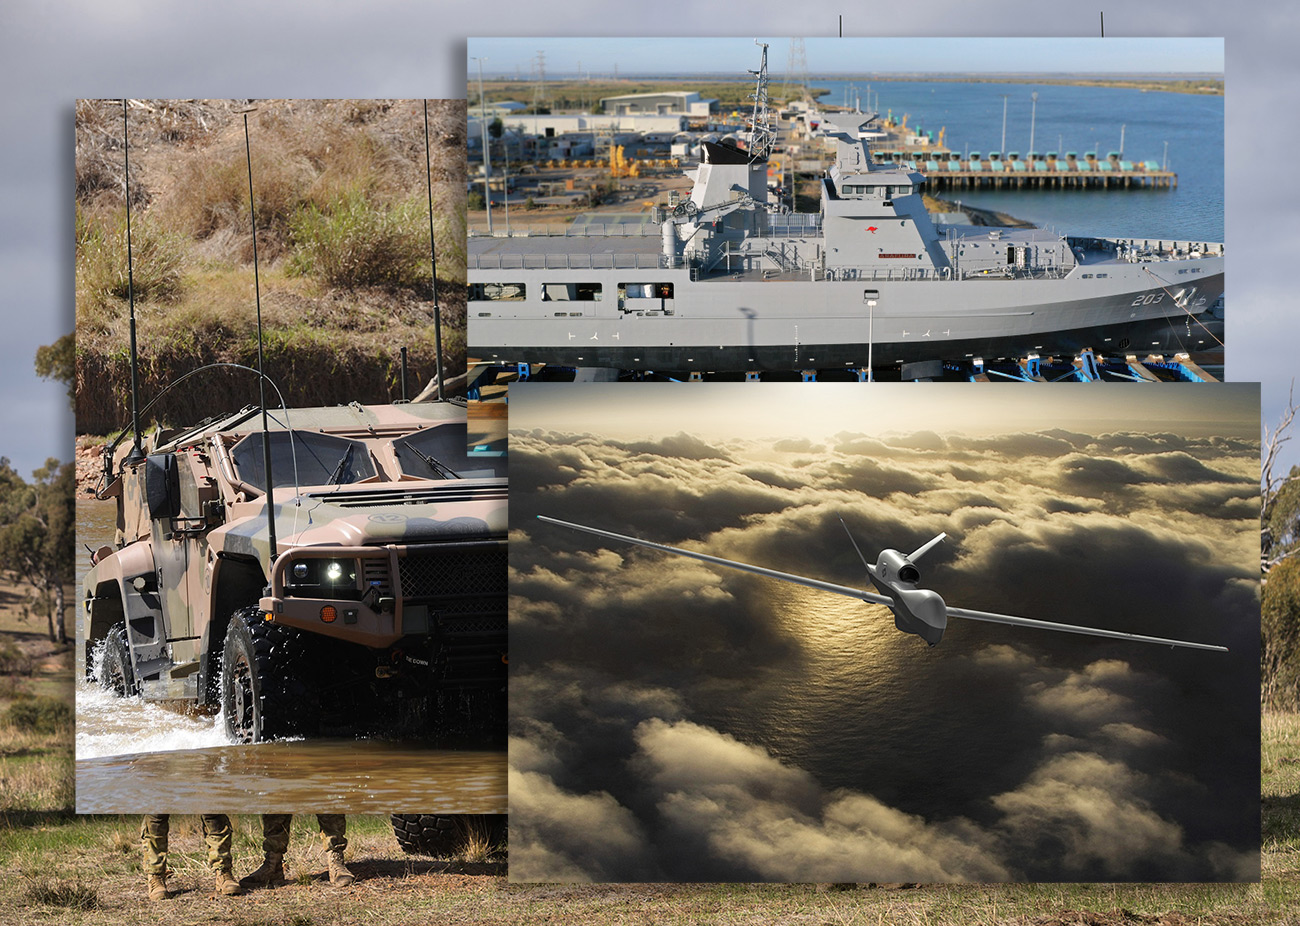
Increased transparency and accountability on progress with major Defence equipment acquisitions has been a focus of parliamentary interest for some time. Beginning in 2007–08, an annual program has been established in conjunction with the Department of Defence to enable the ANAO to review and report to the Parliament on the status of major Defence acquisition projects, as set out in the Major Projects Report. The review includes information relating to the cost, schedule and progress towards delivery of required capability of individual projects as at 30 June each year, and is undertaken at the request of the Joint Committee of Public Accounts and Audit.
Entity
Department of Defence
Contact
Please direct enquiries through our contact page.
Major projects report (Auditor-General Report No. 20 of 2024–25)
Published: Wednesday 18 December 2024
Published
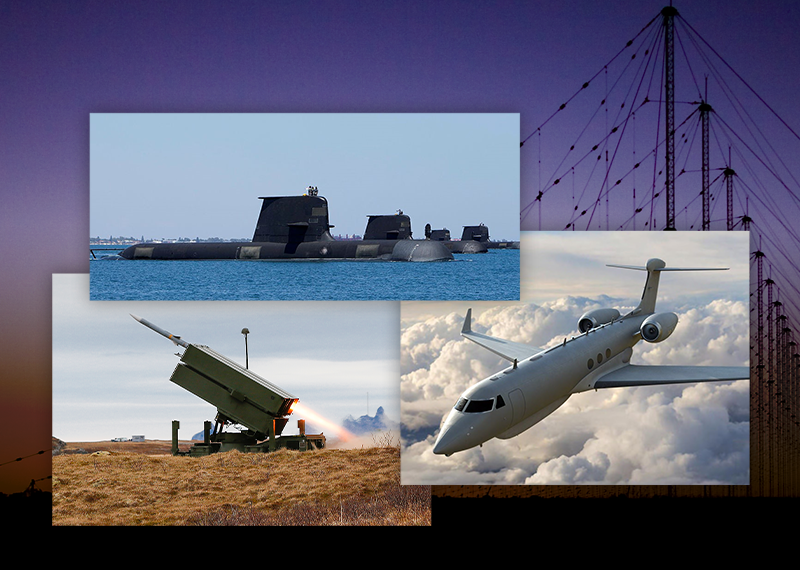
Increased transparency and accountability on progress with major Defence equipment acquisitions has been a focus of parliamentary interest for some time. Beginning in 2007–08, an annual program has been established in conjunction with the Department of Defence to enable the ANAO to review and report to the Parliament on the status of major Defence acquisition projects, as set out in the major projects report. The review includes information relating to the cost, schedule and progress towards delivery of required capability of individual projects as at 30 June each year, and is undertaken at the request of the Joint Committee of Public Accounts and Audit.
Entity
Department of Defence
Contact
Please direct enquiries through our contact page.
Annual report
Published: Wednesday 14 August 2019
Published
This annual report documents the performance of the Australian National Audit Office (ANAO) in the financial year ended on 30 June 2019. The report addresses all applicable obligations under the Public Governance, Performance and Accountability Act 2013; the Public Governance, Performance and Accountability Rule 2014; the Auditor-General Act 1997; the performance measures set out in the outcome and programs framework in the ANAO’s Portfolio Budget Statements 2018–19 and the ANAO Corporate Plan 2018–19, and annual reporting requirements set out in other relevant legislation.
Contact
Please direct enquiries relating to annual reports through our contact page.
Annual report
Published: Monday 4 September 2017
Published
This annual report documents the performance of the Australian National Audit Office (ANAO) in the financial year ending on 30 June 2017. The report addresses all applicable obligations under the Public Governance, Performance and Accountability Act 2013 (PGPA Act); the Public Governance, Performance and Accountability Rule 2014 (PGPA Rule); the Auditor-General Act 1997; the performance measures set out in the outcome and programs framework in the ANAO’s 2016–17 Portfolio Budget Statements (PBS) and the ANAO 2016–20 Corporate Plan and annual reporting requirements set out in other relevant legislation.
Contact
Please direct enquiries relating to annual reports through our contact page.