Browse our range of reports and publications including performance and financial statement audit reports, assurance review reports, information reports and annual reports.
Financial statement audit (Auditor-General Report No. 39 of 2024–25)
Published: Thursday 29 May 2025
Published
The ANAO prepares two reports annually that provide insights at a point in time to the financial statements risks, governance arrangements and internal control frameworks of Commonwealth entities, drawing on information collected during our audits.
This report is the first of the two reports and focuses on the results of the interim financial statements audits, including an assessment of entities’ key internal controls, supporting the 2024–25 financial statements audits. This report examines 27 of the largest Australian Government entities, including all: departments of state; the Department of Parliamentary Services; and other Commonwealth entities that significantly contribute to the revenues, expenses, assets and liabilities within the 2023–24 Australian Government Consolidated Financial Statements (CFS). The National Indigenous Australians Agency is also included in this report given the role it plays working across government with indigenous communities and stakeholders.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Performance audit in-progress
Due to table: March 2027
Report preparation
The objective of this audit is to assess the effectiveness of the Fraud Fusion Taskforce to improve collaboration and reduce fraud against Australian Government programs.
Entity
See page for details
Contact
Please direct enquiries through our contact page.
Insights: Audit lessons
Published: Wednesday 30 June 2021
Published
This edition of Audit Insights considers the approaches entities are taking to implement parliamentary and ANAO recommendations to improve public administration practices and outcomes. It updates and replaces the edition published in November 2019 and draws on audit reports released since then.
Parliamentary committee inquiries and ANAO performance audits identify risks to the successful delivery of outcomes and generally provide recommendations to address them. Tabling an agreed response to a parliamentary committee recommendation formalises government or entity commitment to the Parliament to implement the agreed action. Similarly, ANAO performance audit reports are prepared for presentation to Parliament and agreement to implement a recommendation made in an ANAO report is therefore a commitment to the Parliament.
Contact
Please direct enquiries through our contact page.
Financial statement audit (Auditor-General Report No. 42 of 2025–26)
Published: Thursday 25 June 2026
Published
The ANAO prepares two reports annually that provide insights at a point in time to the financial statements risks, governance arrangements and internal control frameworks of Commonwealth entities, drawing on information collected during our audits.
This report is the first of the two reports and focuses on the results of the interim financial statements audits, including an assessment of entities’ key internal controls, supporting the 2025–26 financial statements audits. This report examines 27 of the largest Australian Government entities, including all: departments of state; the Department of Parliamentary Services; and other Commonwealth entities that significantly contribute to the revenues, expenses, assets and liabilities within the 2024–25 Australian Government Consolidated Financial Statements (CFS). The National Indigenous Australians Agency is also included in this report given the role it plays working across government with indigenous communities and stakeholders.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Insights: Audit lessons
Published: Friday 20 July 2018
Published
This edition of audit insights covers audit reports tabled in Parliament during the fourth quarter of 2017–18 with a focus on the key learnings relating to cyber resilience. Cyber security is an increasing risk across government and one that requires attention by Accountable Authorities.
Contact
Please direct enquiries through our contact page.
About
Updated: Thursday 9 July 2026
Updated
Information on legislation that governs the work of the Auditor-General and the Australian National Audit Office (ANAO).
Contact
Please direct enquiries through our contact page.
Financial statement audit (Auditor-General Report No. 32 of 2021–22)
Published: Thursday 9 June 2022
Published
This report is the first of the two reports and focuses on the results of the interim audits, including an assessment of entities’ key internal controls, supporting the 2021–22 financial statements audits. This report examines 25 entities, including all departments of state and a number of major Australian government entities. The majority of entities included in the report are selected on the basis of their contribution to the income, expenses, assets and liabilities of the 2020–21 Consolidated Financial Statements.
Contact
Please direct enquiries through our contact page.
Performance audit in-progress
Due to table: December 2026
Report preparation
The objective of this audit is to assess the effectiveness of public reporting on domestic, family and sexual violence expenditure under the National Plan to End Violence against Women and Children 2022–2032.
Entity
Department of Social Services
Contact
Please direct enquiries through our contact page.
About
Updated: Friday 23 May 2025
Updated
The ANAO’s governance structure and practices support the Auditor-General in the oversight of the organisation, management of its resources and the delivery of quality audit products. The corporate governance framework, processes and related organisational capability supports the delivery of the ANAO’s purpose, and meets public and community expectations of probity, accountability and transparency.
Contact
Please direct enquiries through our contact page.
Insights: Audit lessons
Published: Monday 19 November 2018
Published
This edition of audit insights focuses on efficiency in the public sector. Find out more about what we think efficiency looks like, why we think efficiency is important in ensuring that public sector agencies remain sustainable, and some examples from recently tabled audits of what we can learn from others.
Contact
Please direct enquiries through our contact page.
Corporate
Published: Friday 4 May 2018
Published
This first e-newsletter of the Commonwealth Auditors General Group was produced by Sir Amyas Morse, UK Comptroller and Auditor General as guest editor, along with the editorial team of the Auditors General of Australia, Fiji, Jamaica and Tanzania. Cybersecurity is the theme for this newsletter, with articles from the Supreme Audit Institutions (SAIs) of Australia, Malta and the UK.
One of the main purposes of the e-newsletter is to share experiences and establish a dialogue based on the discussions that were started at the 23rd Conference of Commonwealth Auditors General in Delhi. For this edition the conversation is around ‘leveraging technology in public audit’, and it draws on international peers experiences and learnings from conducting cybersecurity audits.
Contact
If you have any thoughts on future technical content which you would like to propose, please contact international@nao.gsi.gov.uk
About
Updated: Wednesday 17 January 2024
Updated
Information about ANAO events and seminars including the financial and performance reporting forum and the audit committee chairs forum.
Contact
Please direct enquiries through our contact page.
Insights: Audit lessons
Published: Tuesday 9 January 2024
Published
The aim of Insights: Audit Lessons is to communicate lessons from our audit work and to make it easier for people working within the Australian public sector to apply those lessons.
This edition of Insights: Audit Lessons is targeted at risk practitioners and officials responsible for government operations, projects, programs, services and regulatory activities. It would also be useful for accountable authorities, their senior executives and audit and risk committees.
Contact
Please direct enquiries through our contact page.
Corporate
Published: Thursday 24 October 2019
Published
This is the second e-newsletter of the Commonwealth Auditors General Group. These e-newsletters are a genuine effort to share experiences, challenges and engage in thought-provoking discussions on topics which are common to the fifty-three member countries of the Commonwealth.
Contact
If you have any thoughts on future technical content which you would like to propose, please contact international@nao.gsi.gov.uk
Insights: Audit lessons
Published: Wednesday 11 November 2020
Published
This edition of Audit Insights summarises key messages from a series of ANAO performance audits assessing performance evaluation frameworks and success measures. It discusses the importance of both in keeping entities accountable and their performance transparent.
Contact
Please direct enquiries through our contact page.
Insights: Audit lessons
Published: Monday 3 April 2023
Published
This edition of Audit Insights is targeted at Australian Government officials who have responsibility for overseeing or conducting procurements, including those who only do procurement occasionally. The aim is to communicate lessons from our audit work to make it easier for people working within the Australian public sector to apply those lessons. It is drawn from audit reports tabled in 2020–21, 2021–22 and 2022–23 into Australian Government procurements.
Contact
Please direct enquiries through our contact page.
Insights: Audit lessons
Published: Thursday 29 June 2023
Published
This edition of Audit Insights is targeted at Australian Government officials who have responsibility for overseeing or preparing performance information under the Commonwealth Performance Framework. The aim of Audit Insights is to communicate lessons from our audit work and to make it easier for people working within the Australian public sector to apply those lessons. This edition is drawn from audit reports tabled from 2015–16 to 2022–23 into the implementation of the corporate planning and annual performance statements requirements.
Contact
Please direct enquiries through our contact page.
Insights: Audit lessons
Published: Tuesday 25 January 2022
Published
This edition of Audit Insights summarises key messages for all Australian government entities from a series of Australian National Audit Office (ANAO) performance audits that have examined service delivery through other entities. It discusses the importance of establishing appropriate service delivery governance arrangements between entities, understanding risk tolerances and managing service delivery risks, and establishing performance monitoring and measurement arrangements.
Contact
Please direct enquiries through our contact page.
Insights: Audit practice
Published: Tuesday 30 June 2026
Published
Audit Practice: Information-gathering, confidentiality and reporting is intended for officials within government entities responsible for activity that may be the subject of an ANAO audit. It outlines the operation of legislative provisions relating to information-gathering, access and confidentiality. It also explains the ANAO’s reporting processes.
Contact
Please direct enquiries through our contact page.
Insights: Audit lessons
Published: Friday 28 May 2021
Published
This edition of Audit Insights summarises key messages for all Australian Government entities from a series of recent Australian National Audit Office (ANAO) performance audits assessing the delivery of key components of the Australian Government’s response to the COVID-19 pandemic. It discusses the importance of planning, good governance and sound risk management in managing an emergency such as the COVID-19 pandemic.
Contact
Please direct enquiries through our contact page.
Parliamentary briefing (46th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit (JCPAA)
Topic
Auditor-General Report No. 19 of 2019–20 2018–19 Major Projects Report
Auditor-General Report No. 22 of 2019–20 Future Submarine Program — Transition to Design
Parliamentary briefing (46th Parliament)
Briefing date
Recipient
Joint Committee of Public Accounts and Audit (JCPAA)
Topic
ANAO 2020-21 budget submission
Performance audit (Auditor-General Report No. 43 of 2016–17)
Published: Wednesday 22 March 2017
Published
The objective of this audit was to examine the effectiveness of the Australian Federal Police’s, the Australian Financial Security Authority’s and the Attorney-General’s Department’s administration of property and funds under the Proceeds of Crime Act 2002.
Entity
Australian Financial Security Authority; Australian Federal Police; Attorney-General’s Department
Contact
Please direct enquiries relating to reports through our contact page.
Insights: Audit opinion
Published: Wednesday 29 November 2023
Published
The purpose of Insights: Audit Opinion is to provide the Auditor-General's views on key issues facing the Australian public sector. This inaugural edition is on the topic of the Commonwealth Performance Framework and how it can be better used to drive effectiveness in the Australian public sector. This includes the need to prioritise the improvement of performance frameworks, embed a performance culture and use performance information to drive business improvement.
Contact
Please direct enquiries through our contact page.
- Roles, responsibilities, and governance arrangements should be defined and implemented at the commencement of the cultural change program. It is worth reviewing them at points in the long-term change program to assess if they remain appropriate as change unfolds, including where new risks emerge. Changes in senior positions within organisations during long-term change programs reinforce the need for good records to ensure continuity of intent.
Corporate
Published: Thursday 14 July 2022
Published
The ANAO Workforce Plan 2022-25 outlines how we will attract, develop and retain the capability of our workforce, to ensure we are suitably skilled to deliver on our purpose to the Parliament – now and into the future. This is a summary of the full plan.
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 18 of 2005–06)
Published: Wednesday 30 November 2005
Published
The objective of the audit was to assess the administrative effectiveness of the CCAS. The audit focused on the following key areas: targeting non-compliance; real time compliance activity; post transaction compliance activity; and planning and performance evaluation. As the imports phase of the Integrated Cargo System (ICS) was only introduced in October 2005, this system was not reviewed as part of the audit. Our audit programme for 2005–06 includes ICS as a potential audit topic.
Entity
Australian Customs Service
Performance audit (Auditor-General Report No. 30 of 2009–10)
Published: Thursday 22 April 2010
Published
Recent performance audit priority for the Australian National Audit Office (ANAO) in the Infrastructure, Transport, Regional Development and Local Government portfolio has been directed at the administration of funding for land transport. Accordingly, this audit is one of a series ANAO is undertaking of land transport funding programs. Four audits have already been completed, namely:
- ANAO Audit Report No. 31 2005–06, Roads to Recovery;
- ANAO Audit Report No. 45 2006–07, The National Black Spot Program;
- ANAO Audit Report No. 22 2007–08, Administration of Grants to the Australian Rail Track Corporation; and
- ANAO Audit Report No. 29 2008–09, Delivery of Projects on the AusLink National Network.
Entity
Department of Infrastructure, Transport, Regional Development and Local Government
Corporate
Updated: Wednesday 2 May 2018
Updated
The ANAO may collect personal information in the course of undertaking its audit program and for operational purposes not related to its audit work. This policy outlines our personal information handling practices, how we handle specific types of personal information and the information collected online by the ANAO.
Contact
Please direct enquiries about our Privacy Policy through our contact page.
Performance audit (Auditor-General Report No. 19 of 2005–06)
Published: Thursday 1 December 2005
Published
The objective of this audit was to assess the effectiveness of the actions taken by AQIS and BA to strengthen the administration of quarantine. The audit focussed on progress in implementing the recommendations from the previous ANAO audit, and recommendations made in the JCPAA's inquiry. (The audit did not address four JCPAA recommendations that were either not supported by the Government, or were policy matters for the Government to consider. See Appendix 1.)
Entity
Department of Agriculture Fisheries and Forestry; Biosecurity Australia
Performance audit (Auditor-General Report No. 4 of 2009–10)
Published: Tuesday 15 September 2009
Published
The objective of this audit was to determine whether selected Australian Government organisations had effective processes for managing the annual leave entitlements of their staff, and whether systems and controls over the processing of annual leave were working as intended. In addressing this objective, the audit also assessed progress being made by the audited organisations in implementing the recommendations in ANAO Audit Report No.16 2005-06.
Entity
Australian Bureau of Statistics; Australian Taxation Office; Department of Broadband, Communications and the Digital Economy
Performance audit (Auditor-General Report No. 15 of 2005–06)
Published: Tuesday 15 November 2005
Published
The objective of the audit was to assess the Commonwealth's administration of the grants component of the R&D Start program. Lessons for the new Commercial Ready program have been identified in the audit. Accordingly, recommendations arising from this audit are directed, when appropriate, to the Commercial Ready program. As most financial assistance is in the form of grants, the loans component of the program was excluded from the audit.
Entity
Department of Industry Tourism and Resources; Industry Research and Development Board
Performance audit (Auditor-General Report No. 23 of 2005–06)
Published: Thursday 22 December 2005
Published
This audit is a part of the ANAO's protective security audit coverage. The objective of this audit was to determine whether agencies audited had developed and implemented sound IT security management principles and practices supported by an IT security control framework, in accordance with Australian Government policies and guidelines. The audit at each agency examined the framework for the effective management and control of IT security, including the management of IT operational security controls and, where applicable, was based on the Australian Government protective security and information and communications technology (ICT) security guidelines that were current at that time.
Entity
Across Agency
Performance audit (Auditor-General Report No. 1 of 2005–06)
Published: Thursday 7 July 2005
Published
A performance audit of the management of the Detention Centre Contracts was listed in the 2003-04 Audit Work Program as a potential audit. The audit work program proposed that the audit would be conducted in two parts. The first part would focus on DIMIA's management of the detention centre contracts with the then detention service provider, GEO Australia. The second part would concentrate on how well any lessons learned from the first contract, were translated into improvements with the new contract. The original objective of this second ANAO audit was to assess DIMIA's management of detention services through the Contract, including the tender process, transition period and implementation of lessons learned from the previous contract.
Entity
Department of Immigration and Multicultural and Indigenous Affairs
Performance audit (Auditor-General Report No. 13 of 2003–04)
Published: Friday 7 November 2003
Published
The objective of the audit was to form an opinion on ATSIS' management of the Law and Justice Program, having particular regard to the relative needs of Aboriginal and Torres Strait Islander peoples. The audit focused primarily on how effectively ATSIS manages and delivers the provision of legal services to Aboriginal and Torres Strait Islander people. The audit was desgined to compelement but not to reproduce previous audit and other evaluation activity relevant to the Program.
Entity
Aboriginal and Torres Strait Islander Services
Performance audit (Auditor-General Report No. 35 of 2006–07)
Published: Wednesday 2 May 2007
Published
The audit objective was to assess whether the early stages of DIAC's preparations for the re-tendering of the detention and health services contracts were consistent with sound practice. The audit focused on governance arrangements, in particular the recordkeeping arrangements, roles and responsibilities of personnel, expert advisors and the probity auditor—matters raised in the previous audit report. The audit did not examine the RFT, which is not due to be issued until April 2007.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 42 of 2010–11)
Published: Wednesday 18 May 2011
Published
The objective of the audit was to assess whether the Council Allocation component of the RLCIP has been effectively designed, implemented and administered. The audit examined each of the three funding rounds, albeit with a focus on the first round (as it was due to be completed by 30 September 2009), with the second round not due to be completed until late in the audit timetable (31 December 2010) and third round funding agreements being signed and payments being made at the time audit work was completed.
Entity
Department of Regional Australia, Regional Development and Local Government
Performance audit (Auditor-General Report No. 4 of 2003–04)
Published: Thursday 28 August 2003
Published
The audit reviewed the efficiency and effectiveness of the Department of Health and Ageing's (Health's) planning and conduct of the review undertaken to determine the recommendation to the Government on whether or not to exercise the extension option available to the Commonwealth under the Plasma Fractionation Agreement with CSL Limited. The audit was undertaken in response to a recommendation of the Joint Committee of Public Accounts and Audit.
Entity
Department of Health and Ageing
Performance audit (Auditor-General Report No. 50 of 2005–06)
Published: Tuesday 27 June 2006
Published
The objective of the audit was to assess the framework being put in place to manage and account for aid funds provided under the AIPRD. In particular, the audit addressed: structures for oversighting the development and delivery of the AIPRD; planning and risk management (including those relating to fraud and corruption); financial management; and arrangements for ongoing monitoring and reporting. The audit focussed on the arrangements being established to monitor, evaluate and report on AIPRD implementation, rather than the management of activities and outcomes achieved. This reflects the fact that the long lead times associated with establishing such a large programme of assistance had meant that only limited activities were underway at the time of audit fieldwork. The ANAO anticipates undertaking an audit in the future of the management of activities and outcomes achieved, when more funds have been expended. It was not the purpose of this audit to examine Australia's immediate emergency and humanitarian response to the tsunami crisis.
Entity
Australian Agency for International Development; Department of Foreign Affairs and Trade
Performance audit (Auditor-General Report No. 57 of 2004–05)
Published: Tuesday 28 June 2005
Published
The objective of the audit was to assess whether purchases of goods and services are conducted in accordance with relevant legislation, Government policies and guidelines, and sound purchasing principles and practices. The audit at each entity covered the internal control framework for purchasing and purchase transactions during 2002-03 and 2003-04 and, where applicable, was based on the CPGs current at that time. The audit examined all aspects of the purchasing process from the initial requirement for purchase through to the delivery of the supply and payment. It included an examination of aselection of individual purchases at each audited entity.
Entity
Australian National University; Australian Research Council; CRS Australia; The Department of Finance and Administration
Performance audit (Auditor-General Report No. 37 of 2005–06)
Published: Wednesday 3 May 2006
Published
The objective of the audit was to assess whether selected Australian Government entities were effectively supporting their business requirements through planning for, and management of, the acquisition, disposal and use of their IPE assets. The audit reviewed each entity's policies and practices against a series of audit criteria across the following components of asset management: control environment; planning; acquisitions; operations; and disposals.
Entity
Across agencies
Performance audit (Auditor-General Report No. 41 of 2009–10)
Published: Wednesday 26 May 2010
Published
The audit objective was to assess whether agreements between Australian Government (Commonwealth) agencies reflect sound administrative practices. To meet this objective, the audit reviewed current government policy and a range of better practice guidelines, conducted interviews with agencies and examined cross-agency agreements, to formulate suitable audit criteria and subsequently develop better practice principles.
Entity
Across Entities
Insights: Audit lessons
Published: Wednesday 22 August 2018
Published
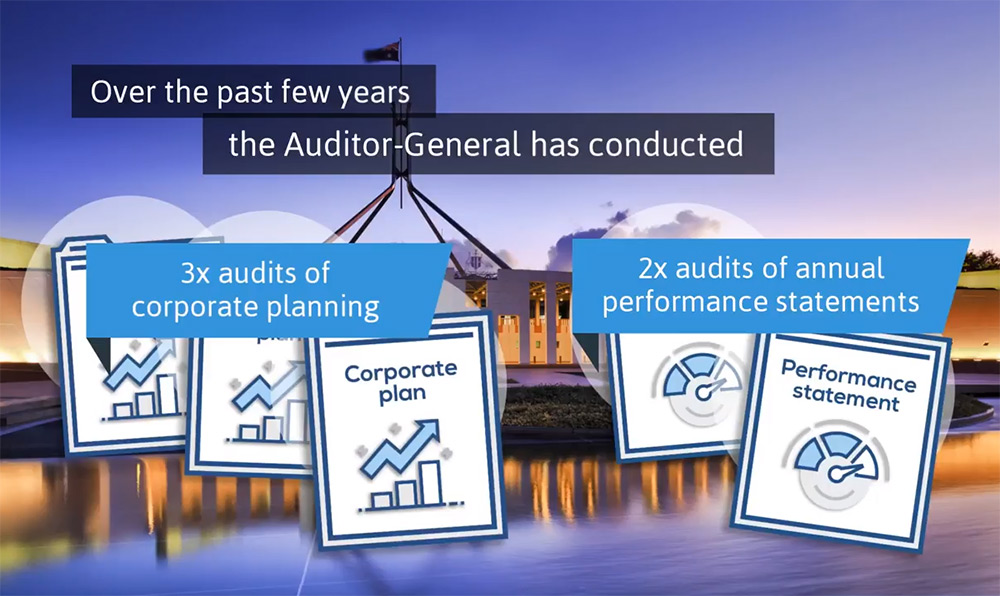
Over the past few years, the Auditor-General has conducted three audits of corporate planning and two audits of annual performance statements. This edition of audit insights examines the findings from these reports and discusses key learnings that are relevant for all Commonwealth entities.
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 43 of 2006–07)
Published: Wednesday 13 June 2007
Published
The objective of this audit was to evaluate whether selected Australian Government agencies were effectively managing security risks arising from the use of contractors. To address this objective, the audit evaluated relevant policies and practices in the audited agencies against a series of minimum requirements in the management of security issues in procurement and contracting activity. These minimum requirements were developed from the guidance and standards contained in the PSM and also from the ANAO's previous protective security audits.
The audit focused on two broad types of contracting arrangements: contracting of security functions; and contracting of any service or business function that requires, or which has the potential to require, contractors to access sensitive or security classified information.
The following Australian Government agencies were involved in this audit:
- Australian Customs Service (Customs);
- Commonwealth Superannuation Administration (ComSuper);
- Department of Finance and Administration (Finance); and
- Department of Foreign Affairs and Trade (DFAT).
In addition, the Attorney-General's Department, which is responsible for the maintenance of the PSM and for providing advice on contemporary protective security policies and practices, was consulted during the audit.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 4 of 2007–08)
Published: Wednesday 8 August 2007
Published
The objective of this follow up audit was to examine Customs' implementation of the eight recommendations in the ANAO Report No.16 2004–05 and the two related recommendations from JCPAA Report 404. The audit has had regard to issues affecting the implementation of the recommendations and has taken into account changed circumstances and new administrative arrangements since the previous audit.
Entity
Australian Customs Service
Performance audit (Auditor-General Report No. 49 of 2006–07)
Published: Monday 25 June 2007
Published
The objective of the audit was to assess the management practices undertaken by APS agencies to achieve value for money and transparency in dealing with contracts for non-APS workers. The focus of the audit was on circumstances where agencies had a significant reliance on a non-APS workforce to assist in achieving their core functions. Regular reporting by agencies of expenditure on non-APS workers was outside the scope of this audit.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 20 of 2007–08)
Published: Wednesday 23 January 2008
Published
The objective of the audit was to examine the accuracy of Medicare claims processing, including the adequacy and operation of relevant manual and system processes. The audit assessed the:
- adequacy and operation of relevant manual and system controls used to support the reliable processing of Medicare claims, and
- accuracy of the assessing and processing of Medicare claims, using Computer Aided Audit Techniques (CAATs).
Entity
Medicare Australia
Performance audit (Auditor-General Report No. 36 of 2005–06)
Published: Tuesday 2 May 2006
Published
The objective of the audit was to assess the effectiveness of management of the procurement of a major, new capability for the ADF by the DMO and Defence. The audit reviewed the initial capability requirements and approval process; analysed the contract negotiation process; and examined management of the Acquisition and Through-Life-Support Contracts. Coverage of the audit extended from development of the concept for the requirement, to acceptance of deliverables in the period prior to the award of the Australian Military Type Certificate (see shaded area of Figure 1). The audit fieldwork was undertaken during the delivery phase of the Project, following delivery of ARH numbers 1, 2 and 5.
Entity
Department of Defence; Defence Material Organisation
Performance audit (Auditor-General Report No. 28 of 2009–10)
Published: Wednesday 21 April 2010
Published
During the preparation of the ANAO's Planned Audit Work Program 2006–07, JSCEM suggested that the ANAO consider a possible performance audit into the efficiency and effectiveness of the AEC's management of elections. JSCEM's suggestion was considered in the planning and preparation for this performance audit, which focuses primarily on the AEC's administration of the CEA in the lead-up to and conduct of the 2007 general election.
Entity
Australian Electoral Commission
Performance audit (Auditor-General Report No. 31 of 2010–11)
Published: Thursday 24 February 2011
Published
The objective of the audit was to examine the Tax Office's administration of the Lost Members Register. In particular, the audit examined the Tax Office's governance arrangements for the LMR; its strategies for managing data quality; and its provision of access to LMR data. The audit also considered how the Tax Office's administration of the LMR has responded to recommendations made in the ANAO's earlier review (Audit Report No.17, 2005–06 Administration of the Superannuation Lost Members Register), relevant changes in funding and legislation supporting the LMR, as well as the Change Program.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 12 of 2003–04)
Published: Wednesday 5 November 2003
Published
The primary objective of the audit was to assess whether the Department of Communications, Information Technology and the Arts (DCITA) and the Department of Transport and Regional Services (DOTARS) were administering a number of grant programs that are designed to enhance telecommunications infrastructure and services in regional, rural and remote areas of Australia according to better practice. The audit was also aimed at determining whether DCITA had implemented the recommendations of an earlier audit of Networking the Nation.
Entity
Department of Communications, Information Technology and the Arts
Performance audit (Auditor-General Report No. 59 of 2003–04)
Published: Wednesday 30 June 2004
Published
The objective of this audit was to provide an independent assurance on the effectiveness of Defence's management of the acqusition of armoured infantry mobility vehicles (IMV) for the Australian Defence Force (ADF). The audit sought to identify the initial capability requirements; analyse the tendering and evaluation process; and examine the management of the project by Defence. As such, this was not an audit of contractor performance, but of the formation and contract management of the aquisition project by Defence.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 44 of 2006–07)
Published: Thursday 14 June 2007
Published
The objective of the audit was to assess the effectiveness of the Tribunals' management of their operations. To this end, the audit examined whether the MRT and the RRT:
- have achieved intended operational efficiencies from the introduction of common facilities, services and resourcing;
- have established appropriate arrangements for governance, business planning and guidance of Members and staff, and for performance monitoring and reporting of Tribunal operations;
- finalise cases within Tribunal time and productivity standards; and
- provide applicants with services in accordance with service standards.
The audit covered Tribunal operations for review of visa decisions. The correctness of individual decisions was not assessed as part of the audit.
The audit focused particularly on developments in the Tribunals' management performance in the four year period from 2001–02 to 2004–05.
Entity
Migration Review Tribunal; Refugee Review Tribunal
Performance audit (Auditor-General Report No. 3 of 2009–10)
Published: Tuesday 8 September 2009
Published
The focus of this audit was on those entitlements administered by Finance. Similar to the 2001-02 Audit Report, the audit scope did not include entitlements provided to persons employed under the Members of Parliament (Staff) Act 1984 (MOP(S) Act). It also did not examine the administration of entitlements provided through other agencies (such as Parliamentarians' salary and electorate allowance, which are paid by the Chamber Departments, and entitlements provided to Ministers by their home department).
Entity
Department of Finance and Deregulation
Performance audit (Auditor-General Report No. 11 of 2006–07)
Published: Thursday 9 November 2006
Published
The objective of this audit was to assess DAFF's management of the contractual arrangements in place to deliver the National Food Industry Strategy. The audit assessed: implementation of the Strategy; financial management;assessment and selection of grants and projects; management of grants and projects; monitoring and verification of contract services; and performance management. The Australian National Audit Office (ANAO) examined a number of FIG applications and projects, one food centre of excellence and a major project under the Food Market Development programme. The audit did not examine the Food Chain programme or DAFF's administration of the Strategy's government-to-government activities.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 8 of 2006–07)
Published: Wednesday 18 October 2006
Published
On 9 May 2006, the Auditor-General advised the then Minister for Transport and Regional Services that he would undertake a performance audit and that the specific audit objectives and approach would be established once officers of the Australian National Audit Office (ANAO) had the opportunity to undertake preliminary enquiries with senior staff in Airservices Australia and the Department of Transport and Regional Services (DOTARS). On 31 May 2006, the Auditor-General designated a performance audit under Section 18 of the Auditor-General Act 1997 (Auditor-General Act). The objectives of the performance audit were to: examine the development and administration by Airservices Australia of its contracts with the Solomon Islands Government for upper airspace management; assess the regularity of payments made under the contracts and steps taken by Airservices Australia in respect of any irregularities; and make recommendations for any improvements in the processes employed by Airservices Australia in developing and administering these and similar contractual arrangements.
Entity
Airservices Australia
Performance audit (Auditor-General Report No. 15 of 2003–04)
Published: Monday 1 December 2003
Published
On 2 November 2000, the Senate agreed to a resolution that the Auditor-General be requested to review all expenditures and entitlements accruing to Parliamentarians and Ministers in 1999-2000. The resolution requested that the Auditor-General consider a number of specific matters, and report by 30 June 2001. In the course of that audit, examination of issues relating to Parliamentarians' staff was deferred in order to give the Auditor-General a reasonable chance of reporting reasonably close to the Senate's requested reporting timeframe. ANAO Audit Report No.5 2001-02, Parliamentarians' Entitlements: 1999-2000, was tabled in the Parliament in August 2001. A proposed audit of the administration by Finance of the entitlements of staff engaged under the Members of Parliament (Staff) Act 1984 (MOP(S) Act was included in the ANAO Audit Work Program for 2001-02. The objectives of this performance audit were to: review the effectiveness of the internal control structures in the Department of Finance and Administration (Finance) concerning the administration of entitlements for MOP(S) Act staff; review the effectiveness and efficiency of the procurement and support services Finance provides in relation to MOP(S) Act staff: and identify principles of sound administrative practices to facilitate improved administrative arrangements for the future. The audit covered Finance's administration of payments and services to MOP(S) Act staff during the period 1998-99 to 2001-02. Sub-section 15(c) of the Auditor General Act 1997 precludes an audit of persons who are engaged under the MOP(S) Act. Accordingly, the audit scope did not include examination of the responsibilities of MOP(S) Act staff.
Entity
Department of Finance and Administration
Performance audit (Auditor-General Report No. 33 of 2009–10)
Published: Wednesday 5 May 2010
Published
The audit objective was to examine the effectiveness of the department's establishment of the P21 element of the BER program. The focus of the audit was on: the establishment of administrative arrangements for BER P21 in accordance with government policy; the assessment and approval of funding allocations; and the arrangements to monitor and report BER P21 progress and achievement of broader program outcomes. An examination of individual BER P21 projects was outside the scope of the audit.
Entity
Department of Education, Employment and Workplace Relations
Performance audit (Auditor-General Report No. 6 of 2005–06)
Published: Thursday 18 August 2005
Published
The objective of this audit was to assess whether DEWR had implemented ESC3 and its computer system EA3000, efficiently and effectively. The primary focus is on the period of change from the previous employment services contract to ESC3 and the first full year of its operation, 2003-04. The scope of the audit was limited to the implementation of Job Network services under ESC3, the introduction of the supporting computer application, EA3000, and DEWR's use of modelling to estimate the effects of the APM. The audit did not test the effectiveness of the APM. DEWR has a plan to evaluate the new model. A separate, concurrent ANAO audit assessed DEWR's oversight of Job Network services to job seekers.
Entity
Department of Employment and Workplace Relations; Centrelink
Performance audit (Auditor-General Report No. 41 of 2010–11)
Published: Tuesday 17 May 2011
Published
The objective of the audit was to examine the effectiveness of the management of maintenance of the Defence estate, taking particular account of planning and delivery aspects.
The audit examined: Defence’s policies, procedures, processes and supporting tools related to the planning and delivery of the maintenance of the estate; and services provided to Defence by private sector firms in relation to maintenance activities. The audit did not focus on contract management matters, nor on the systems used by Defence to maintain information related to estate maintenance.
Entity
Department of Defence