Browse our range of reports and publications including performance and financial statement audit reports, assurance review reports, information reports and annual reports.
Performance audit (Auditor-General Report No. 52 of 2012–13)
Published: Tuesday 25 June 2013
Published
The objective of the audit was to assess the effectiveness of the Australian Taxation Office’s administration of debt relief arrangements.
Entity
Australian Taxation Office
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 23 of 2007–08)
Published: Thursday 21 February 2008
Published
The objective of the audit was to assess whether selected regulatory agencies have cost recovery procedures and practices which comply with the Government's guidelines. To address this objective, the audit assessed the management of cost recovery against the following criteria:
- regulatory agencies have clear and consistent cost recovery procedures to identify their activities and costs, and set fees and levies;
- regulatory agencies have effectively implemented their cost recovery procedures;
- regulatory agencies regularly monitor and review their cost recovery activities; and
- regulatory agencies regularly report on their cost recovery.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 19 of 2011–12)
Published: Tuesday 20 December 2011
Published
The objective of the audit was to assess the development of Defence’s oversight and management of its portfolio of ICT investments and projects. In particular, the audit examined Defence’s:
- governance, strategic processes and decision-making structures that set out, prioritise and coordinate the integrated ICT reform portfolio and programs;
- ICT risk management and capacity to identify and plan to achieve the benefits of its SRP ICT stream reforms (including methodologies to measure the realisation of savings and non-savings benefits);
- level of portfolio and program management maturity; and
- the impact of improvement efforts on Defence’s ability to deliver the ICT services capacity required to support the SRP.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 19 of 2009–10)
Published: Friday 18 December 2009
Published
The objective of the audit was to assess how effectively DHS (including CSA), FaHCSIA and Centrelink managed the implementation of stage one of the CSSR and the Improving Compliance program.
Entity
Department of Human Services; Department of Families, Housing, Community Services and Indigenous Affairs; Centrelink
Performance audit (Auditor-General Report No. 16 of 2009–10)
Published: Wednesday 16 December 2009
Published
The objective of the audit was to assess the ACMA's effectiveness in operating, managing and monitoring the Register, including compliance with legislative requirements.
Entity
The Australian Communications and Media Authority
Performance audit (Auditor-General Report No. 45 of 2003–04)
Published: Thursday 29 April 2004
Published
The objective of the current audit was to assess Army's progress in implementing the ANAO recommendations and to examine and assess any developments in relation to AIRN since the 1999?2000 audit report and the 2001 JCPAA report. Army updated AIRN policy in 2001 and 2004, and the ANAO has assessed, where appropriate, the implementation of the 1999?2000 audit recommendations for these two policy reissues.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 44 of 2020–21)
Published: Thursday 17 June 2021
Published
The audit objective was to examine the effectiveness of the Great Barrier Reef Marine Park Authority’s regulation of permits and approvals, including its implementation of recommendations from Auditor-General Report No.3 of 2015–16 Regulation of Great Barrier Reef Marine Park Permits and Approvals.
Entity
Great Barrier Reef Marine Park Authority
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 30 of 2020–21)
Published: Tuesday 9 March 2021
Published
The objective of the audit was to examine the effectiveness of the Department of Veterans’ Affairs' (DVA's) planning and management of the Veteran Centric Reform (VCR) program.
Entity
Department of Veterans' Affairs
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 4 of 2006–07)
Published: Tuesday 12 September 2006
Published
The objective of the audit was to review the operation of the ATO's Tax Agent and Business Portals. In conducting the audit the ANAO examined three key areas: governance – the governance arrangements supporting ongoing management of the Portals; portals development, user satisfaction and realisation of expected benefits – the ATO's processes for involving users in developing the Tax Agent and Business Portals, assessing user satisfaction, and evaluating business benefits arising from uptake of the Portals; and information technology (IT) security and user access controls – the ATO's IT security environment and user access controls supporting the operation of the Tax Agent and Business Portals.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 54 of 2011–12)
Published: Wednesday 27 June 2012
Published
The objective of the audit was to assess the effectiveness of the ATO’s administration of external debt collection arrangements.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 4 of 2020–21)
Published: Monday 31 August 2020
Published
The objective of this audit was to assess the extent to which entities’ establishment and use of ICT related procurement panels and arrangements supported the achievement of value for money outcomes.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 44 of 2003–04)
Published: Tuesday 27 April 2004
Published
The audit examined ATSIS' implementation of recommendations from Audit Report No.39, 1998-1999 National Aboriginal Health Strategy - Delivery of Housing and Infrastructure to Aboriginal and Torres Strait Islander Communities (the previous audit). In addition to assessing ATSIS' progress in implementing the recommendations of the previous audit, this follow-up audit examined ATSIS' performance reporting of the NAHS program, and concluded that the current level of aggregation of performance reporting makes it difficult to identify the particular contribution that the NAHS Program makes in improving services to Indigenous communities.
Entity
Aboriginal and Torres Strait Islander Services
Performance audit (Auditor-General Report No. 22 of 2013–14)
Published: Thursday 6 March 2014
Published
The objective of the audit was to report on the progress of the current phase of the Air Warfare Destroyer (AWD) Program, which is known as SEA 4000 Phase 3–Build. This phase commenced in June 2007, and covers the finalisation of the detailed design, the signing of the Alliance and Platform System Design contracts, and the construction and delivery of the ships by the Industry Participants to the Defence Materiel Organisation (DMO).
Entity
Department of Defence; Defence Materiel Organisation
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 10 of 2008–09)
Published: Tuesday 2 December 2008
Published
The objective of this audit was to assess whether the Scheme is being administered effectively by the department. The ANAO focussed on Program Year 1 of the Scheme, 2005–06, and examined DIISR's arrangements for:
- assessing the eligibility of entities to receive grants;
- assessing entities' claims for eligible expenditure;
- adhering to the funding limits for the Scheme when calculating and paying claims, and managing any debts that arise;
- and evaluating and reporting on whether the statutory objective of the Scheme is being met.
The audit did not examine the other components of the 2005–2015 industry assistance package; nor did it examine any of the programs delivered under the previous assistance package (2000–2005).
Entity
Department of Innovation, Industry, Science and Research
Performance audit (Auditor-General Report No. 40 of 2010–11)
Published: Tuesday 17 May 2011
Published
The objective of the audit was to assess whether Defence is effectively managing the EO Services Contract.
The audit focused mainly on Defence's contract management framework, including the arrangements to monitor the contractor’s performance in delivering services under the contract. The audit also examined the processes used by Defence to develop the current version of the contract and the extent to which the revised contract, as negotiated in 2006, provides an assurance of better value for money when compared to the original contract signed in 2001.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 30 of 2014–15)
Published: Tuesday 21 April 2015
Published
The audit objective was to examine Defence’s administration of Materiel Sustainment Agreements (MSAs) and the contribution made by MSAs to the effective sustainment of specialist military equipment.
Entity
Department of Defence; Defence Materiel Organisation
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 52 of 2005–06)
Published: Thursday 29 June 2006
Published
The audit objectives were to examine the extent to which selected TSB2 and TSI Response programs: are achieving or had achieved their objectives; and had been administered effectively by DCITA according to better practice principles. To evaluate this aspect, the audit assessed DCITA's compliance with the better practice principles outlined in the Administration of Grants Better Practice Guide (May 2002) produced by the Australian National Audit Office (ANAO). There are 19 separate principles covered under the broad areas of: Planning for effective grant programs; Selecting projects; Managing and monitoring funding deeds; and Evaluating and reporting grant program performance.
Entity
Department of Communications, Information Technology and the Arts
Performance audit (Auditor-General Report No. 34 of 2009–10)
Published: Tuesday 18 May 2010
Published
The Management and use of Double Taxation Agreement Information Collected through Automatic Exchange
The objective of the audit was to review and assess the use, and management of, automatic exchanges of information under Double Taxation Agreements (DTAs) by the Tax Office.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 12 of 2004–05)
Published: Tuesday 19 October 2004
Published
The ANAO Audit Report No. 51 of 2001/02, Research Project Management, Commonwealth Scientific and Industrial Research Organisation, assessed the effectiveness of CSIRO in administering research projects to deliver required results. The audit made nine recommendations designed to improve project management in CSIRO. The purpose of this follow-up audit was to assess the extent to which CSIRO has implemented the recommendations of the previous audit and of the JCPAA.
Entity
Commonwealth Scientific and Industrial Research Organisation
Performance audit (Auditor-General Report No. 4 of 2011–12)
Published: Wednesday 31 August 2011
Published
The audit objective was to assess the effectiveness of DEEWR’s and FaHCSIA’s administration of the Australian Government’s responsibilities under Element 1 of the National Partnership Agreement on Indigenous Economic Participation (including the NT Jobs Package).
Entity
Across Entities
Performance audit (Auditor-General Report No. 51 of 2014–15)
Published: Thursday 25 June 2015
Published
The objective of the audit was to assess the effectiveness of the Australian Taxation Office’s administration of capital gains tax for individual and small business taxpayers.
Entity
Australian Taxation Office
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 32 of 2008–09)
Published: Tuesday 19 May 2009
Published
The objective of the audit was to review Defence's management of the HQJOC Project's tender process, including probity management, for the construction of the joint operation headquarters in order to provide assurance that the policy principles for the use of private financing had been followed.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 45 of 2014–15)
Published: Tuesday 9 June 2015
Published
The audit objective was to examine whether the Department of Defence provides an efficient and effective security vetting service for Australian Government entities through the Australian Government Security Vetting Agency.
Entity
Department of Defence
Contact
Please direct enquiries relating to reports through our contact page.
Major projects report (Auditor-General Report No. 20 of 2011–12)
Published: Tuesday 20 December 2011
Published
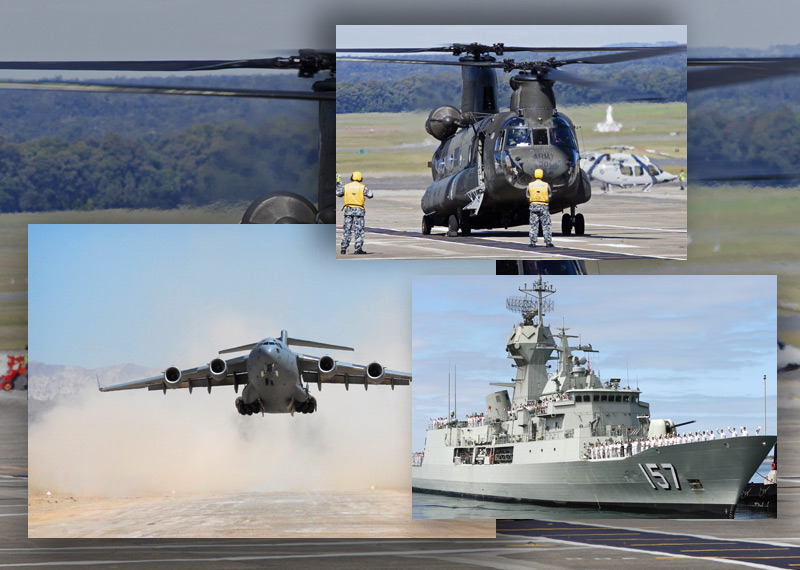
The objective of this report is to provide a formal conclusion on the review of the Project Data Summary Sheets by the Auditor-General, including comprehensive information on the status of projects as reflected in the PDSSs prepared by the DMO.
Entity
Defence Materiel Organisation
Performance audit (Auditor-General Report No. 23 of 2016–17)
Published: Monday 7 November 2016
Published
The objective of this audit was to examine the effectiveness of the Department of Social Services’ administration of NRAS allocations; processing of market rent valuations, statements of compliance and incentive payments; and the supporting business systems and processes.
Entity
Department of Social Services
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 44 of 2011–12)
Published: Tuesday 19 June 2012
Published
The objective of the audit was to assess the effectiveness of the Department of Health and Ageing's support for improved access to integrated GP and primary healthcare services through its administration of the Primary Care Infrastructure Grants (PCIG) program.
Entity
Department of Health and Ageing
Insights: Audit lessons
Published: Monday 3 April 2023
Published
This edition of Audit Insights is targeted at Australian Government officials who have responsibility for overseeing or conducting procurements, including those who only do procurement occasionally. The aim is to communicate lessons from our audit work to make it easier for people working within the Australian public sector to apply those lessons. It is drawn from audit reports tabled in 2020–21, 2021–22 and 2022–23 into Australian Government procurements.
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 50 of 2003–04)
Published: Friday 4 June 2004
Published
The objectives of the audit were to assess whether DOTARS had developed and implemented an appropriate framework and procedures to administer lessee obligations entered into as part of the 1997 and 1998 leasehold sales of 17 Federal airports. In particular, the audit sought to: - review DOTARS' monitoring of lessee compliance with the Airport Leases and supporting sale documentation; - examine the effectiveness of the framework and procedures developed by DOTARS to administer lessee development commitments; and assess the impact of changes in the aviation environment on the management and monitoring of lessee obligations.
Entity
Department of Transport and Regional Services
Speeches and papers
Published: Tuesday 24 July 2001
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented at the Public Service and Merit Protection Commission Senior Executive Service (SES) Breakfast Seminar Series
Performance audit (Auditor-General Report No. 11 of 2004–05)
Published: Thursday 14 October 2004
Published
This audit focused on the implementation of the Revised Government Foreign Exchange Risk Management Policy. Overall, the audit found the implementation of the Revised Policy with all CAC Act entities was not complete and important elements of the Revised Policy have not been adequately implemented. ANAO made five recommendations aimed at improving the compliance of GGS entities with the revised Policy, central agency consideration of entities' requests for exemption and enhancing the reporting made to Government. Finance and other entities agreed with all the recommendations.
Entity
Department of Finance and Administration