Browse our range of reports and publications including performance and financial statement audit reports, assurance review reports, information reports and annual reports.
Performance audit (Auditor-General Report No. 38 of 1996–97)
Published: Tuesday 24 June 1997
Published
The objective of this audit was to assess the effectiveness of the action taken by the Australian Institute of Marine Science in response to the recommendations contained in 'External Funds Generation', Audit Report No.48, 1991-92.
Entity
Australian Institute of Marine Science
Speeches and papers
Published: Monday 15 October 2007
Published
Mr Ian McPhee - Auditor-General for Australia, presented at the Australian Institute of Project Management, Hobart
Speeches and papers
Published: Thursday 9 November 1995
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented to the Canberra Staff of ANAO
Performance audit (Auditor-General Report No. 9 of 1998–99)
Published: Monday 28 September 1998
Published
The audit reviewed the accountability framework and performance information of the Australian Sports Commission (ASC). The objective of the audit was to form an opinion on the efficiency and effectiveness of the ASC: accountability arrangements, focussing on key stakeholders such as the Minister and the Parliament; and management information systems, focussing on performance information, in particular key performance indicators; and its use in resource allocation decision-making.
Entity
Australian Sports Commission
Performance audit (Auditor-General Report No. 18 of 2016–17)
Published: Tuesday 27 September 2016
Published
The objective of the audit was to assess the appropriateness of the use and reporting of confidentiality provisions in a sample of Australian Government contracts.
Entity
Department of Defence; Department of Foreign Affairs and Trade; Department of Agriculture and Water Resources; Department of Health
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 35 of 1997–98)
Published: Monday 2 March 1998
Published
The objective of the audit was to examine the operations of DEETYA International Services with a view to identifying the administrative issues and difficulties experienced by DEETYA in establishing a commercial entity and its subsequent operation within the framework of the Australian Public Service.
Entity
Department of Employment, Education, Training and Youth Affairs
Performance audit (Auditor-General Report No. 14 of 2001–02)
Published: Friday 28 September 2001
Published
The objective of this follow-up audit was to assess Austrade's implementation of the recommendations contained in ANAO Report No. 4 of 1998-99 (Client Service Initiatives - Australian Trade Commission (Austrade)), and whether the implementation of the recommendations or appropriate alternative measures has improved the management and delivery of Austrade's client service.
Entity
Australian Trade Commission
Speeches and papers
Published: Wednesday 15 November 1995
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented to the ANAO Graduates - Graduate Recall Day
Performance audit (Auditor-General Report No. 17 of 1999–2000)
Published: Monday 15 November 1999
Published
The audit reviewed the Commonwealth-State Housing Agreement (CSHA). CSHA is a joint arrangement between the Commonwealth and the States under which both the Commonwealth and the States contribute funding in the form of grants, which are used by State Housing Authorities to provide a variety of housing assistance programs to households on low incomes and those with special needs. The overall objective of the audit was to assess and report to Parliament on how effectively the Department of Family and Community Services (FaCS - formerly the Department of Social Security) administered the CSHA and to identify any areas where improvements could be made.
Entity
Department of Family and Community Services
Performance audit (Auditor-General Report No. 39 of 1998–99)
Published: Monday 10 May 1999
Published
The audit reviewed the National Aboriginal Health Strategy (NAHS) component of the Aboriginal and Torres Strait Islander Commission's (ATSIC) Community Housing Infrastructure Program (CHIP). A major NAHS objective is to improve environmental health in indigenous communities through the construction and housing and the provision of water, sewerage and related systems. The objective of the performance audit was to form an opinion on ATSIC's management of the National Aboriginal Health Strategy program in providing housing and related infrastructure to Aboriginal and Torres Strait Islander communities, and to identify areas where program administration could be improved.
Entity
Aboriginal and Torres Strait Islander Commission
Performance audit (Auditor-General Report No. 3 of 1997–98)
Published: Sunday 28 September 1997
Published
The objective of the audit was to examine the effectiveness of the management and control of program evaluation in the Australian Public Service. The ANAO made an assessment against criteria which were designed to test whether agencies were undertaking evaluations in a way which would enhance their overall effectiveness. The main issues examined were:
- approaches to evaluation planning;
- the conduct of individual evaluations;
- the quality of evaluation reports; and
- the impact of evaluations.
Entity
Across Agency
Performance audit (Auditor-General Report No. 32 of 1996–97)
Published: Thursday 15 May 1997
Published
The objectives of the audit were to: examine the efficiency and administrative effectiveness of grant programs administered in the APS; and identify any specific problem areas and evidence of better practice in both program administration and agency guidelines not already included in the ANAO's 1994 Better Practice Guide on the Administration of Grants. The ANAO also sought to incorporate in the revision of the better practice guide the lessons learned through the audit to help ensure its continued relevance in public sector administration at all levels of government.
Entity
Across Agency
Performance audit (Auditor-General Report No. 28 of 2011–12)
Published: Thursday 29 March 2012
Published
The objective of the audit was to assess the effectiveness of Centrelink’s QOL control, which supports the integrity of payments administered by DHS on behalf of the Australian Government.
Entity
Department of Human Services
Performance audit (Auditor-General Report No. 24 of 2020–21)
Published: Monday 14 December 2020
Published
The objective of the audit was to assess whether the Australian Taxation Office (ATO) has effectively managed risks related to the rapid implementation of COVID-19 economic response measures.
Entity
Australian Taxation Office
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 47 of 2011–12)
Published: Friday 22 June 2012
Published
The objective of the audit was to assess the effectiveness of the implementation and administration of the Small Business Superannuation Clearing House.
Entity
Department of the Treasury; Department of Human Services; Australian Taxation Office
Speeches and papers
Published: Monday 26 March 2001
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented at the Institute of Internal Auditors Australia. South Pacific and Asia Conference SOPAC 2001, Melbourne
Speeches and papers
Published: Tuesday 13 October 1998
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented at the opening Presentation to Workshop on ANAO Year 2000 Discussion Paper
Performance audit (Auditor-General Report No. 6 of 1996–97)
Published: Thursday 12 September 1996
Published
The objectives for the audit were to examine Commonwealth guarantees, indemnities and letters of comfort in relation to:
- the potential size of the Commonwealth's exposure to these instruments;
- the extent to which the overall exposures of the Commonwealth are managed and monitored;
- the adequacy of administrative reporting arrangements;
- areas of better administrative practice relating to their management; and
- to raise agencies' awareness of appropriate risk management and accountability practices in relation to these instruments.
The audit set out to quantify the Commonwealth's exposure to guarantees, indemnities and letters of comfort.
Entity
Across Agency
Speeches and papers
Published: Friday 24 September 2010
Published
Mr Ian McPhee - Auditor-General for Australia, address to the Risk Management Institution of Australasia -ACT Chapter Conference 'Building on Experience'
Performance audit (Auditor-General Report No. 5 of 2010–11)
Published: Wednesday 15 September 2010
Published
The objective of the audit was to assess DoHA's effectiveness:
- in undertaking PIP program planning, program monitoring and review; and
- with Medicare Australia, in ensuring PIP program delivery to general practices and their medical practitioners.
In undertaking the audit, the ANAO considered the 12 incentives that comprised the PIP up to August 2009. The three most recently introduced incentives at the time of audit fieldwork, namely, Domestic Violence, GP Aged Care Access and eHealth incentives, were examined in greater detail and formed case studies to support audit analysis. The ANAO also sought views on the program administration from industry, including from general practices directly through an online survey.
With regard to accreditation of general practice, the audit scope did not include an assessment of the Standards nor the work of the bodies that undertake accreditation of general practices. The ANAO's focus on general practice accreditation related to DoHA's management of program entry criteria.
Entity
Department of Health and AgeingMedicare Australia
Performance audit (Auditor-General Report No. 50 of 2010–11)
Published: Tuesday 21 June 2011
Published
The objective of the audit was to assess the effectiveness of the services delivered through ATO shopfronts to individual and micro enterprise tax clients. Particular emphasis was given to the delivery of services to clients and planning and reporting processes for shopfront services.
Entity
Australian Taxation Office
Major projects report (Auditor-General Report No. 9 of 2008–09)
Published: Thursday 27 November 2008
Published
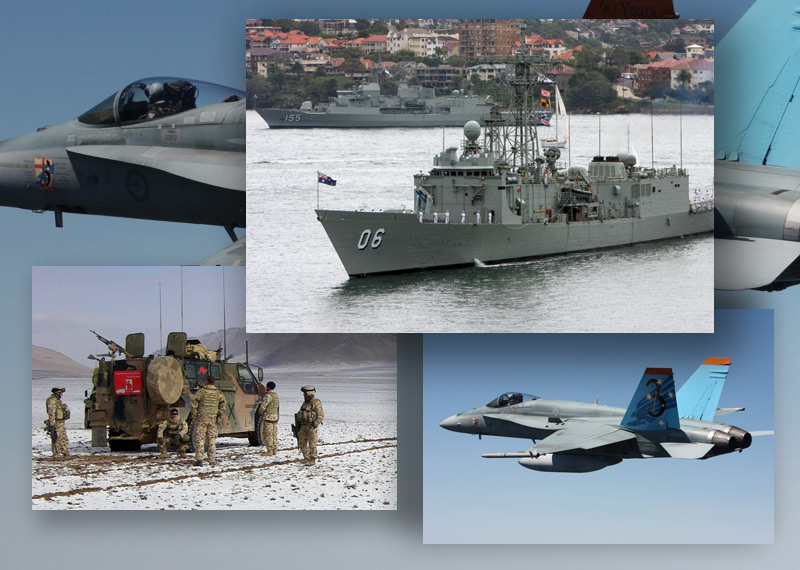
This first Assurance Report on the status of selected Defence equipment acquisition projects, which has the support of the Parliament and the Government, represents a substantial step towards improving transparency and public accountability in major Defence procurement projects. It is the pilot of an annual Defence Materiel Organisation (DMO) Major Projects Report, and was developed in conjunction with the DMO. It covers the cost, schedule and capability progress achieved by nine DMO projects, which had an approved budget totalling $13.535 billion as at 30 June 2008.
This report is organised into three parts. Part 1 comprises an ANAO overview and Auditor–General's Foreword. Part 2 comprises the Major Projects Report prepared by DMO, including an overview reflecting DMO's perspective on their business and on the nine projects included in the. Part 3 incorporates the Auditor-General's Review Report, the statement by the CEO DMO, and the information prepared by DMO in the form of standardised Project Data Summary Sheets covering each of the nine pilot projects.
In the next 12 months, the ANAO will review 15 DMO projects planned for inclusion in the 2008-09 DMO Major Projects Report, with the number of projects rising to 30 projects in subsequent years. The ANAO will also work with DMO to refine the approach adopted for providing assurance on each project's progress toward achieving Final Operational Capability. The ANAO will also consider the inclusion of an analysis of each project's emerging trends, as appropriate, to complement DMO's intention to provide improved analysis of project management performance regarding all projects included in the Major Projects Report.
Entity
Defence Materiel Organisation
Performance audit (Auditor-General Report No. 46 of 2010–11)
Published: Tuesday 31 May 2011
Published
The objective of the audit was to assess the effectiveness of DIAC’s management of the student visa program. Three key areas were examined in the audit: the processing of student visa applications; ensuring compliance with student visa conditions; and cooperation between DIAC and DEEWR.
Entity
Department of Immigration and Citizenship
Performance audit (Auditor-General Report No. 28 of 2002–03)
Published: Friday 7 February 2003
Published
The audit assessed the operations of the four Northern Territory Land Councils which provide a range of services to Aboriginal people under the Aboriginal Land Rights (Northern Territory) Act 1976. The audit also assessed the Aboriginal and Torres Strait Islander Commision's (ATSIC) administration of the Aboriginals Benefit Account, which provides funding to the Land Councils under the same Act. The objectives of the audit were to assess:
- whether the governance arrangements used by ATSIC and the Land Councils are appropriate;
- whether ATSIC meets its legislative requirements concerning the Aboriginals Benefit Account in an effective and efficient way; and
- whether the Land Councils are effective and efficient in managing their recourses to meet the objectives of the Aboriginal Land Rights (Northern Territory) Act 1976.
Entity
Aboriginal and Torres Strait Islander Commission; Anindilyakwa Land Council; Central Land Council; Northern Land Council; Tiwi Land Council
Speeches and papers
Published: Tuesday 5 February 2002
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, Closing Address for the Institute of Chartered Accountants
Speeches and papers
Published: Friday 23 August 2002
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented at the Forum of Commonwealth Agencies Seminar, Sydney, NSW
Performance audit (Auditor-General Report No. 10 of 2005–06)
Published: Friday 23 September 2005
Published
The audit objective was to examine the adequacy of Defence's and DMO's management of the nearly completed elements of Project Air 5276. The ANAO identified a number of causes for time delays and cost escalation in those elements. Those causes are outlined in the overall audit conclusions, to assist in the achievement of improvements in future planning and management of capital equipment acquisitions.
Entity
Department of Defence
Speeches and papers
Published: Thursday 2 October 2014
Published
Mr Mr Ian McPhee - Auditor-General for Australia, presented at the 2014 National Conference of the Risk Management Institution of Australasia, Brisbane
Performance audit (Auditor-General Report No. 14 of 2002–03)
Published: Tuesday 29 October 2002
Published
Pursuant to a request from the Senate Finance and Public Administration References Committee and the Auditor - General's response to the Committee, the objective of this performance audit was to examine and report on the selection of the preferred tenderer in the Health Group IT outsourcing process. In particular, the audit examined the circumstances surrounding OASITO's administration of the: - disclosure to a tenderer of information provided by other tenderers; - subsequent acceptance of a late re-pricing offer from a tenderer: and - advice to the decision- maker leading to the selection of the preferred tenderer. The audit focused particularly on assessing the administrative processes undertaken in the selection of the preferred tenderer for the Health Group. Audit emphasis was placed on the management of the probity aspects of the tender process, particularly in regard to events that occurred between June 1999, when the tenderers provided their penultimate pricing, and the selection of the preferred tenderer in September 1999.
Entity
Department of Finance and Administration
Performance audit (Auditor-General Report No. 29 of 1998–99)
Published: Tuesday 22 December 1998
Published
The audit addressed administration of migrant settlement services by DIMA, in particular:
- strategic management, including corporate planning, performance measurement and reporting arrangements; and
- operational management of some of the individual schemes operated by DIMA (the Adult English Migrant Program and Translating Interpreting Services were not covered as part of this audit).
Entity
Department of Immigration and Multicultural Affairs