Browse our range of reports and publications including performance and financial statement audit reports, assurance review reports, information reports and annual reports.
Performance audit (Auditor-General Report No. 49 of 2000–01)
Published: Tuesday 12 June 2001
Published
The audit was conducted as a joint financial statement and performance audit of HIC's IT systems. The objective of the financial statement component of the audit was to express an opinion on whether HIC could rely on its IT systems to support production of a reliable set of balances for the financial statements. The objective of the performance audit component was to determine whether HIC's IT systems' outputs met quality and service delivery targets.
Entity
Health Insurance Commission
Performance audit (Auditor-General Report No. 51 of 1999–2000)
Published: Thursday 29 June 2000
Published
The objective of the audit was to examine program management in the Training and Youth Division of the Department of Education, Training and Youth Affairs. In broad terms, the audit focused on the management frameworks at both Divisional and program level. Three of the Division's programs were selected for more detailed review as follows:
- Workplace English Language and Literacy;
- Literacy and Numeracy; and
- Support for New Apprentices.
Entity
Department of Education, Training and Youth Affairs
Performance audit (Auditor-General Report No. 41 of 2007–08)
Published: Wednesday 18 June 2008
Published
The objective of this audit was to assess the effectiveness of personnel security arrangements at selected Australian Government organisations, including whether they satisfied the requirements of the PSM.
To address this objective, the audit examined the extent to which the selected organisations implemented the 14 recommendations from the three previous reports.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 19 of 2007–08)
Published: Tuesday 22 January 2008
Published
The current audit has focussed on Stage 2 of the Scheme. Its objective was to assess whether ACIS is being administered effectively by DIISR and, as relevant, by Customs. In particular, the audit examined the department's arrangements for:
- assessing the eligibility of participants to receive duty credits;
- calculating duty credits accurately and adhering to the funding limits for the Scheme;
- checking the integrity of participants' claims, which are self-assessed;
- accounting for the duty credits transferred to and used at Customs; and
- measuring and reporting on the performance of ACIS.
The audit also followed up on whether the ANAO's previous recommendations have been addressed.
Entity
Department of Innovation, Industry, Science and Research; Australian Customs Service
Performance audit (Auditor-General Report No. 39 of 2000–01)
Published: Monday 28 May 2001
Published
The audit was conducted as a joint financial statement and performance audit of Centrelink's Information and Technology (I&T) systems. The objective of the financial statement component of the audit was to express an opinion on whether Centrelink could rely on its I&T systems to support production of a reliable set of financial information for the financial statements. The objective of the performance audit component was to determine whether Centrelink's I&T systems outputs adequately met quality and service delivery targets.
Entity
Centrelink
Performance audit (Auditor-General Report No. 45 of 2001–02)
Published: Wednesday 1 May 2002
Published
An Assurance and Control Assessment audit of recordkeeping was undertaken across four Commonwealth organisations to assess whether their recordkeeping policies, systems and processes accord with requirements under the Archives Act 1983, with relevant government policies, and with accepted standards and recordkeeping principles; and to identify better practices and recommend improvements. The audit addressed both electronic and traditional records.
Entity
Across Agency
Performance audit (Auditor-General Report No. 2 of 2008–09)
Published: Wednesday 6 August 2008
Published
The objective of this audit was to assess the effectiveness of Tourism Australia's governance arrangements, the management of its marketing contracts, and whether outcomes are being achieved. The audit reviewed Tourism Australia's:
- procurement processes for selecting service providers;
- management of service provider contracts; and
- governance framework including planning, performance management and reporting.
Entity
Tourism Australia
Performance audit (Auditor-General Report No. 52 of 2000–01)
Published: Monday 18 June 2001
Published
The audit reviewed the operation of the payment of accounts function in 8 Commonwealth organisations against their internal control framework. The main objectives of the audit were to determine whether organisations had implemented appropriate risk management strategies for the processing of accounts and whether payment for goods ans services had been properly authorised. The audit also reviewed progress since the payment of accounts audit undertaken in 1996 ( Audit Report No. 16, 1996-97, Financial Control and Administration Audit, Payment of Accounts).
Entity
Across Agency
Performance audit (Auditor-General Report No. 44 of 2009–10)
Published: Wednesday 16 June 2010
Published
The audit objective was to assess the Tax Office's effectiveness in administering the tax obligations of non-residents.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 40 of 2004–05)
Published: Thursday 14 April 2005
Published
The objectives of the audit were to determine whether FaCS and Centrelink had: a valid Business Case for the Edge project, as revised from time to time, including estimated costs, actual costs, and expected benefits; effective governance of the project, including reviews at critical points in the project and subsequent decisions to continue or, in the final analysis, to discontinue; an appropriate contract with SoftLaw, which was adequately managed; delivered appropriate advice on progress, project viability, and acceptable solutions to technical issues to Executive of FaCS and Centrelink during the project; and valid reasons for discontinuing the project. The ANAO began this audit in March 2004, four months after the Edge project was terminated, following the Auditor-General's agreement to a suggestion by the Joint Committee of Public Accounts and Audit that the project was a suitable subject for audit.
Entity
Department of Family and Community Services; Centrelink
Performance audit (Auditor-General Report No. 5 of 2003–04)
Published: Thursday 11 September 2003
Published
This report relates to the fourth audit of Financial Management and Accountability Act 1997 (FMA Act) agencies' compliance with the Order of the Senate for Departmental and Agency Contracts, (the Senate Order) to list, on the Internet, contract details for the reporting period 4 February 2002 to 3 February 2003. The audit was conducted in accordance with the Senate Order request for the Auditor-General to undertake twice-yearly examinations of agency contracts listed on the Internet, and to report whether there had been any inappropriate use of confidentiality provisions. The objectives of the audit were to assess agency performance in relation to compiling the Internet listings required by the Senate Order and the appropriateness of the use of confidentiality provisions in Commonwealth contracts.
Entity
Australian Federal Police (AFP);; Australian Greenhouse Office (AGO);; Department of Defence (Defence);; Department of Employment and Workplace Relations (DEWR);; Department of Family and Community Services (FaCS);1 and; National Capital Authority (NCA)
Performance audit (Auditor-General Report No. 3 of 2005–06)
Published: Thursday 28 July 2005
Published
The objective of the audit was to provide an independent assurance on the effectiveness of the management of the upgrade of the M113 fleet for the Australian Defence Force (ADF). The audit sought to identify the initial capability requirements and approval process; analyse the contract negotiation process; and examine the management of the project and contracts.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 41 of 2006–07)
Published: Thursday 31 May 2007
Published
The objective of the audit was to assess the efficiency and the effectiveness of DEWR's administrative oversight for the WfD programme. The components of administration examined included whether:
- the operation of the WfD programme was guided by sound business planning including risk assessment;
- DEWR effectively and efficiently managed, monitored and reported the performance of CWCs in meeting contractual obligations;
- adequate support was provided to DEWR contract managers and account managers to assist in the delivery of WfD outcomes;
- there was evaluation of the performance of CWCs in delivering WfD objectives on behalf of the department;
- DEWR measures the effectiveness of WfD against programme objectives; and
- DEWR had implemented agreed recommendations from the previous WfD audit, where current and relevant.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 2 of 2005–06)
Published: Friday 15 July 2005
Published
The objective of this follow-up audit was to assess the extent to which APRA has implemented recommendations regarding the supervisory framework and cross-border banking made in ANAO's 2001 audit of bank prudential supervision.
Entity
Australian Prudential Regulation Authority
Performance audit (Auditor-General Report No. 7 of 2004–05)
Published: Monday 9 August 2004
Published
The objective of the follow-up audit was to assess how well the ATO has implemented the recommendations of Audit Report No.3 of 2001-2002, The Australian Taxation Ofiice's Administration of Taxation Rulings. As part of the audit we also considered the ATO's progress in addressing the JCPAA's suggestions resulting from its review of Report No.3 of 2001-2002.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 59 of 2003–04)
Published: Wednesday 30 June 2004
Published
The objective of this audit was to provide an independent assurance on the effectiveness of Defence's management of the acqusition of armoured infantry mobility vehicles (IMV) for the Australian Defence Force (ADF). The audit sought to identify the initial capability requirements; analyse the tendering and evaluation process; and examine the management of the project by Defence. As such, this was not an audit of contractor performance, but of the formation and contract management of the aquisition project by Defence.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 15 of 2008–09)
Published: Thursday 18 December 2008
Published
The objective of the audit was to assess the effectiveness of AIMS administration of its co investment research program.
Entity
Australian Institute of Marine Science
Performance audit (Auditor-General Report No. 45 of 2000–01)
Published: Tuesday 5 June 2001
Published
The audit reviewed the fraud control arrangements in the Department of Family and Community Services (FaCS), a policy formulation, and advising body and major purchaser of social welfare services from Centrelink. The objective was to assess whether FaCS had:
- implemented appropriate fraud control arrangements in line with the Fraud Control Policy of the Commonwealth and that these arrangements operated effectively in practice; and
- fulfilled its responsibilities as a purchaser of services in relation to fraud control.
This audit is one in a series of fraud control audit and is complemented by a similar audit of Centrelink, a major provider of services on behalf of FaCS.
Entity
Department of Family and Community Services
Performance audit (Auditor-General Report No. 28 of 2008–09)
Published: Wednesday 22 April 2009
Published
The objective of the audit was to examine the quality and integrity of DVA's income support records and to report on the effectiveness of the department's management of the data and how it impacts on service delivery.
Entity
Department of Veterans' Affairs
Performance audit (Auditor-General Report No. 6 of 2004–05)
Published: Thursday 5 August 2004
Published
The objective of the audit were to assess the extent to which agencies' performance management systems, strategies and plans are consistent with the strategic framework set out in the Managment Advisory Committee Report; provide assurance that the administration of performance managment is being implemented efficiently and effectively in accordance with better practice principles; provide assurance that performance linked remuneration reported in anual reports complies with the Department of Prime Minister and Cabinet Requirements for Annual Reports; and quantify the cost of performance linked remuneration, both performance bonuses and performance linked advancements (salary increments), across the APS.
Entity
Across Entities
Performance audit (Auditor-General Report No. 4 of 1999–2000)
Published: Thursday 22 July 1999
Published
The audit reviewed fraud control arrangements in the Department of Employment, Education, Training and Youth Affairs. The objective of this audit was to establish whether the Department had developed a sound fraud control framework by examining the arrangements for: · policy and planning; · performance assessment; · quality assurance; and · training and awareness raising.
Entity
Department of Education, Training and Youth Affairs
Performance audit (Auditor-General Report No. 31 of 2013–14)
Published: Thursday 8 May 2014
Published
The objective of the audit was to assess the adequacy and effectiveness of the AEC’s implementation of the recommendation made in ANAO Audit Report No. 28 2009–10 relating to the transport and storage of completed ballot papers.
Entity
Australian Electoral Commission
Contact
Please direct enquiries relating to reports through our contact page.
Major projects report (Auditor-General Report No. 17 of 2010–11)
Published: Tuesday 30 November 2010
Published
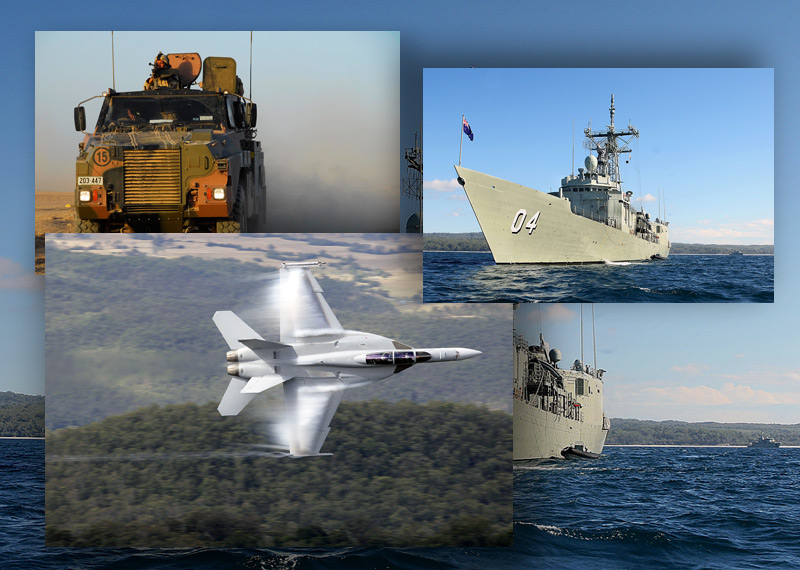
The objective of this report is to provide comprehensive information on the status of projects as reflected in the Project Data Summary Sheets (PDSSs) prepared by DMO, and a review by the ANAO.
Entity
Defence Materiel Organisation
Performance audit (Auditor-General Report No. 18 of 2005–06)
Published: Wednesday 30 November 2005
Published
The objective of the audit was to assess the administrative effectiveness of the CCAS. The audit focused on the following key areas: targeting non-compliance; real time compliance activity; post transaction compliance activity; and planning and performance evaluation. As the imports phase of the Integrated Cargo System (ICS) was only introduced in October 2005, this system was not reviewed as part of the audit. Our audit programme for 2005–06 includes ICS as a potential audit topic.
Entity
Australian Customs Service
Performance audit (Auditor-General Report No. 8 of 2005–06)
Published: Friday 26 August 2005
Published
The objective of the audit was to assess the Personnel Management Key Solution Project's planning and approval processes and its contract and project management. The audit addresses the scope of the delivered system, the expectations of end-users, and the system's ability to meet their capability requirements.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 9 of 2004–05)
Published: Wednesday 25 August 2004
Published
The audit examined the range of support made available to ADF personnel making the transition from military to civilian life, the extent to which the assistance is utilised, the cost to Defence of such assistance and the relevant responsibilities of those who deliver assistance.
Entity
Department of Defence; Department of Veterans' Affairs
Performance audit (Auditor-General Report No. 37 of 2000–01)
Published: Wednesday 23 May 2001
Published
The audit reviewed the Australian Taxation Office's use of audit of individual taxpayers as part of its approach to encouraging taxpayer compliance. The objective of the audit was to examine the use of audit as an element of the compliance management function within the Individuals Non-Business line of the ATO.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 32 of 2008–09)
Published: Tuesday 19 May 2009
Published
The objective of the audit was to review Defence's management of the HQJOC Project's tender process, including probity management, for the construction of the joint operation headquarters in order to provide assurance that the policy principles for the use of private financing had been followed.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 15 of 2010–11)
Published: Thursday 18 November 2010
Published
The objective of the audit was to assess FSANZ's administration of its food standard functions, as specified in the Food Standards Australia New Zealand Act, 1991 (last amended 2007).
Particular emphasis was given to whether:
- FSANZ's performance management and reporting provided effective support and ensures accountability;
- FSANZ effectively administered its food standard development and variation function, including its stakeholder management; and
- FSANZ effectively monitored the implementation of its standards and coordinates relevant jurisdictions to address market failures.
Entity
Food Standards Australia New Zealand
Performance audit (Auditor-General Report No. 37 of 2009–10)
Published: Thursday 20 May 2010
Published
The objective of this audit was to review the effectiveness of Defence's and the DMO's management of the acquisition arrangements for JP 2070.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 9 of 2005–06)
Published: Tuesday 6 September 2005
Published
The objective of this audit was to assess the provision of export assistance and support to new and irregular exporters in rural and regional Australia through the TradeStart program. The focus on rural and regional Australia reflects the priority given by the Government to providing effective business and trade assistance to small businesses and rural and regional businesses. However, broader aspects of TradeStart management, such as contract and risk management, have been assessed across the program as a whole.
Entity
Australian Trade Commission (Austrade)
Performance audit (Auditor-General Report No. 16 of 2005–06)
Published: Thursday 17 November 2005
Published
The audit was conducted at the: Australian Federal Police (AFP) and the Australian Protective Service (PS); Australian Sports Commission (ASC); Department of Communications, Information Technology and the Arts (DoCITA); Department of Family and Community Services (FaCS); and Civil Aviation Safety Authority (CASA). The objectives of the audit were to: determine whether entities had established appropriate arrangements in relation to the management of annual leave For the purposes of this audit the ANAO has used the term ‘annual leave'. However entities refer to this entitlement using other terminology such as recreation leave, planned leave or personal leave. and had effective internal controls over leave processing; assess whether leave had been managed in accordance with the requirements of the respective entity's certified agreement; and identify sound and better practices in the management and processing of leave.
Entity
Across Entities
Performance audit (Auditor-General Report No. 51 of 2001–02)
Published: Thursday 23 May 2002
Published
The objective of this audit was to assess the effectiveness of CSIRO in administering research projects to deliver required results. In particular, the audit examined:
- structures for project management in CSIRO;
- the alignment of project with strategic objectives;
- the adequacy of project planning; and
- CSIRO's approach to assessing project outcomes.
Entity
Commonwealth Scientific and Industrial Research Organisation
Performance audit (Auditor-General Report No. 2 of 2007–08)
Published: Wednesday 18 July 2007
Published
The objective of this audit is to examine DIAC's implementation of the nine recommendations made in the earlier audit. The audit has also taken into account changed circumstances since the original audit. These include a heightened security environment after 11 September 2001 and the results of other relevant ANAO performance audit and financial statement work. The audit also examined ETA decision-making processes to gain assurance about its robustness in a changing risk environment. This issue came to attention in recent audits of visa management processes.
Entity
Department of Immigration and Citizenship
Performance audit (Auditor-General Report No. 47 of 2008–09)
Published: Thursday 25 June 2009
Published
The objective of the audit was to examine if AFMA is effectively undertaking its regulatory compliance responsibilities in respect of domestic fishing in Commonwealth fisheries. Particular emphasis was
given to:
- the licensing of fishers and related transaction processing;
- the management of fishing quota by concession holders and AFMA; AFMA's domestic compliance monitoring and
- enforcement activities; and the governance arrangement for domestic fishing compliance.
Entity
Australian Fisheries Management Authority
Performance audit (Auditor-General Report No. 13 of 2005–06)
Published: Tuesday 18 October 2005
Published
The objective of the audit was to assess the administrative effectiveness of the ATO's management of GST compliance in the large business market segment. In conducting the audit the ANAO examined three key areas: governance - ILEC's corporate planning and reporting arrangements relevant to the management of GST compliance in the large business market segment; assessing and identifying compliance risks- how ILEC collects information relating to the large business market segment and how it uses this information to support risk identification and assessment; and managing compliance- compliance planning and the products and processes used by ILEC to manage GST compliance in the large business market segment and evaluating compliance outcomes to support future compliance planning and the targeting of GST compliance risks. In undertaking the audit, the ANAO took account of the findings of previous reviews, in particular the LCCP Review.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 33 of 2007–08)
Published: Thursday 15 May 2008
Published
The objective of the audit was to assess the effectiveness of the NCA's management of its asset portfolio. This included examining its asset management systems and the management of selected contracts that the NCA has in place to maintain specific assets.
Entity
National Capital Authority
Performance audit (Auditor-General Report No. 6 of 2010–11)
Published: Tuesday 21 September 2010
Published
The objective of the audit was to assess the implementation of the Australian Taxation Office's Client Contact – Work Management – Case Management system (CWC). The audit examined four key areas that included:
- progress of the CWC against the endorsed Change Program business case;
- improvements to the productivity and efficiency of tax administration as a result of the implementation of the CWC;
- improvements to client experiences when dealing with the Tax Office as a result of the implementation of the CWC; and
- effects of the CWC implementation, including additional benefits achievable beyond its current capacity to further improve tax administration.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 33 of 2005–06)
Published: Thursday 2 March 2006
Published
The objective of this follow-up audit was to examine the ATO's implementation of the 20 recommendations in: The Administration of Petroleum Excise Collections (Audit Report No.17, 2001(02); and The Administration of Tobacco Excise (Audit Report No. 55, 2001(02), having regard to any changed circumstances, or new administrative issues, affecting implementation of those recommendations. The audit also aimed to identify scope for improvement in the ATO's administration of petroleum and tobacco excise. Follow-up audits are recognised as an important element of the accountability processes of Commonwealth administration. The Parliament looks to the Auditor-General to report, from time to time, on the extent to which Commonwealth agencies have implemented recommendations of previous audit reports. Follow-up audits keep the Parliament informed of progressive improvements and current challenges in areas of Commonwealth administration that have previously been subject to scrutiny through performance audits.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 18 of 1997–98)
Published: Thursday 4 December 1997
Published
The objective of the audit was to determine the extent to which the new Commonwealth services delivery arrangements were implemented efficiently and effectively. The audit focussed on the establishment of Centrelink to deliver services on behalf of purchaser departments and the development of associated purchaser/provider arrangements.
Entity
Centrelink
Performance audit (Auditor-General Report No. 32 of 2002–03)
Published: Wednesday 5 March 2003
Published
This is the third audit report undertaken by the ANAO in response to a request made by the Senate in the Senate Order for Departmental and Agency Contracts, which requires all Financial Management and Accountability Act 1997 (FMA Act) agencies to place on the Internet, lists of contracts of $100 000 and more by the tenth day of the Spring and Autumn sittings of Parliament. It relates to the audit of the contract information to be listed on the Internet by the tenth day of the Autumn 2002 sitting. The audit involved a desktop review of all FMA Act agencies' Internet listings; and a detailed review in six selected agencies, of the process for making the Internet listings, and the policies and practices for determining and identifying whether contracts contained either confidential provisions and other requirements of confidentiality.
Entity
Across Agency
Performance audit (Auditor-General Report No. 22 of 2007–08)
Published: Thursday 14 February 2008
Published
The objective of this performance audit was to assess the effectiveness of the administration of grants made to the ARTC. The audit involved an examination of DOTARS' administration of the grant funding approved for, and paid to, the ARTC (in respect of both the grants paid for projects approved under legislation and the three special grants). It also involved consideration of the role of Finance and the Department of the Prime Minister and Cabinet (PM&C) in advising on the special grant funding and (in respect of Finance) the payment and reporting arrangements for the grants. The audit was conducted under Section 18 of the Auditor-General Act 1997.
Entity
Department of Infrastructure, Transport, Regional Development and Local Government
Performance audit (Auditor-General Report No. 34 of 2007–08)
Published: Wednesday 21 May 2008
Published
The objective of the audit was to determine the effectiveness of DoHA's administration of the MoU between the Government and the pathology profession, including monitoring whether the MoU is achieving its objectives
Entity
Department of Health and Ageing
Performance audit (Auditor-General Report No. 26 of 2007–08)
Published: Thursday 28 February 2008
Published
The objective of the audit was to assess DAFF's implementation and administration of the three forest industry assistance programs under the TCFA. Particular emphasis was given to the:
- implementation of the programs and ongoing governance arrangements;
- promotion of the program and the development of program guidelines;
- assessment of applications and approval of funding; and
- management of funding agreements.
Entity
Department of Agriculture Fisheries and Forestry
Performance audit (Auditor-General Report No. 46 of 2000–01)
Published: Wednesday 6 June 2001
Published
The objective of the audit was to report to Parliament on the ATO's management of its performance reporting within the outcomes and outputs framework and to identify potential areas for improvement in specifying, measuring, administering and reporting under that framework.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 28 of 2005–06)
Published: Tuesday 31 January 2006
Published
The objective of this performance audit was to assess agencies' financial management of, and accountability for, the use of net appropriation agreements to increase available appropriations.
Entity
Across Agencies
Performance audit (Auditor-General Report No. 47 of 2006–07)
Published: Thursday 21 June 2007
Published
The objective of the audit was to assess the coordination of Australian Government assistance to Solomon Islands through RAMSI, including the establishment of objectives and an outcomes monitoring framework. In particular, the audit examined arrangements for: coordination between Australian Government agencies; strategic planning and risk management; measuring the effectiveness of RAMSI; and reporting to RAMSI's Australian stakeholders.
Entity
Department of Foreign Affairs and Trade; Australian Agency for International Development
Performance audit (Auditor-General Report No. 9 of 2012–13)
Published: Thursday 1 November 2012
Published
The objective of the audit was to assess the management and effectiveness of DCO’s delivery and coordination of support services to ADF families, in particular support services provided when an ADF member is seriously injured or ill, or dies in service.
Entity
Department of Defence, Department of Veterans' Affairs
Performance audit (Auditor-General Report No. 19 of 2005–06)
Published: Thursday 1 December 2005
Published
The objective of this audit was to assess the effectiveness of the actions taken by AQIS and BA to strengthen the administration of quarantine. The audit focussed on progress in implementing the recommendations from the previous ANAO audit, and recommendations made in the JCPAA's inquiry. (The audit did not address four JCPAA recommendations that were either not supported by the Government, or were policy matters for the Government to consider. See Appendix 1.)
Entity
Department of Agriculture Fisheries and Forestry; Biosecurity Australia
Performance audit (Auditor-General Report No. 43 of 2000–01)
Published: Friday 1 June 2001
Published
The audit examined the design, management and reporting of performance information for the Natural Heritage Trust (NHT) which is administered by the Commonwealth Departments of Environment and Heritage, and Agriculture, Fisheries and Forestry. The objective of the audit was to examine and report on the performance information used to support the administration of $1.5 billion in Commonwealth financial assistance; and compliance with legislative requirements for performance monitoring and reporting.
Entity
Agriculture Fisheries and Forestry - Australia; Department of the Environment and Heritage; Department of Agriculture
Performance audit (Auditor-General Report No. 40 of 1999–2000)
Published: Wednesday 26 April 2000
Published
Tactical fighter operations (TFOs) form the basis of Australia's current military capability to ensure air superiority. Air superiority over the Australian territory and maritime approaches is an essential element in Australia's defence strategy. The audit objectives were to:
- assess whether the resources used to provide the F/A-18 tactical fighter force operational capability are managed cost-effectively; and
- identify areas for improvement in the coordination, planning and practices employed in administration of tactical fighter operations.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 11 of 2007–08)
Published: Wednesday 31 October 2007
Published
The audit follows on from Audit Report No. 45 2004-2005, Management of Selected Defence Systems Program Offices, May 2005. That report is being considered by the JCPAA, as part of its current inquiry into Defence Financial Management and Equipment Acquisition at the Department of Defence and DMO.
Entity
Department of Defence; Defence Materiel Organisation
Performance audit (Auditor-General Report No. 25 of 2003–04)
Published: Thursday 5 February 2004
Published
The audit examined agency approaches to the management of intellectual property under its control, and identified themes common to the management of all types of intellectual property. The audit objective was to:
(i) form an opinion on whether Commonwealth agencies have systems in place to efficiently, effectively and ethically manage their intellectual property assets; and
(ii) identify areas for better practice in intellectual property management by those agencies.
Entity
Australian Nuclear Science and Technology Organisation; Department of Defence
Performance audit (Auditor-General Report No. 14 of 2010–11)
Published: Thursday 28 October 2010
Published
The objective of the audit was to assess whether entities properly accounted for software assets, and adopted an integrated planning approach to inform software asset investment decisions.
The main focus of the audit was on whether entities accounted for software costs in accordance with relevant accounting standards and the FMOs, paying particular attention to the standard elements of an internal control framework and accounting practices. In addition, in the context of software asset planning, the audit considered whether entities assessed the risks associated with software assets, used life-cycle costing approaches, and aligned ICT and capital management plans, to inform decision-making on software asset investments.
Entity
Australian Bureau of Statistics; Civil Aviation Safety Authority; IP Australia
Performance audit (Auditor-General Report No. 9 of 2001–02)
Published: Thursday 16 August 2001
Published
The audit examined some key aspects of HRD in relation to Centrelink's Customer Service Officers (CSOs). The objective of the audit was to determine whether Centrelink had appropriate systems and strategies in place to ensure that its CSOs had access to the skills and knowledge necessary to meet expected levels of performance and customer service.
Entity
Centrelink
Performance audit (Auditor-General Report No. 29 of 2013–14)
Published: Wednesday 7 May 2014
Published
The objective of the audit was to assess the effectiveness of ARPANSA’s management of the regulation of Commonwealth nuclear, radiation facilities and sources, including ARPANSA’s compliance with its legislative requirements.
Entity
Australian Radiation Protection and Nuclear Safety Agency
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 13 of 2010–11)
Published: Thursday 28 October 2010
Published
The Civil Aviation Safety Authority (CASA) is responsible for regulating aviation safety in Australia, the safety of Australian aircraft operating overseas as well as for regulating and administering Australia's airspace. In September 2008, the Senate Committee on Rural and Regional Affairs and Transport presented a report on the Administration of the Civil Aviation Safety Authority and related matters. That report made three recommendations, one of which requested an Australian National Audit Office (ANAO) audit of CASA's implementation and administration of the regulation of aircraft operators' Safety Management Systems (SMS'). ANAO agreed to this request with the objective of the audit being to assess CASA's implementation and administration of an SMS approach to regulating aircraft operators.
An SMS is a systematic approach to managing safety, which encompasses organisational structures, accountabilities, policies and procedures. Amendments to the Convention on International Civil Aviation (commonly referred to as the Chicago Convention) made in 2006 require that contracting states regulate the SMS' of aircraft operators. As a contracting state to the Chicago Convention, Australia is required to mandate that aircraft operators implement an SMS.
Entity
Civil Aviation Safety Authority
Performance audit (Auditor-General Report No. 38 of 2000–01)
Published: Thursday 24 May 2001
Published
The audit's main objectives were to:
- examine the guidance on the use of confidentiality clauses in contracts and agencies' use of such clauses;
- develop criteria to assist agencies in determining what information in a contract is confidential; and
- assess the effectiveness of the existing accountability and disclosure arrangements for Commonwealth contracts.
Entity
Across Agency
Major projects report (Auditor-General Report No. 15 of 2012–13)
Published: Wednesday 19 December 2012
Published
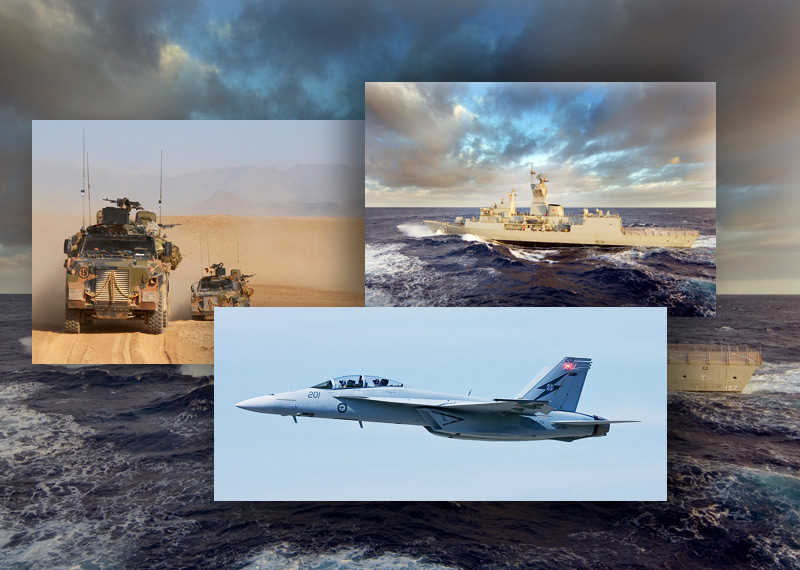
The objective of this report is to provide comprehensive information on the status of selected Major Projects, as reflected in the Project Data Summary Sheets prepared by the DMO, and the Statement by the Chief Executive Officer (CEO) of the DMO, and including the ANAO’s review of the preparation of the PDSSs by the DMO.
Entity
Defence Materiel Organisation
Performance audit (Auditor-General Report No. 17 of 2005–06)
Published: Tuesday 29 November 2005
Published
The objective of the audit was to assess the ATO's administration of the LMR. Specifically, the audit sought to: examine and report on aspects of LMR governance; assess the systems, processes and controls used by the ATO to capture and process LMR data reported by providers; examine the mechanisms and strategies the ATO uses to gain assurance that providers are complying with LMR legislation; and assess the mechanisms and strategies the ATO uses to promote awareness of, and enable access to, the LMR.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 46 of 2001–02)
Published: Monday 6 May 2002
Published
The Department of Veterans' Affairs (DVA) uses information technology (IT) extensively in providing services to Australia's veteran and defence force communities. The audit reviewed DVA's management of its IT outsourcing contract. The audit considered DVA's planning to meet its strategic IT needs through the IT outsourcing contract, the provisions of the contract, contract administration, management of the impacts of the outsourced services on DVA's business and the outcomes of DVA's approach to the contract.
Entity
Department of Veterans' Affairs
Performance audit (Auditor-General Report No. 27 of 2006–07)
Published: Wednesday 21 February 2007
Published
This audit focuses on the Australian Defence Force's (ADF) Air Combat fleet's logistics support, regular maintenance and structural refurbishment. These activities are collectively referred to as fleet in-service support. The current Defence White Paper states that Air Combat is the most important single capability for the defence of Australia.
The audit objective was to assess the effectiveness of the Air Combat fleet's in-service support arrangements to provide capability for air combat operations. Capital equipment acquisition projects covered by this report are limited to the Hornet and F-111 structural refurbishment projects, which aim to ensure these aircraft remain serviceable until their withdrawal from service.
Entity
Department of Defence; Defence Materiel Organisation
Performance audit (Auditor-General Report No. 21 of 2007–08)
Published: Thursday 7 February 2008
Published
The objective of this audit was to assess and report on the administration of the regional delivery of NHT 2 and the NAP.
The scope of the audit encompassed both Environment and DAFF, including the Joint Team of staff from both departments working together under a common management structure for the delivery of both programs. The audit focused on:
- the implementation of the regional delivery arrangements;
- governance and financial management for regional delivery; and
- monitoring, evaluation and reporting on the programs' performance.
Entity
Department of the Environment, Water, Heritage and the Arts; Department of Agriculture, Fisheries and Forestry
Performance audit (Auditor-General Report No. 36 of 2005–06)
Published: Tuesday 2 May 2006
Published
The objective of the audit was to assess the effectiveness of management of the procurement of a major, new capability for the ADF by the DMO and Defence. The audit reviewed the initial capability requirements and approval process; analysed the contract negotiation process; and examined management of the Acquisition and Through-Life-Support Contracts. Coverage of the audit extended from development of the concept for the requirement, to acceptance of deliverables in the period prior to the award of the Australian Military Type Certificate (see shaded area of Figure 1). The audit fieldwork was undertaken during the delivery phase of the Project, following delivery of ARH numbers 1, 2 and 5.
Entity
Department of Defence; Defence Material Organisation
Performance audit (Auditor-General Report No. 18 of 2001–02)
Published: Thursday 1 November 2001
Published
The ANAO examined the performance information in the 2000-01 Portfolio Budget Statements (PBS) for a mix of ten small and large agencies. The objective of the audit was to assess the appropriateness of the performance information in the selected PBS, the reporting of performance information in annual reports and agency arrangements to identify and collect this information.
Entity
Across Agency
Performance audit (Auditor-General Report No. 13 of 2007–08)
Published: Thursday 1 November 2007
Published
This second audit report relating to SMSFs examines the effectiveness of the Tax Office's approach to managing SMSF compliance risks. Specifically the ANAO examined the processes the Tax Office uses to:
- identify the risks relevant to SMSFs not complying with their obligations under the SISA, including members accessing their superannuation early;
- mitigate SMSF compliance risks; and
- administer fund wind-ups.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 12 of 2004–05)
Published: Tuesday 19 October 2004
Published
The ANAO Audit Report No. 51 of 2001/02, Research Project Management, Commonwealth Scientific and Industrial Research Organisation, assessed the effectiveness of CSIRO in administering research projects to deliver required results. The audit made nine recommendations designed to improve project management in CSIRO. The purpose of this follow-up audit was to assess the extent to which CSIRO has implemented the recommendations of the previous audit and of the JCPAA.
Entity
Commonwealth Scientific and Industrial Research Organisation
Performance audit (Auditor-General Report No. 12 of 2010–11)
Published: Friday 15 October 2010
Published
The objective of this audit was to assess key aspects of the establishment and administration of HIP by DEWHA as well as the transition of the program to DCCEE. All phases of the program were examined with particular emphasis for Phase 2 being given to:
- program design and implementation;
- registration and training of installers;
- payment of rebates; and
- the compliance strategy underpinning the program.
Entity
Department of Climate Change and Energy Efficiency; Department of the Environment, Water, Heritage and the Arts; Medicare Australia
Performance audit (Auditor-General Report No. 37 of 1998–99)
Published: Wednesday 5 May 1999
Published
The purpose of the report was to report to the Parliament on how effectively and efficiently the Australian Taxation Office administers the Tax File Number System, and to identify opportunities for improvement of that system. The ANAO developed a methodological framework for the evaluation of the efficiency and effectiveness of the ATO's administration of the TFN system. The framework examined the TFN system; individuals and their TFNs; TFN withholding tax arrangements; and TFN information matching.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 42 of 2009–10)
Published: Thursday 27 May 2010
Published
The objective of this audit was to assess key aspects of Australian Government agencies' fraud control arrangements to effectively prevent, detect and respond to fraud, as outlined in the Guidelines. The scope of the audit included 173 agencies subject to the FMA Act or the CAC Act.
Entity
Attorney-General's Department; Australian Institute of Criminology
Performance audit (Auditor-General Report No. 36 of 2006–07)
Published: Wednesday 16 May 2007
Published
The audit objectives were to examine if:
- DCITA had effectively planned and administered the HiBIS and BC Stage 1 programs; and
- the programs had achieved their objectives.
The audit focused on DCITA's activities to support the planning, implementation, monitoring and reporting of HiBIS and BC Stage 1 programs.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 33 of 2000–01)
Published: Monday 7 May 2001
Published
The objective of the ANAO audit was to identify possible areas for improvement in the Australian Defence Force's management of its Reserve forces. The audit focused on major aspects of the Reserves including roles and tasks, force structure, capability, training, individual readiness, equipment, facilities, recruitment, retention, conditions of service and administration. The audit covered the Australian Naval Reserve, the Australian Army Reserve and the Royal Australian Air Force Reserve. However, due to its size and cost, the Army Reserve was a major focus of the audit activity.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 47 of 2001–02)
Published: Tuesday 7 May 2002
Published
The 30 per cent Private Health Insurance Rebate is a financial incentive for individuals to purchase health insurance cover. The rebate provides for a reimbursement or discount of 30 per cent of the cost of private health insurance. It is available to all Australians who are eligible for Medicare and have private health insurance. The objective of the audit was to determine the effectiveness of Commonwealth Government agencies administration of the rebate.
Entity
Australian Taxation Office; Department of Finance and Administration; Department of Health and Aged Care; Department of the Treasury; Health Insurance Commission
Performance audit (Auditor-General Report No. 15 of 2007–08)
Published: Thursday 29 November 2007
Published
The objective of this follow-up audit is to assess the Tax Office's progress in implementing the recommendations of Audit Report No.59 2002–03, Administration of Australian Business Number Registrations, having regard to any changed circumstances, or new administrative issues, affecting the implementation of those recommendations.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 20 of 2005–06)
Published: Tuesday 6 December 2005
Published
The objective of this audit was to assess the Private Health Insurance Administration Council's (PHIAC's) administrative effectiveness as a regulator of private health insurance. In making this assessment, the Australian National Audit Office (ANAO) addressed the following criteria: whether PHIAC monitored compliance with its legislative requirements and analysed related data; whether PHIAC addressed and managed non-compliance with its legislative requirements; and whether PHIAC's governance and organisation supported the performance of its legislative functions. Although the Department of Health and Ageing (Health) also has a role in the regulation of the private health insurance industry under the National Health Act 1953 (Health Act), Health's regulatory activities were outside the scope of this audit.
Entity
Private Health Insurance Administration Council
Performance audit (Auditor-General Report No. 32 of 2003–04)
Published: Tuesday 2 March 2004
Published
The audit reviewed the Defence Materiel Organisation's management of the $3.43 billion Wedgetail Airborne Early Warning and Control (AEW&C) project. The Wedgetail project is to provide the Australian Defence Force with an AEW&C capability based on four Boeing 737 AEW&C aircraft and associated supplies and logistic support. At the time of the audit the AEW&C systems were still in their early development phase, and by November 2003, Defence had spent $1.107 billion on the project.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 23 of 2008–09)
Published: Wednesday 25 February 2009
Published
The audit focussed on performance information reporting by the submarine System Program Offices on reliability, safety systems and logistic support services. In the context of the sustainability arrangements, the audit considered combat system upgrades and personnel escape and rescue systems. Any arrangements that the Commonwealth may be considering regarding the potential sale of ASC were not within the scope of this audit.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 30 of 1999–2000)
Published: Thursday 3 February 2000
Published
The examined the $1 billion Federation Fund program, which was established by the Government to mark the Centenary of Federation. The objectives of the examination were to assess the:
- extent to which the administration of the FCHP program complied with better practice in the assessment of applications, especially in relation to the transparency and rigour of the decision-making process;
- equity of the geographic spread of grants to States and electorates; and
- process for the announcement of the results of grant applications.
Entity
Across Agency
Performance audit (Auditor-General Report No. 3 of 2007–08)
Published: Thursday 19 July 2007
Published
The audit objective was to form an opinion on the effectiveness of DEST's planning, assessment, and Funding Agreements management for the Australian Technical Colleges programme. At the time of the audit fieldwork (prior to the 2007–08 Budget) the Government had announced the establishment of 21 of the then target of 25 colleges. After fieldwork was completed the Government announced its intention to fund an additional three colleges in three new regions.
The criteria for this audit were designed to test whether DEST's management of the programme complied with its plans, procedures and guidelines, with the Act, and better practices for grants administration. For these purposes, the ANAO focused on DEST's:
- planning for the implementation of the programme;
- assessment of proposals to establish and operate the colleges; and
- management of the Funding Agreements.
Entity
Department of Education, Science and Training
Performance audit (Auditor-General Report No. 39 of 2009–10)
Published: Monday 24 May 2010
Published
The objective of this audit was to examine the effectiveness of Medicare Australia's administration of the PBS. In assessing the objective, the audit considered three key areas:
- Medicare Australia's relationship with the PBS policy agency (DoHA) and service delivery policy agency (Department of Human Services (DHS));
- the management arrangements and processes underpinning Medicare Australia's delivery of the PBS (including the means by which Medicare Australia gains assurance over the integrity of the PBS); and
- how Medicare Australia undertakes its three main responsibilities relating to the delivery of the PBS, namely: approving pharmacies; approving authority prescriptions; and processing PBS claims.
Entity
Medicare Australia; Department of Human Services; Department of Health and Ageing
Performance audit (Auditor-General Report No. 44 of 2002–03)
Published: Friday 23 May 2003
Published
The objective of the audit was to determine whether the controls and measures employed by FaCS and Centrelink to deliver Parenting Payment Single (PPS) payments were effective and efficient. To achieve this, the audit focused on four key areas. These were:
- the quality of performance measures used by FaCS and Centrelink;
- the effectiveness of FaCS' methodology for estimating the levels of risk of incorrect payment to PPS customers and the impact of these incorrect payments on the integrity of program outlays;
- the correctness of Centrelink's processing of reassessments; and
- the improvements to preventive controls such as training, guidance material, and the Quality On-Line system.
Entity
Department of Family and Community Services; Centrelink
Speeches and papers
Published: Thursday 14 February 2002
Published
Mr P.J. Barrett (AM) - Auditor-General for Australia, presented at the Global Working Group Meeting, Wellington, New Zealand
Performance audit (Auditor-General Report No. 7 of 2002–03)
Published: Monday 16 September 2002
Published
In 1997-98, the ANAO audited the Child Support Agency (CSA), making 12 recommendations to improve its operational performance. A related report by the Joint Committee of Public Accounts and Audit supported the general findings of the ANAO audit and reinforced three ANAO recommendations in its own report. The audit examined client service in the CSA by following-up the CSA's implementation of the recommendations contained in these two previous reports and more broadly assessing whether the CSA had improved the management and delivery of its client service sine the previous ANAO audit.
Entity
Department of Family and Community Services
Performance audit (Auditor-General Report No. 42 of 2005–06)
Published: Thursday 25 May 2006
Published
The follow-up audit assessed the extent to which the Australian Taxation Office (ATO), Department of Health and Ageing (Health), and Medicare Australia had implemented the six recommendations from Audit Report No.47 2001–02, Administration of the 30 Per Cent Private Health Insurance Rebate. The audit also looked at: the implementation of some of the major suggestions for improvement in the original audit; and the current validity of some of the positive major findings from that audit. The audit found that the ATO, Health and Medicare Australia have acted upon the recommendations contained in Audit Report No.47 2001–02 and, overall, the administration of the Rebate is currently being undertaken effectively.
Entity
Australian Taxation Office; Department of Health and Ageing; Medicare Australia
Performance audit (Auditor-General Report No. 40 of 2007–08)
Published: Wednesday 11 June 2008
Published
The objective of this audit was to assess the Tax Office's implementation of the nine recommendations of Audit Report No.19 2004–05 Taxpayers' Charter, having regard to any changed circumstances affecting the implementation of the recommendations. This involved an examination of the Tax Office's:
- systems and processes used to develop, maintain and update the Charter;
- strategic commitment to implementing the principles of the Charter;
- integration of Charter principles with its business processes;
- systems for resolving disputes according to Charter principles; and
- monitoring and reporting of its performance against commitments in the Charter.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 51 of 2000–01)
Published: Friday 15 June 2001
Published
This audit followed up the ANAO's 1997 performance audit report on ADF health services (Audit Report No.34 1996-97 Australian Defence Force Health Services), which focused on the delivery of non-operational health services to entitled members. The objective of the follow-up audit was to assess Defence's implementation of recommendations made in the original audit report and their effectiveness in improving ADF health services.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 27 of 2008–09)
Published: Friday 27 March 2009
Published
The objectives of this audit were to assess the progress of the M113 Armoured Personnel Carrier Upgrade Project against stated schedule, cost and technical performance objectives; and Defence Materiel Organisation's (DMO's) progress in implementing the recommendations and addressing the findings of ANAO Audit Report No. 3 2005–06, Management of the M113 Armoured Personnel Carrier Upgrade Project.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 52 of 2006–07)
Published: Thursday 28 June 2007
Published
This is the first of two audit reports concerning the Tax Office's administration of SMSFs pursuant to the provisions of the Superannuation Industry (Supervision) Act 1993.
This audit report examines the efficiency and effectiveness of the Tax Office's approach to regulating and registering self managed superannuation funds. Specifically the ANAO examined the:
- Environment in which SMSFs operate, including the Tax Office's regulatory roles and responsibilities;
- Tax Office's governance of its SMSF regulatory role; and
- Systems, processes and controls the Tax Office uses to register SMSFs, and enforce the lodgement of fund income tax and regulatory returns.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 40 of 2005–06)
Published: Wednesday 17 May 2006
Published
The objective of the audit was to examine processes used by Defence and the DMO to procure explosive ordnance for the ADF, with an emphasis on Army requirements. The audit reviewed the extent to which the DMO effectively translated the explosive ordnance requirements of the ADF, and particularly of Army, into procurement and through life support arrangements.
Entity
Department of Defence; Defence Materiel Organisation
Performance audit (Auditor-General Report No. 42 of 2006–07)
Published: Tuesday 12 June 2007
Published
The objective of the audit is to assess the effectiveness of the ATO's administration of debt collection. Micro-business debt is a particular focus of attention. The three key areas examined are:
- strategies–especially the ATO's initiatives trialled in 2006;
- infrastructure–the IT systems, people, policy and processes and risk management framework supporting the collection of debt; and
- management and governance–planning, monitoring and reporting mechanisms and liaison with stakeholders.
The ANAO focused on the work of the campaigns area within the Debt Line, which has collection responsibility for 90 per cent of collectable debt cases and responsibility for other key, centralised functions such as reporting, quality assurance review, consistency and best practice, and the debt collection initiatives.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 42 of 2000–01)
Published: Wednesday 30 May 2001
Published
The Australian Prudential Regulation Authority (APRA) was established on 1 July 1998 as the prudential regulator of banks and other authorised deposit-taking institutions (ADIs), life insurance companies (including friendly societies), general insurance companies, superannuation funds and retirement savings accounts. ANAO's objectives for this audit were to assess the efficiency and effectiveness of APRA's prudential supervision of banks. Prudential supervision aims to protect depositors by ensuring that financial institutions adopt prudent risk management practices designed to ensure their continuing solvency and liquidity. APRA is a relatively new organisation, established in July 1998 and becoming responsible for prudential supervision of all ADIs from July 1999. ANAO concluded that there are steps APRA can take in a number of areas to improve its supervisory practices, including improving the administration of the ADI supervisory levy; strengthening its risk management approach; and maintaining closer adherence to international standards for prudential supervision issued by the Basle Committee on Banking Supervision. ANAO made five recommendations concerning administration of levies, risk-based supervision and supervision of cross-border banking. APRA agreed, or agreed with qualifications, to all recommendations, as well as agreeing with the overall audit conclusions.
Entity
Australian Prudential Regulation Authority
Performance audit (Auditor-General Report No. 12 of 2007–08)
Published: Thursday 1 November 2007
Published
The objective of the audit was to assess the effectiveness of the Tax Office's compliance approach for high risk income tax refunds in the individuals and micro enterprises market segments. The audit examined three key areas:
management and organisational arrangements relating to high risk income tax refund processes;
processes and procedures for identifying high risk income tax refunds, and the processes and tools used to evaluate and verify taxpayers' entitlements to income tax refunds; and
information technology systems, processes and controls supporting the processing of income tax returns and refunds.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 30 of 2007–08)
Published: Thursday 24 April 2008
Published
The objective of the audit was to evaluate the Tax Office's corporate management of data matching, including analytics.
The ANAO examined the Tax Office's strategic goals and governance arrangements for data matching and analytics, its compliance with privacy requirements and whether the Tax Office is achieving intended results, which include revenue collection, optimised compliance and provision of improved services to taxpayers.
Tax Office executives have been increasingly drawing on the interrelationships and conceptual commonalities of Tax Office data matching and analytics activity. Accordingly, the audit included these relationships and conceptual commonalities within the scope of the audit. The audit was guided, therefore, by a broader definition of ‘data matching': meaning ‘finding relationships and patterns in large volumes of data'. This includes the more traditional idea of data matching as ‘bringing together data from different sources and comparing it'.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 36 of 1996–97)
Published: Thursday 5 June 1997
Published
The audit covered major program elements within the Department of Primary Industries and Energy and Environment Australia that are managed:
- directly by DPIE or Environment Australia;
- through the One-Stop-Shop project assessment process administered by the States/Territories; or
- by non-government organisations.
The purpose of the audit was to examine and benchmark the administrative processes established for these programs. The primary focus of the audit was to draw on the best elements of past practice (particularly in relation to programs involving the One-Stop-Shop) and highlight any shortcomings so that the risks to program effectiveness and accountability could be addressed in the implementation of the Natural Heritage Trust.
Entity
Across Agency
Performance audit (Auditor-General Report No. 9 of 2010–11)
Published: Wednesday 29 September 2010
Published
On 3 February 2010, Senator Christine Milne wrote to the Auditor General raising concerns about DEWHA's administration of the Green Loans program and requesting a performance audit of the program. Issues raised included: uncapped assessor numbers; problems with the delivery of the program; the quality of assessor training and assessments provided to households; the lack of an audit facility within the program; and equitable access to work under the program.
In light of Senator Milne's request and other concerns in relation to the administration of the program, the Auditor-General agreed on 25 February 2010 to conduct a performance audit of the program. The objective of the audit was to examine key aspects of the establishment and administration of the Green Loans program by DEWHA and the program's transition to DCCEE. Particular emphasis was given to the program's three main elements:
- training, registration and contracting of assessors;
- scheduling, conduct, and reporting of home sustainability assessments, and the associated payments to assessors; and
- provision of green loans to householders, and the associated payments to participating financial institutions.
The audit also examined the extent to which steps had been taken by DEWHA and DCCEE to assess whether the Green Loans program was achieving its objectives.
Entity
Department of the Environment, Water, Heritage and the Arts; Department of Climate Change and Energy Efficiency
Performance audit (Auditor-General Report No. 9 of 2003–04)
Published: Wednesday 22 October 2003
Published
The audit assessed whether Centrelink has effective Business Continuity Management and/or associated risk management procedures and plans in place that: minimise the likelihood of a significant business outage; and in the event of such an outage, minimise disruption of critical services to customers. The audit also assessed whether Centrelink services satisfy special community demands in times of emergency.
Entity
Centrelink
Performance audit (Auditor-General Report No. 20 of 2003–04)
Published: Friday 19 December 2003
Published
The objective of the audit was to assess the Australian Agency for International Development's (AusAid) planning for, and management of, the delivery of aid to East Timor. The audit examined Australia's emergency and humanitarian response following the crisis in East Timor in 1999; AusAID's post-crisis strategy for assisting East Timor; coordination with overseas donors; and financial contributions to multilateral reconstruction assistance. Australia's bilateral assistance, comprising shorter-term transitional assistance and medium-term development assistance, was also examined.
Entity
Australian Agency for International Development (AusAID)
Performance audit (Auditor-General Report No. 44 of 2001–02)
Published: Wednesday 24 April 2002
Published
The audit sought to assess the efficiency and effectiveness of the ADF's management of fuel and lubricants and to identify possible areas for improvement. The audit focused on major aspects of the fuel supply chain, in particular the strategic management of fuel (eg. the coordination of fuel requirements and stockholding policy). The audit also reviewed fuel procurement practices, storage and handling issues. The audit coverage addressed the fuel supply aspects of these matters rather than transport, distribution and equipment issues. Although directed principally towards operational fuels, the audit took into consideration issues associated with ADF's requirement for oils and lubricants.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 23 of 2006–07)
Published: Tuesday 6 February 2007
Published
The objective of the audit was to assess the application of the outcomes and outputs framework in Australian Government agencies. The audit included a review of:
- the outcomes and outputs of agencies and the integration of the outcomes and outputs framework into agencies' operations;
- the extent to which agencies' performance indicators incorporated better practice characteristics to enable agencies to meet their performance reporting obligations;
- agencies' processes for capturing, monitoring and reporting financial and performance information and the extent to which outcomes and outputs information was used in agency decision-making; and
- the extent that agencies met their external reporting and accountability obligations.
The audit consisted of a survey of 44 agencies subject to the Financial Management and Accountability Act 1997 (FMA Act) undertaken in October 2005 and detailed audit testing in three of those agencies. The purpose of the survey was to provide cross-agency data in relation to agencies' implementation of the framework during the period 2002–03 to 2005–06. The ANAO received responses from all 44 agencies, although not all agencies responded to all questions. The ANAO did not audit the information provided by survey participants and the reported results are based on agencies' responses to the survey.
The agencies at which detailed audit testing was undertaken were:
- Department of Education Science and Training;
- the then Department of the Environment and Heritage; and
- IP Australia.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 45 of 2009–10)
Published: Thursday 17 June 2010
Published
The objective of the audit was to assess whether Defence effectively managed the procurement process for services related to the recruitment of personnel to the ADF and the introduction of a new service provider.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 7 of 1998–99)
Published: Monday 7 September 1998
Published
The objective of the audit was to determine the extent to which the new employment services market had been implemented effectively and efficiently in accordance with announced Government policy and timeframe.
Entity
Department of Education, Training and Youth Affairs
Performance audit (Auditor-General Report No. 49 of 2009–10)
Published: Thursday 24 June 2010
Published
The objective of the audit was to assess whether Defence is effectively managing the delivery of health services to ADF personnel in Australia (chiefly Garrison Health Services).
Entity
Department of Defence
Performance audit (Auditor-General Report No. 4 of 2005–06)
Published: Thursday 4 August 2005
Published
The objectives of the audit were to assess the Commonwealth's management of contractual rights and obligations under the Sale Agreements. In particular the audit sought to: assess the Commonwealth's management of contractual warranties and indemnities; assess DoTARS' management of each purchaser's compliance with contractual commitments to capital expenditure; and examine the effectiveness of the development and management of contractual arrangements for concessional rail passenger travel provided by the Commonwealth.
Entity
Department of Transport and Regional Services; Department of Veterans’ Affairs; Department of Family and Community Services
Performance audit (Auditor-General Report No. 35 of 2005–06)
Published: Tuesday 28 March 2006
Published
The objective of the audit was to assess the ATO's administration of activity statement HRRs. Specifically the audit sought to: examine aspects of ATO governance relevant to its administration of activity statement HRRs. This includes: ATO planning, the integration between Lines to administer HRRs; corporate risk management processes; and performance management; assess the ATO's methodology and practice to identify and, if necessary, correct activity statement HRRs; and identify and assess the Information Technology (IT) and manual systems, processes and controls used by the ATO to process HRRs resulting from the lodgement of activity statements.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 25 of 2005–06)
Published: Tuesday 24 January 2006
Published
The audit objective was to examine the effectiveness and efficiency of ASIC's implementation of Australian financial services licences. In particular, the audit examined ASIC's planning for the introduction of financial services licences; the roles of the Department of the Treasury (Treasury) and ASIC in defining the effective scope of licensing; ASIC's assessment and processing of licence applications; and ASIC's supervision of licensees.
Entity
Australian Securities and Investment Commission
Performance audit (Auditor-General Report No. 40 of 2001–02)
Published: Monday 8 April 2002
Published
The audit was undertaken following advice from the Joint Committee of Public Accounts and Audit (JCPAA) to the Auditor-General that assurance that ABC programming adequately reflects the ABC's Charter was an audit priority of Parliament. The objective of the audit is to provide Parliament with this assurance. The focus of the audit was on the governance arrangements of the ABC Board and management that enable the ABC to demonstrate the extent to which it is achieving its' Charter obligations, and other related statutory requirements, efficiently and effectively. The scope of the audit was as follows:
- Review the ABC's corporate governance framework against better practice models. The ANAO had regard to the ABC's unique role as a national public broadcaster established as a budget funded Commonwealth statutory authority subject to the Commonwealth Authorities and Companies Act 1997.
- Examine the ABC Board's approach to the interpretation of the Charter requirements of the ABC and the setting of strategic directions, and management's administrative arrangements for implementing the strategic directions established by the Board.
- Examine the ABC's performance information framework, the development, documentation and use of performance measures in relation to targets and/or objectives, the monitoring and reporting of performance and its' inter-relationship with the corporate planning and budgetary processes, particularly in relation to the strategic directions set by the Board.
The audit did not examine the overall management of the ABC. In keeping with the audit scope, the audit examined ways in which the ABC aligns its' strategic directions with its' Charter requirements for programs broadcast on radio, television and on-line and assures itself, and Parliament, about the achievement of its' Charter obligations. Further, the audit did not examine the operations of ABC Enterprises or symphony orchestras that operate as ABC-owned subsidiary companies.
Entity
Australian Broadcasting Corporation
Performance audit (Auditor-General Report No. 3 of 2008–09)
Published: Tuesday 23 September 2008
Published
The objective of the audit was to assess the effectiveness of the management and administration of the Communications Fund, including an assessment of:
- the development and implementation of appropriate investment strategies; and
- the robustness of the governance structures and controls relating to investment activities.
Entity
Department of Broadband, Communications and the Digital Economy; Department of Finance and Deregulation
Performance audit (Auditor-General Report No. 41 of 2008–09)
Published: Wednesday 17 June 2009
Published
Given the significant expenditure associated with the Super Seasprites, and the problems that the Project had encountered over some time, the ANAO had commenced this performance audit prior to the Government's decision to cancel the Project. The focus of the audit was on Defence's and DMO's administration of the Project. In light of the Government's decision to cancel the Project, the objective of the audit was revised to place greater emphasis on those issues that resulted in the failure of the Project to provide the required capability, and highlighting project management lessons for major Defence acquisitions going forward.Accordingly the audit objective was to:
- identify those factors that contributed to the on-going poor performance of the Project;
- outline measures taken by Defence and DMO in seeking to overcome issues encountered by the Project, and key lessons arising from this project for the benefit of major acquisitions projects generally; and
- determine the capability and cost implications of a project that failed to deliver to expectations.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 47 of 2009–10)
Published: Wednesday 23 June 2010
Published
The audit objective was to examine how effectively the Department of Agriculture, Fisheries and Forestry (DAFF) manages the importation of live animals into Australia.
Entity
Department of Agriculture, Fisheries and Forestry
Performance audit (Auditor-General Report No. 39 of 2004–05)
Published: Wednesday 13 April 2005
Published
The objective of the audit was to assess the ATO's administration of the Surcharge. Specifically, the audit sought to: report on the environment into which the Surcharge was introduced, including the legislative intent behind the Surcharge, and the current Surcharge environment; examine and report on aspects of Surcharge governance; assess the systems, processes and controls the ATO uses to: match Member Contributions Statements (MCS) data with income tax return data using Tax File Numbers (TFNs); process Surcharge information; and issue Surcharge liability assessments. assess the mechanisms the ATO uses to assess, classify, manage and rectify existing Surcharge exceptions, and prevent future exceptions from occurring; and examine the mechanisms and strategies the ATO uses to provide assurance that members and holders of contributions are complying with their Surcharge obligations.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 3 of 2011–12)
Published: Tuesday 30 August 2011
Published
The objective of this audit is to examine the effectiveness of the TGA’s administration of complementary medicines regulation in Australia. The primary focus is on listed complementary medicines, which comprise about 98 per cent of these medicines.
Entity
Department of Health and Ageing
Major projects report (Auditor-General Report No. 12 of 2013–14)
Published: Tuesday 17 December 2013
Published
The objective of this report is to provide the Auditor-General’s independent assurance over the status of selected Major Projects, as reflected in the Project Data Summary Sheets (PDSSs) prepared by the DMO, and the Statement by the Chief Executive Officer (CEO) DMO. Assurance from the ANAO’s review of the preparation of the PDSSs by the Defence Materiel Organisation (DMO) is conveyed in the Auditor-General’s Independent Review Report, prepared pursuant to the endorsed Guidelines, contained in Part 3.
Entity
Defence Materiel Organisation
Contact
Michael White, Executive Director, Phone: (02) 6203 7393
Performance audit (Auditor-General Report No. 15 of 2000–01)
Published: Thursday 9 November 2000
Published
The objectives of the audit were to examine:
- the effectiveness of agencies' implementation of the current GBEs governance framework;
- the extent to which agencies and GBEs comply with the Governance Arrangements and legislative requirements; and
- whether the GBE monitoring system provides an effective level of accountability to Ministers and to the Parliament.
Entity
Across Agency
Performance audit (Auditor-General Report No. 53 of 2006–07)
Published: Friday 29 June 2007
Published
The objective of the audit is to examine and report on the efficiency and effectiveness of AFP's administration and management of its overseas deployments. The audit specifically examines two deployments and focuses on strategic and operational planning and logistics. The audit examines a planned, long-term overseas deployment (as part of the Participating Police Force (PPF) within the Regional Assistance Mission to Solomon Islands (RAMSI)) and a crisis-driven deployment in response to a specific event (Disaster Victim Identification (DVI) assistance to Thailand following the Indian Ocean Tsunamis of 26 December 2004).
Entity
Australian Federal Police
Performance audit (Auditor-General Report No. 5 of 2005–06)
Published: Thursday 11 August 2005
Published
The audit objective was to examine whether Health's financial management framework and processes adequately support Health's Secretary, Executive and managers to make informed decisions on the use of Commonwealth resources.
Entity
Department of Health and Ageing
Performance audit (Auditor-General Report No. 29 of 2008–09)
Published: Thursday 23 April 2009
Published
The objective of this performance audit of construction projects on the AusLink National Network was to assess the effectiveness of the administration by DITRDLG in working with the States to deliver the outcomes expected by the Government and the broader community. To inform the audit assessment, the methodology included examination of both Australian Government and State Government records as well as site inspections in relation to 21 projects being delivered in three States (New South Wales (NSW), Queensland and Tasmania). DITRDLG and the respective State road transport authorities were consulted in the selection of projects to be examined in detail.
Entity
Department of Infrastructure, Transport, Regional Development and Local Government
Performance audit (Auditor-General Report No. 57 of 2003–04)
Published: Thursday 24 June 2004
Published
The audit objectives were to assess: the appropriateness of agencies' policies for dealing with requests for information in accordance with the FOI Act; and assess agencies' compliance with the provisions of the FOI Act, in relation to selected requests for information.
Entity
Australian Federal Police; Attorney-General’s Department; Department of Communications, Information Technology and the Arts; Department of Veterans’ Affairs; Australian Customs Service; Civil Aviation Safety Authority
Performance audit (Auditor-General Report No. 2 of 2013–14)
Published: Wednesday 14 August 2013
Published
The objective of the audit was to assess the effectiveness of the administration, by DoHA and the Commonwealth partners, of the 2008 and 2011 Heads of Agreement for the management, operation and funding of the Mersey Community Hospital (The Commonwealth partners for this audit were the Tasmanian Government Department of Health and Human Services and the Tasmanian Health Organisation – North West).
Entity
Department of Health and Ageing; Department of Health and Human Services, Tasmania; Tasmanian Health Organisation, North West
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 45 of 2006–07)
Published: Tuesday 19 June 2007
Published
The objective of this performance audit was to assess the administration of the National Black Spot Programme. It was undertaken in a manner similar to the audit of the Roads to Recovery Programme. Specifically, the audit approach involved:
- examination of DOTARS records and discussions with officers in DOTARS and four of the State road transport authorities responsible for administering the Programme;
- analysis of project monitoring, reporting and payment arrangements; and
- selecting a sample of 45 LGA areas across four States so that ANAO could examine projects delivered with Commonwealth funding.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 23 of 2001–02)
Published: Friday 7 December 2001
Published
The audit reviewed the broadcasting planning and licensing operations of the Australian Broadcasting Authority, which is responsible for planning the availability of segments of the broadcasting services bands used by radio and television for analogue and digital broadcasting. The objective was to assess the ABA's management of licence area planning and the subsequent issue of broadcasting licences, focussing on analogue radio planning and identifying improved administrative practices, where possible, together with the main factors that have contributed to the delays to date in achieving the planning timetable.
Entity
Australian Broadcasting Authority