Browse our range of reports and publications including performance and financial statement audit reports, assurance review reports, information reports and annual reports.
Performance audit (Auditor-General Report No. 27 of 2002–03)
Published: Thursday 30 January 2003
Published
The audit reviewed the management and recording of guarentees, warranties, indemnities and letters of comfort issued by the Commonwealth and also assessed action taken in the relation to the recommendations from ANAO Audit Report No. 47 1997-98. The objectives of the audit were to assess the extent of:
- improvement in agencies' management and monitoring of the Commonwealth's exposure to these instruments;
- changes in the size and nature of the exposure since 30 June 1997; and
- the approach of agencies to effective risk management and control of Commonwealth exposures to these instruments.
Entity
Across Agency
Performance audit (Auditor-General Report No. 21 of 2006–07)
Published: Wednesday 31 January 2007
Published
The objective of the audit was to:
- assess, in a selection of FMA Act and CAC Act agencies, how well the revised Commonwealth Procurement Guidelines had been implemented; and
- identify any better practice or common problem areas to assist other agencies in their future procurement activities.
The audit focused on procurement requirements that had changed as a result of the revised CPGs, rather than being a more general audit of compliance with all procurement requirements.
The audit was conducted in the following entities:
- Australian Federal Police;
- Bureau of Meteorology;
- Commonwealth Scientific and Industrial Research Organisation (CSIRO);
- Department of Defence;
- Department of Education, Science & Training;
- Family Court of Australia; and
- National Museum of Australia.
Entity
NO-DEPTS-LISTED
Financial statement audit (Auditor-General Report No. 47 of 2017–18)
Published: Thursday 14 June 2018
Published
The Australian National Audit Office (ANAO) publishes two reports annually addressing the outcomes of the financial statement audits of Australian government entities and the Consolidated Financial Statements (CFS) of the Australian Government, to provide the Parliament of Australia with an independent examination of the financial accounting and reporting of public sector entities. This report focused on the results of the interim audit phase, including an assessment of entities’ key internal controls, of the 2017–18 financial statements audits of a range of entities including all departments of state and a number of major Australian government entities.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 18 of 2003–04)
Published: Wednesday 10 December 2003
Published
The Australian National Audit Office (ANAO) completed a performance audit of the ATO's use of AUSTRAC data in August 2000, titled The AustralianTaxation Office's Use of AUSTRAC Data, Audit Report No. 7 2000-2001. It found that the ATO had used AUSTRAC data to achieve a significant improvement in the collection of taxation revenue. The ANAO considered that the ATO could build on this success by using AUSTRAC data more effectively at both the strategic and operational levels. The audit made six recommendations. The ATO agreed with all recommendations. The objective of this follow-up performance audit was to assess the ATO's progress in implementing the recommendations of Audit Report No 7 2000-2001, The Australian Taxation Office's Use of AUSTRAC Data.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 35 of 2000–01)
Published: Thursday 17 May 2001
Published
Family and Community Services' Oversight of Centrelink's Assesment of New Claims for the Age Pension
The objective of the audit was to assess whether FaCS had established effective business arrangements with Centrelink to help ensure that new claims for Age Pension were properly assessed in accordance with the Social Security Law and the Guide to the Social Security Law. In the context of the audit objective, the primary issues examined were whether FaCS had:
- established an appropriate business framework;
- adopted an appropriate risk management approach;
- appropriately monitored and evaluated performance; and
- provided relevant business support to Centrelink.
Entity
Department of Family and Community Services
Performance audit (Auditor-General Report No. 21 of 1997–98)
Published: Thursday 4 December 1997
Published
The main objectives of the audit were to assess the management and administration of protective security across Commonwealth agencies and to identify, recommend and report better practice in security management. Particular attention was paid to:
- compliance with Government policy, standards and guidelines;
- the role of management in protective security; and
- the operation of security systems and practices.
The audit criteria and procedures to assess the management and administration of the individual organisations examined were largely based on the overall control framework of an organisation and the guidance provided in the current Commonwealth Protective Security Manual.
Entity
Across Agency
Performance audit (Auditor-General Report No. 34 of 2016–17)
Published: Tuesday 24 January 2017
Published
The objective of this audit was to assess the effectiveness of the Department of Agriculture and Water Resources' implementation of the new biosecurity legislative framework.
Entity
Department of Agriculture and Water Resources
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 25 of 2014–15)
Published: Thursday 5 March 2015
Published
The audit objective was to assess the effectiveness of the development and administration of the Fifth Community Pharmacy Agreement (5CPA), and the extent to which the 5CPA has met its objectives.
Entity
Department of Health; Department of Human Services; Department of Veterans' Affairs
Contact
Please direct enquiries relating to reports through our contact page.
Financial statement audit (Auditor-General Report No. 17 of 2009–10)
Published: Thursday 17 December 2009
Published
Financial statement audits are an independent examination of the financial accounting and reporting of public sector entities. The results of the examination are presented in an audit report, which expresses the auditor's opinion on whether the financial statements as a whole and the information contained therein fairly present each entity's financial position and the results of its operations and cash flows. The accounting treatments and disclosures reflected in the financial statements by the entity are assessed against relevant accounting standards and legislative reporting requirements.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 63 of 2002–03)
Published: Monday 30 June 2003
Published
The objective of the audit was to assess the Commonwealth's administration of the Automotive Competitiveness and Investment Scheme (ACIS) . The audit reviewed program governance, scheme promotion and registration, management of credit allocations, and compliance processes.
Entity
Department of Industry Tourism and Resources; Australian Customs Service
Performance audit (Auditor-General Report No. 38 of 1996–97)
Published: Tuesday 24 June 1997
Published
The objective of this audit was to assess the effectiveness of the action taken by the Australian Institute of Marine Science in response to the recommendations contained in 'External Funds Generation', Audit Report No.48, 1991-92.
Entity
Australian Institute of Marine Science
Financial statement audit (Auditor-General Report No. 38 of 2019–20)
Published: Thursday 28 May 2020
Published
This report focuses on the results of the interim financial statements audits, including an assessment of entities’ key internal controls, supporting the 2019–20 financial statements audits. This report examines 24 entities, including all departments of state and a number of major Australian government entities. The entities included in the report are selected on the basis of their contribution to the income, expenses, assets and liabilities of the 2018–19 Consolidated Financial Statements (CFS). Significant and moderate findings arising from the interim audits are reported to the responsible Minister(s), and all findings are reported to those charged with governance of each entity.
Contact
Please direct enquiries through our contact page.
Financial statement audit (Auditor-General Report No. 46 of 2018–19)
Published: Thursday 13 June 2019
Published
This report focuses on the results of the interim audits, including an assessment of entities’ key internal controls, supporting the 2018–19 financial statements audits. It examines 26 entities, including all departments of state and a number of major Australian government entities. The entities included in the report are selected on the basis of their contribution to the income, expenses, assets and liabilities of the 2017–18 Consolidated Financial Statements of the Australian Government (CFS). Significant and moderate findings arising from the interim audits are reported to the responsible Minister(s), and all findings are reported to those charged with governance of each entity.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Financial statement audit (Auditor-General Report No. 7 of 2016–17)
Published: Wednesday 31 August 2016
Published
The Australian National Audit Office (ANAO) publishes two reports annually addressing the outcomes of the financial statement audits of Commonwealth entities, and the Consolidated Financial Statements of the Australian Government, to provide Parliament an independent examination of the financial accounting and reporting of public sector entities. This report focuses on the results of the interim audit phase, including an assessment of entities’ key internal controls, of the 2015–16 financial statements audits of 21 departments and other major General Government Sector (GGS) entities. These entities contribute 95 per cent of GGS revenues and expenses.
Entity
Across Entities
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 19 of 2010–11)
Published: Thursday 9 December 2010
Published
The audit assessed FaHCSIA's management of AACAP and how the department monitors the contribution the program is making to the improvement of primary and environmental health, and living conditions, in remote Indigenous communities.
The audit examined program delivery under the 2006–2009 MoU, as well as the planning for the 2010 project under the variation to the 2006–2009 MoU. As part of the audit the ANAO considered:
- program strategy and implementation including the roles and responsibilities of the major stakeholders, community selection and scope of works (Chapter 2);
- the financial management of the program and the changing role of the Contracted Program Manager (Chapter 3); and
- performance measures, including FaHCSIA's performance reporting framework, and approach to monitoring and reporting performance against the stated program objectives (Chapter 4).
The audit focused on AACAP in so far as it relates to Indigenous community outcomes. It did not consider the program from the perspective of the Australian Defence Force capability building.
Entity
Department of Families, Housing, Community Services and Indigenous Affairs
Request for audit
Responded: Tuesday 19 September 2017
Response provided
The Auditor-General responded on 19 September 2017 to correspondence from Mr Stephen Jones MP dated 6 September 2017, requesting that the Auditor-General undertake an independent assessment of the project funding provided to Central Coast Group Training Ltd (CCGT) for the Central Coast Youth Skills and Employment Centres, and the administration of the Community Development Grants Program.
Contact
Please direct enquiries relating to requests for audit through our contact page.
Performance audit (Auditor-General Report No. 49 of 1998–99)
Published: Tuesday 29 June 1999
Published
The objective was to assess the extent to which staff reductions have been managed in a sound strategic and cost-effective manner consistent with the Government's guidelines and the ANAO's 1996 better practice guide Managing APS Staff Reductions. The audit focussed on 3 agencies - the Australian Taxation Office, the former Department of Primary Industry and Energy, and the former Department of Transport and Regional Development. The ANAO found that the majority of staff reductions were achieved through retrenchment rather than natural attrition; and that decisions on the number of retrenchments were not always supported by an assessment of the impact of the reductions on the agencies' abilities to conduct their business.
Entity
Public Service and Merit Protection Commission and Other Agencies
Performance audit (Auditor-General Report No. 26 of 1996–97)
Published: Tuesday 11 February 1997
Published
The objective of Phase Two of the audit was to examine the efficiency and effectiveness of operations of ATSIC Central, State and Regional Offices in relation to the administration of the Community Development Employment Projects Scheme. The ANAO established key criteria to assess progress against the implementation of the Phase One recommendations and further assess the efficiency and effectiveness of CDEP administration. The main areas examined were: planning, including reports of progress against plans and the development and use of performance information; monitoring, including client feedback and the review process at the Regional Office level; the implementation and effectiveness of management information systems in relation to CDEP; and the development and implementation of quality assuranced processes at State/Regional level.
Entity
Aboriginal and Torres Strait Islander Commission
Performance audit (Auditor-General Report No. 59 of 2001–02)
Published: Thursday 20 June 2002
Published
The overall objective of the audit was to assess AusAID's management of commercial contracts to deliver Australia's overseas aid program. To this end, the audit examined whether:
- there are sound supporting structures for contract management;
- AusAid effectively manages risks;
- contracts clearly define deliverables;
- services are delivered and payments are made in accordance with the contract;
- there are appropriate arrangements to manage contractor performance;
- strategies appropriately assess and allocate risk between AusAid and contractors; and
- contracts deliver the desired aid outcomes.
Entity
Australian Agency for International Development (AusAID)
Performance audit (Auditor-General Report No. 35 of 2003–04)
Published: Wednesday 24 March 2004
Published
This report covers a number of the discretionary compensation and debt relief mechanisms that are available to Commonwealth agencies, where individuals or entities have been disadvantaged by legislation, or actions by agencies or staff, or some other negative circumstances. It deals mainly with two legislative mechanisms, namely, act of grace payments and waivers of debt, and one administrative mechanism, the Compensation for Detriment caused by Defective Administration (CDDA) scheme. This report also briefly covers two other mechanisms, namely ex gratia payments and payments in special circumstances relating to Australian Public Service (APS) employment. The main objective of the audit was to assess whether the management of claims for compensation and debt relief in special circumstances was in accordance with relevant legislative requirements and Commonwealth guidelines, and whether the current administrative policies and procedures were adequate.
Entity
Across Agency
Financial statement audit (Auditor-General Report No. 54 of 2010–11)
Published: Thursday 23 June 2011
Published
The Auditor-General Act 1997 establishes the mandate for the Auditor-General to undertake financial statement audits of all Australian Government entities including those of government agencies, statutory authorities and government business enterprises.
Our interim audits of agencies encompass a review of governance arrangements related to agencies’ financial reporting responsibilities, and an examination of relevant internal controls, including information technology system controls. The ANAO’s examination of these areas is designed to assess the reliance that can be placed on agencies’ internal controls to produce complete and accurate information for financial reporting purposes.
Entity
Across Entities
Performance audit (Auditor-General Report No. 13 of 2010–11)
Published: Thursday 28 October 2010
Published
The Civil Aviation Safety Authority (CASA) is responsible for regulating aviation safety in Australia, the safety of Australian aircraft operating overseas as well as for regulating and administering Australia's airspace. In September 2008, the Senate Committee on Rural and Regional Affairs and Transport presented a report on the Administration of the Civil Aviation Safety Authority and related matters. That report made three recommendations, one of which requested an Australian National Audit Office (ANAO) audit of CASA's implementation and administration of the regulation of aircraft operators' Safety Management Systems (SMS'). ANAO agreed to this request with the objective of the audit being to assess CASA's implementation and administration of an SMS approach to regulating aircraft operators.
An SMS is a systematic approach to managing safety, which encompasses organisational structures, accountabilities, policies and procedures. Amendments to the Convention on International Civil Aviation (commonly referred to as the Chicago Convention) made in 2006 require that contracting states regulate the SMS' of aircraft operators. As a contracting state to the Chicago Convention, Australia is required to mandate that aircraft operators implement an SMS.
Entity
Civil Aviation Safety Authority
Financial statement audit (Auditor-General Report No. 60 of 2016–17)
Published: Wednesday 28 June 2017
Published
The Australian National Audit Office (ANAO) publishes two reports annually addressing the outcomes of the financial statement audits of Australian government entities and the Consolidated Financial Statements (CFS) of the Australian Government to provide Parliament an independent examination of the financial accounting and reporting of public sector entities. This report focuses on the results of the interim audit phase, including an assessment of entities’ key internal controls, of the 2016–17 financial statements audits of 25 entities including all departments of state and a number of major Australian government entities.
Entity
Across Entities
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 10 of 1995–96)
Published: Thursday 23 November 1995
Published
The ANAO's objective in auditing the sale was to assess:
- the extent to which the Commonwealth's objectives were achieved; and
- the efficiency, administrative effectiveness and accountability of the sale process.
Entity
Across Agency
Performance audit (Auditor-General Report No. 10 of 2000–01)
Published: Friday 15 September 2000
Published
The objective of the audit was to assess the efficiency and effectiveness of the management of AQIS cost-recovery systems and provide assurance to the Parliament that the cost-recoverable programs are identifying and recovering the full costs of services provided, without cross-subsidisation.
Entity
Australian Quarantine and Inspection Service
Performance audit (Auditor-General Report No. 21 of 2010–11)
Published: Wednesday 15 December 2010
Published
The objective of the audit was to assess the effectiveness of FaHCSIA's management of the Fixing Houses for Better Health program since 2005.
The audit reviewed the two elements of the program for which FaHCSIA is responsible: management of the service delivery arrangements and overall performance monitoring and reporting. Following the development of the National Partnership Agreement on Remote Indigenous Housing, which introduced new approaches to the delivery of Indigenous programs, FaHCSIA made changes to FHBH for the 2009–11 phase. The audit has focused on both the 2005–09 and the 2009–11 phases. This provided coverage of the program's normal operations as well enabling the audit to consider the modifications made to the program for the
2009–11 phase.
Against this background, the audit considered whether:
- program management arrangements had been established that were suitable for the size, nature and objectives of the FHBH program;
- service delivery arrangements were designed to support the achievement of the program's objectives and FaHCSIA's management of the program; and
- FaHCSIA used robust systems to monitor achievement of the program objectives.
The ANAO also considered whether there was any experience from the department's management of FHBH that could be broadly applied to FaHCSIA's management of the National Partnership Agreement.
Entity
Department of Families, Housing, Community Services and Indigenous Affairs
Performance audit (Auditor-General Report No. 11 of 2010–11)
Published: Thursday 30 September 2010
Published
The objective of the audit was to assess how well agencies had implemented the CPGs and relevant FMA legislation when undertaking Direct Source procurement.
The audit examined whether selected agencies had developed a sound procurement framework; appropriately classified procurement methods when meeting external reporting requirements; implemented the CPGs and relevant legislation when Direct Sourcing; and established effective procurement monitoring and review arrangements.
The ANAO selected four FMA Act agencies to provide a cross-section of the 104 agencies that reported procurement activity in AusTender in
2008–09. The agencies selected for audit were:
- the Department of Families, Housing, Community Services and Indigenous Affairs (FaHCSIA);
- the Department of Innovation, Industry, Science and Research (Innovation);
- the Department of Veterans' Affairs (DVA); and
- the Australian Crime Commission (ACC).
The ANAO examined a stratified random sample of 645 procurements valued at $10 000 and over, across the four agencies. More detailed testing was undertaken for the 285 Direct Source procurements in the sample.
Entity
Across Agencies
Performance audit (Auditor-General Report No. 27 of 1996–97)
Published: Wednesday 5 March 1997
Published
The objective of the audit was to assess the effectiveness and efficiency of Army's management of the move of 1st Brigade to Darwin. The audit criteria directly related to implementation of the project. These criteria addressed planning as well as identification and management of longer-term risks to the success of the project.
Entity
Department of Defence
Performance audit in-progress
Due to table: March 2027
Open for contribution
The objective of this audit is to assess the efficiency of the Department of Finance’s management of the Comcover insurance fund.
Entity
Department of Finance
Contact
Please direct enquiries through our contact page.
Performance audit in-progress
Due to table: May 2027
Open for contribution
The objective of this audit is to assess the effectiveness of the management of investments for the Rewiring the Nation (RTN) fund.
Entity
Department of Climate Change, Energy, the Environment and Water; Clean Energy Finance Corporation
Contact
Please direct enquiries through our contact page.
Financial statement audit (Auditor-General Report No. 42 of 2008–09)
Published: Monday 22 June 2009
Published
Under section 57 of the Financial Management and Accountability Act 1997 (FMA Act) the Auditor-General is required to report each year to the relevant Minister, on whether the financial statements of agencies have been prepared in accordance with the Finance Minister's Orders (FMOs) and whether they give a true and fair view of the matters required by those Orders.
Our interim audits of agencies encompass a review of governance arrangements related to agencies' financial reporting responsibilities, and an examination of relevant internal controls, including information technology system controls. An examination of such issues is designed to assess the reliance that can be placed on internal controls to produce complete and accurate information for financial reporting purposes.
Entity
Across Agencies
Performance audit (Auditor-General Report No. 34 of 2002–03)
Published: Monday 24 March 2003
Published
This audit followed up the ANAO's 1999 performance audit report on the Commonwealth's planning and response mechanisms to deal with exotic and new endemic pest and emergencies in the animal and plant sectors (Audit Report No 9 1999-2000 Managing Pest and Disease Emergencies). The previous audit made nine recommendations to improve planning and response strategies for emergencies; better coordination; diagnostic support; and appropriate monitoring and surveillance. The objective of the follow-up audit was to assess AFFA's implementation of the recommendations, and whether implementation of these recommendations, or appropriate alternative measures, has improved the Commonwealth's planning and response strategies for pest and disease emergencies. The ANAO also observed and assessed relevant parts of the September 2002 foot and mouth disease simulation, Exercise Minotaur.
Entity
Agriculture Fisheries and Forestry - Australia Department of Agriculture
Performance audit (Auditor-General Report No. 15 of 1996–97)
Published: Monday 25 November 1996
Published
The objective of the audit was to assess the efficiency and effectiveness of administrative arrangements for the provision of food to the Australian Defence Force and identify possible areas for improvement. The audit criteria addressed the adequacy of policy guidance, planning, performance information and risk management in all areas of ADF food provisioning.
Entity
Across Agency
Performance audit in-progress
Due to table: December 2026
Report preparation
The objective of this audit is to assess the effectiveness of the Department of Veterans’ Affairs’ (DVA’s) management of the compensation claims.
Entity
Department of Veterans' Affairs
Contact
Please direct enquiries through our contact page.
Performance audit in-progress
Due to table: February 2027
Report preparation
The objective of this audit is to assess the effectiveness of Services Australia’s management of Centrelink automated decision-making.
Entity
Services Australia
Contact
Please direct enquiries through our contact page.
Potential topic
Potential topic: 2026-27
Potential
The ANAO could assess the effectiveness of the design and delivery of the Leaving Violence Program national program.
Entity
Department of Social Services
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 17 of 2002–03)
Published: Tuesday 5 November 2002
Published
The objective of the audit was to assess whether the controls employed by the Department of Family and Community Services (FACS) and Centrelink to ensure the correctness of payments made under the Age Pension program were effective and efficient. The ANAO focused on:
- business arrangements between FACS and Centrelink and the Business Assurance Framework;
- whether the source of error was correctly attributed in customer records assessed by FACS and Centrelink as containing an error in the 2000-01 Age Pension Random Sample Survey:
- the correctness of Centrelink's processing of reassessments, including Pensioner Entitlements Reviews, Customer Initiated Reassessments and automated reassessments: and
- progress in implementing the recommendations of previous ANAO audits concerning the preventive quality controls that underpin correct payments.
Entity
Department of Family and Community Services; Centrelink
Financial statement audit (Auditor-General Report No. 56 of 2004–05)
Published: Friday 24 June 2005
Published
This report presents the results of the interim phase of the 2004-2005 financial statement audits. The audits have encompassed a review of governance arrangements related to entities' financial management responsibilities, and an examination of internal control, including information technology system controls for all portfolio departments and other major General Government Sector entities as at 31 March 2005. An examination of such issues is designed to assess the reliance that can be placed on internal controls to produce complete and accurate information for financial reporting purposes. All ANAO findings have been reported to entities and summary reports provided to the relevant Minister(s).
Entity
Across Agency
Performance audit (Auditor-General Report No. 23 of 2006–07)
Published: Tuesday 6 February 2007
Published
The objective of the audit was to assess the application of the outcomes and outputs framework in Australian Government agencies. The audit included a review of:
- the outcomes and outputs of agencies and the integration of the outcomes and outputs framework into agencies' operations;
- the extent to which agencies' performance indicators incorporated better practice characteristics to enable agencies to meet their performance reporting obligations;
- agencies' processes for capturing, monitoring and reporting financial and performance information and the extent to which outcomes and outputs information was used in agency decision-making; and
- the extent that agencies met their external reporting and accountability obligations.
The audit consisted of a survey of 44 agencies subject to the Financial Management and Accountability Act 1997 (FMA Act) undertaken in October 2005 and detailed audit testing in three of those agencies. The purpose of the survey was to provide cross-agency data in relation to agencies' implementation of the framework during the period 2002–03 to 2005–06. The ANAO received responses from all 44 agencies, although not all agencies responded to all questions. The ANAO did not audit the information provided by survey participants and the reported results are based on agencies' responses to the survey.
The agencies at which detailed audit testing was undertaken were:
- Department of Education Science and Training;
- the then Department of the Environment and Heritage; and
- IP Australia.
Entity
NO-DEPTS-LISTED
Performance audit in-progress
Due to table: March 2027
Report preparation
The objective of this audit is to assess the effectiveness of the Department of Finance’s (Finance) administration of the Digital ID Program (program).
Entity
Department of Finance
Contact
Please direct enquiries through our contact page.
Performance audit in-progress
Due to table: February 2027
Open for contribution
The objective of this audit is to assess whether there are effective arrangements to manage the delivery risks to the Inland Rail project.
Entity
Australian Rail Track Corporation
Contact
Please direct enquiries through our contact page.
Performance audit in-progress
Due to table: January 2027
Report preparation
The objective of this audit is to assess the effectiveness of the Department of the Treasury’s (Treasury) stewardship of the Federation Funding Agreement framework.
Entity
Department of the Treasury
Contact
Please direct enquiries through our contact page.
Financial statement audit (Auditor-General Report No. 42 of 2023–24)
Published: Thursday 20 June 2024
Published
The ANAO prepares two reports annually that provide insights at a point in time to the financial statements risks, governance arrangements and internal control frameworks of Commonwealth entities, drawing on information collected during our audits.
This report is the first of the two reports and focuses on the results of the interim financial statements audits, including an assessment of entities’ key internal controls, supporting the 2023–24 financial statements audits. This report examines 27 entities, including all: departments of state; the Department of Parliamentary Services; and other Commonwealth entities that significantly contribute to the revenues, expenses, assets and liabilities within the 2022–23 Australian Government Consolidated Financial Statements (CFS). The National Indigenous Australians Agency is also included in this report given the role it plays working across government with indigenous communities and stakeholders.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Financial statement audit (Auditor-General Report No. 39 of 2024–25)
Published: Thursday 29 May 2025
Published
The ANAO prepares two reports annually that provide insights at a point in time to the financial statements risks, governance arrangements and internal control frameworks of Commonwealth entities, drawing on information collected during our audits.
This report is the first of the two reports and focuses on the results of the interim financial statements audits, including an assessment of entities’ key internal controls, supporting the 2024–25 financial statements audits. This report examines 27 of the largest Australian Government entities, including all: departments of state; the Department of Parliamentary Services; and other Commonwealth entities that significantly contribute to the revenues, expenses, assets and liabilities within the 2023–24 Australian Government Consolidated Financial Statements (CFS). The National Indigenous Australians Agency is also included in this report given the role it plays working across government with indigenous communities and stakeholders.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Potential topic
Potential topic: 2026-27
Potential
The ANAO could assess the design and delivery of the cheaper home batteries program. The program commenced in July 2025 with a budget of $2.3 billion. In December 2025 the government increased the program budget to $7.2 billion due to higher than expected demand. The audit could consider the advice used during policy development, including any assessment of likely demand.
Entity
Department of Climate Change, Energy, the Environment and Water; Clean Energy Regulator
Contact
Please direct enquiries through our contact page.
Performance audit in-progress
Due to table: November 2026
Report preparation
The objective of this audit is to assess the effectiveness of Services Australia’s use of its enforcement powers for child support debt.
Entity
Services Australia
Contact
Please direct enquiries through our contact page.
Performance audit in-progress
Due to table: November 2026
Report preparation
The objective of this audit is to assess whether strategic coordination of market stewardship activities in the care and support economy is effective.
Entity
Department of the Prime Minister and Cabinet; Australian Public Service Commission; Department of Education; Department of Health, Disability and Ageing; National Disability Insurance Agency
Contact
Please direct enquiries through our contact page.
Financial statement audit (Auditor-General Report No. 42 of 2025–26)
Published: Thursday 25 June 2026
Published
The ANAO prepares two reports annually that provide insights at a point in time to the financial statements risks, governance arrangements and internal control frameworks of Commonwealth entities, drawing on information collected during our audits.
This report is the first of the two reports and focuses on the results of the interim financial statements audits, including an assessment of entities’ key internal controls, supporting the 2025–26 financial statements audits. This report examines 27 of the largest Australian Government entities, including all: departments of state; the Department of Parliamentary Services; and other Commonwealth entities that significantly contribute to the revenues, expenses, assets and liabilities within the 2024–25 Australian Government Consolidated Financial Statements (CFS). The National Indigenous Australians Agency is also included in this report given the role it plays working across government with indigenous communities and stakeholders.
Entity
Across Entities
Contact
Please direct enquiries through our contact page.
Performance audit in-progress
Due to table: March 2027
Open for contribution
The objective of this audit is to assess the effectiveness of the Australian Taxation Office’s (ATO) regulation of self-managed superannuation funds (SMSFs).
Entity
Australian Taxation Office
Contact
Please direct enquiries through our contact page.
Performance audit in-progress
Due to table: May 2027
Open for contribution
The objective of this audit is to assess whether the Australian Taxation Office’s (ATO) Personal Income Tax Compliance Program is efficient.
Entity
Australian Taxation Office
Contact
Please direct enquiries through our contact page.
Performance audit in-progress
Due to table: August 2027
Open for contribution
The objective of this audit is to assess the effectiveness of the Department of Defence’s (Defence) acquisition of the MQ-4C Triton unmanned aircraft system.
Entity
Department of Defence
Contact
Please direct enquiries through our contact page.
Performance audit in-progress
Due to table: February 2027
Report preparation
The objective of this audit is to assess the effectiveness of the Department of Education’s (Education) delivery of agreements under the Federation Funding Agreements framework.
Entity
Department of Education
Contact
Please direct enquiries through our contact page.
Performance audit in-progress
Due to table: May 2027
Open for contribution
The objective of this audit is to assess the effectiveness of the Department of Defence’s (Defence) development and delivery of the MQ-28A Ghost Bat capability.
Entity
Department of Defence
Contact
Please direct enquiries through our contact page.
Performance audit in-progress
Due to table: April 2027
Open for contribution
The objective of this audit is to assess the effectiveness of the Department of Defence’s (Defence) delivery of the Enhanced Defence High Frequency Communications System.
Entity
Department of Defence
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 28 of 1995–96)
Published: Tuesday 18 June 1996
Published
The objective of the audit was to assess the performance of the Department's management of the project in the light of accepted project management techniques, including risk management. An important part of the audit was to derive lessons to be learnt and recommendations that could be applied to the remainder of the project and to other large Defence projects.
Entity
Department of Defence
Insights: Audit lessons
Published: Monday 16 October 2023
Published
The aim of Insights: Audit Lessons (formerly Audit Insights) is to communicate lessons from our audit work and to make it easier for people working within the Australian public sector to apply those lessons.
This edition of Insights: Audit Lessons is targeted at Australian Government officials who are working in governance roles or who have responsibility for ensuring effective oversight and management of probity. Although it is based on audits of financial regulators, the lessons for managing probity risks can be applied across the public sector.
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 58 of 2001–02)
Published: Monday 17 June 2002
Published
The audit sought to assess the efficiency of Defence property management; provide assurance that probity and compliance requirements are being met; and make practical recommendations for enhancing property operations. It focused on Infrastructure Division's property management, with recognition that other areas manage certain property service contracts, such as those for electricity supply and cleaning.
Entity
Department of Defence
Performance audit (Auditor-General Report No. 21 of 2016–17)
Published: Monday 17 October 2016
Published
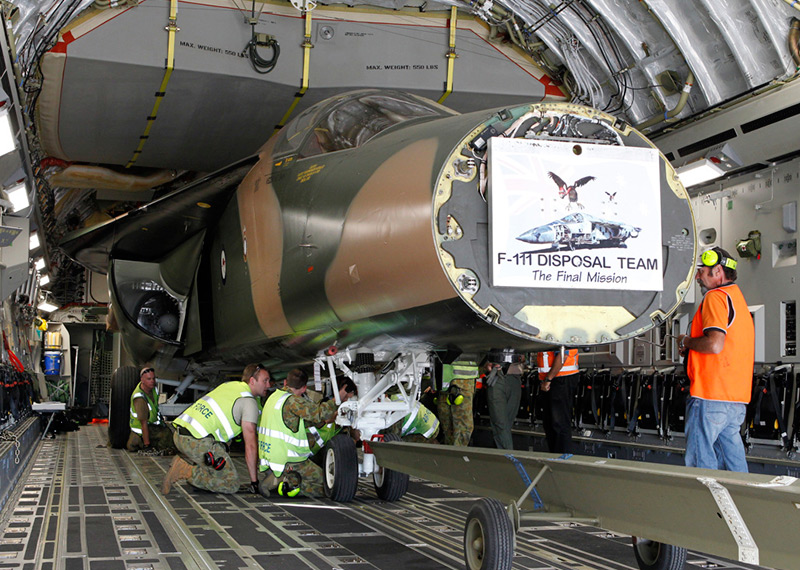
The audit objective was to assess Defence’s implementation of the five recommendations in ANAO Report No.19 2014-15 Management of the Disposal of Specialist Military Equipment and the related recommendation in JCPAA Report 449 Review of Auditor-General's Reports Nos. 1-23 (2014-15).
Entity
Department of Defence
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 45 of 1999–2000)
Published: Wednesday 31 May 2000
Published
The Commonwealth has significant foreign exchange risk exposures including $A8.4 billion of foreign currency transactions with the Reserve Bank of Australia in 1998-99. Under the Financial Management and Accountability Act and its associated Regulations, all agencies are required to assess and, where possible, manage, foreign exchange risk. The audit reviewed four agencies that have substantial foreign currency payment exposures namely:
- the Department of Defence;
- the Australian Agency for International Development;
- the Department of Foreign Affairs and Trade; and
- the Department of Finance and Administration.
The objective of the audit was to identify and assess the efficiency and cost effectiveness of the management of foreign exchange risk across the selected agencies, also to identify opportunities to improve the management of foreign exchange risk, including any associated potential financial savings that could accrue to the Commonwealth.
Entity
Department of Defence; Australian Agency for International Development; Department of Foreign Affairs and Trade; Department of Finance and Administration
Performance audit (Auditor-General Report No. 46 of 1999–2000)
Published: Tuesday 13 June 2000
Published
The audit reviewed the High Wealth Individuals Taskforce, a comprehensive compliance program with the Australian Taxation Office. The objective of the audit was to examine and report on the management and operations of the taskforce. In doing so, the audit reviewed the Australian Taxation Office's own evaluation of the taskforce and assessed whether, and to what extent, the taskforce delivered the outcomes specified by the Government.
Entity
Australian Taxation Office