Browse our range of reports and publications including performance and financial statement audit reports, assurance review reports, information reports and annual reports.
Performance audit (Auditor-General Report No. 31 of 2004–05)
Published: Wednesday 9 March 2005
Published
Given the importance of customer feedback to Centrelink's business, the ANAO considered it timely to conduct a series of performance audits relating to Centrelink's customer feedback systems, particularly in relation to its delivery of the services then provided on behalf of FaCS. The overarching objective of this series of ANAO performance audits of Centrelink's customer feedback systems was to assess whether Centrelink has effective processes and systems for gathering, measuring, reporting and responding effectively to customer feedback, including in relation to customer satisfaction with Centrelink services and processes.
Entity
Centrelink
Performance audit (Auditor-General Report No. 27 of 2006–07)
Published: Wednesday 21 February 2007
Published
This audit focuses on the Australian Defence Force's (ADF) Air Combat fleet's logistics support, regular maintenance and structural refurbishment. These activities are collectively referred to as fleet in-service support. The current Defence White Paper states that Air Combat is the most important single capability for the defence of Australia.
The audit objective was to assess the effectiveness of the Air Combat fleet's in-service support arrangements to provide capability for air combat operations. Capital equipment acquisition projects covered by this report are limited to the Hornet and F-111 structural refurbishment projects, which aim to ensure these aircraft remain serviceable until their withdrawal from service.
Entity
Department of Defence; Defence Materiel Organisation
Performance audit (Auditor-General Report No. 48 of 2003–04)
Published: Thursday 27 May 2004
Published
The objective of the performance audit was to report to Parliament our assessment as to how well the ATO manages and uses the AIIR data in taxation administration. The ANAO considered the following four key areas in addressing the audit objective. 1. Governance arrangements within the ATO, focussing on whole of ATO and whole-of-government aspects of the AIIR data, as distinct from solely business line applications. 2. Receipt of AIIR data and how well the ATO facilitates the collection of complete and valid AIIR data from investment bodies 3. Management of AIIR data through the construction by the ATO of valid entity records by using the AIIR data in conjunction with existing ATO client identification master files. 4: Use of the AIIR data on a systematic basis to inform active compliance activities.
Entity
Australian Taxation Office
Performance audit (Auditor-General Report No. 30 of 1999–2000)
Published: Thursday 3 February 2000
Published
The examined the $1 billion Federation Fund program, which was established by the Government to mark the Centenary of Federation. The objectives of the examination were to assess the:
- extent to which the administration of the FCHP program complied with better practice in the assessment of applications, especially in relation to the transparency and rigour of the decision-making process;
- equity of the geographic spread of grants to States and electorates; and
- process for the announcement of the results of grant applications.
Entity
Across Agency
Performance audit (Auditor-General Report No. 33 of 2004–05)
Published: Wednesday 9 March 2005
Published
Given the importance of customer feedback to Centrelink's business, the ANAO considered it timely to conduct a series of performance audits relating to Centrelink's customer feedback systems, particularly in relation to its delivery of the services then provided on behalf of FaCS. The overarching objective of this series of ANAO performance audits of Centrelink's customer feedback systems was to assess whether Centrelink has effective processes and systems for gathering, measuring, reporting and responding effectively to customer feedback, including in relation to customer satisfaction with Centrelink services and processes.
Entity
Centrelink
Performance audit (Auditor-General Report No. 42 of 2006–07)
Published: Tuesday 12 June 2007
Published
The objective of the audit is to assess the effectiveness of the ATO's administration of debt collection. Micro-business debt is a particular focus of attention. The three key areas examined are:
- strategies–especially the ATO's initiatives trialled in 2006;
- infrastructure–the IT systems, people, policy and processes and risk management framework supporting the collection of debt; and
- management and governance–planning, monitoring and reporting mechanisms and liaison with stakeholders.
The ANAO focused on the work of the campaigns area within the Debt Line, which has collection responsibility for 90 per cent of collectable debt cases and responsibility for other key, centralised functions such as reporting, quality assurance review, consistency and best practice, and the debt collection initiatives.
Entity
NO-DEPTS-LISTED
Performance audit (Auditor-General Report No. 44 of 1999–2000)
Published: Tuesday 16 May 2000
Published
The audit reviewed the management of the first round of Job Network contracts, which focused on Job Matching, Job Search Training and Intensive Assistance. The objective of the audit was to assess the efficiency and effectiveness of the Department of Employment, Workplace Relations and Small Business's management of the first round of employment services contracts. A key part of this examination was to assess the Department's level of confidence that the program was meeting government objectives based on performance and management information.
Entity
Department of Employment, Workplace Relations and Small Business
Performance audit (Auditor-General Report No. 32 of 1998–99)
Published: Monday 8 March 1999
Published
The purpose of the audit was to assess whether management of parliamentary workflow by the agencies reviewed was efficient and effective and to identify elements of good practice. In assessing agency effectiveness and efficiency, the audit focussed on issues of client service such as timeliness, quality and cost. It considered also the governance framework and accountability arrangements relevant to parliamentary workflow, as well as more operational considerations including the use of information technology, development of relevant management information and suitable benchmarking processes.
Entity
Centrelink; Department of Defence; Department of Family and Community Services; Department of Health and Aged Care
Request for audit
Responded: Tuesday 8 September 2026
Response provided
The Auditor-General responded on 8 September 2026 to follow-up correspondence from the Hon Dan Tehan MP and Garth Hamilton MP dated 20 August 2026.
The Auditor-General responded on 31 July 2026 to correspondence from Mr Garth Hamilton MP dated 1 July 2026, requesting that the Auditor-General undertake an assessment of the Capacity Investment Scheme (CIS).
Contact
Please direct enquiries through our contact page.
About
Published: Monday 23 August 2021
Published
The objective of this audit was to assess the effectiveness of the ANAO’s internal budgeting and forecasting processes and practices. View the audit.
This page lists status updates about the ANAO's progress on recommendations contained in the audit.
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 28 of 2002–03)
Published: Friday 7 February 2003
Published
The audit assessed the operations of the four Northern Territory Land Councils which provide a range of services to Aboriginal people under the Aboriginal Land Rights (Northern Territory) Act 1976. The audit also assessed the Aboriginal and Torres Strait Islander Commision's (ATSIC) administration of the Aboriginals Benefit Account, which provides funding to the Land Councils under the same Act. The objectives of the audit were to assess:
- whether the governance arrangements used by ATSIC and the Land Councils are appropriate;
- whether ATSIC meets its legislative requirements concerning the Aboriginals Benefit Account in an effective and efficient way; and
- whether the Land Councils are effective and efficient in managing their recourses to meet the objectives of the Aboriginal Land Rights (Northern Territory) Act 1976.
Entity
Aboriginal and Torres Strait Islander Commission; Anindilyakwa Land Council; Central Land Council; Northern Land Council; Tiwi Land Council
Financial statement audit (Auditor-General Report No. 26 of 2022–23)
Published: Thursday 25 May 2023
Published
This report is the first of two reports each year and focuses on the results of the interim audits, including an assessment of entities’ key internal controls, supporting the 2022–23 financial statements audits. This report examines 27 entities, including all departments of state and a number of major Australian government entities. The majority of entities included in the report are selected on the basis of their contribution to the income, expenses, assets and liabilities of the 2021–22 Consolidated Financial Statements.
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 34 of 2004–05)
Published: Wednesday 9 March 2005
Published
Given the importance of customer feedback to Centrelink's business, the ANAO considered it timely to conduct a series of performance audits relating to Centrelink's customer feedback systems, particularly in relation to its delivery of the services then provided on behalf of FaCS. The overarching objective of this series of ANAO performance audits of Centrelink's customer feedback systems was to assess whether Centrelink has effective processes and systems for gathering, measuring, reporting and responding effectively to customer feedback, including in relation to customer satisfaction with Centrelink services and processes.
Entity
Centrelink
Insights: Audit lessons
Published: Friday 28 May 2021
Published
This edition of Audit Insights summarises key messages for all Australian Government entities from a series of recent Australian National Audit Office (ANAO) performance audits assessing the delivery of key components of the Australian Government’s response to the COVID-19 pandemic. It discusses the importance of planning, good governance and sound risk management in managing an emergency such as the COVID-19 pandemic.
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 20 of 2001–02)
Published: Friday 16 November 2001
Published
The ANAO reviewed arrangements for the development of the department's fraud policy, fraud risk assessment and fraud control plan within the core functional areas of the department that are responsible for these activities. The audit also examined the operational procedures and guidelines that were in place to implement the department's fraud policy. The objective of the audit was to assess whether AFFA has implemented appropriate fraud control arrangements in line with the Fraud Control Policy of the Commonwealth and whether these arrangements operate effectively in practice.
Entity
Agriculture Fisheries and Forestry - Australia
Performance audit (Auditor-General Report No. 6 of 2002–03)
Published: Thursday 29 August 2002
Published
The ANAO reviewed arrangements for the development of the department's fraud policy, fraud risk assessment and fraud control plan within the core functional areas of the department that are responsible for these activities. The audit also examined the operational procedures and guidelines that were in place to implement the departments' fraud policy. The objective of the audit was to assess whether DVA has implemented appropriate fraud control arrangements in line with the Fraud Control Policy of the Commonwealth and whether these arrangements operate effectively in practice.
Entity
Department of Veterans' Affairs
Financial statement audit (Auditor-General Report No. 40 of 2020–21)
Published: Wednesday 2 June 2021
Published
This report is the first in the series of reports for the 2020–21 financial year and focuses on the results of the interim audits, including an assessment of entities’ key internal controls, supporting the 2020–21 financial statements audits. This report examines 25 entities, including all departments of state and a number of major Australian government entities. The entities included in the report are selected on the basis of their contribution to the income, expenses, assets and liabilities of the 2019–20 Consolidated Financial Statements.
Contact
Please direct enquiries through our contact page.
Insights: Audit lessons
Published: Monday 3 April 2023
Published
This edition of Audit Insights is targeted at Australian Government officials who have responsibility for overseeing or conducting procurements, including those who only do procurement occasionally. The aim is to communicate lessons from our audit work to make it easier for people working within the Australian public sector to apply those lessons. It is drawn from audit reports tabled in 2020–21, 2021–22 and 2022–23 into Australian Government procurements.
Contact
Please direct enquiries through our contact page.
Performance audit (Auditor-General Report No. 16 of 2005–06)
Published: Thursday 17 November 2005
Published
The audit was conducted at the: Australian Federal Police (AFP) and the Australian Protective Service (PS); Australian Sports Commission (ASC); Department of Communications, Information Technology and the Arts (DoCITA); Department of Family and Community Services (FaCS); and Civil Aviation Safety Authority (CASA). The objectives of the audit were to: determine whether entities had established appropriate arrangements in relation to the management of annual leave For the purposes of this audit the ANAO has used the term ‘annual leave'. However entities refer to this entitlement using other terminology such as recreation leave, planned leave or personal leave. and had effective internal controls over leave processing; assess whether leave had been managed in accordance with the requirements of the respective entity's certified agreement; and identify sound and better practices in the management and processing of leave.
Entity
Across Entities
Performance audit (Auditor-General Report No. 17 of 2000–01)
Published: Monday 4 December 2000
Published
The objectives of the audit were to: assess compliance with the Stevedoring Levy (Collection) Act 1998 and Stevedoring Levy (Imposition) Act 1998 and other relevant legislation; assess the effectiveness of the administrative and financial controls regarding the collection of the Stevedoring Levy by DoTRS and the provision of redundancy payments to eligible employees of stevedoring companies and the management of the funding of those payments by way of borrowings by MIFCo; and review the administrative efficiency of the redundancy payment and Stevedoring Levy collection aspects of the waterfront redundancy scheme.
Entity
Department of Transport and Regional Services; Maritime Industry Finance Company Ltd
Performance audit (Auditor-General Report No. 8 of 2006–07)
Published: Wednesday 18 October 2006
Published
On 9 May 2006, the Auditor-General advised the then Minister for Transport and Regional Services that he would undertake a performance audit and that the specific audit objectives and approach would be established once officers of the Australian National Audit Office (ANAO) had the opportunity to undertake preliminary enquiries with senior staff in Airservices Australia and the Department of Transport and Regional Services (DOTARS). On 31 May 2006, the Auditor-General designated a performance audit under Section 18 of the Auditor-General Act 1997 (Auditor-General Act). The objectives of the performance audit were to: examine the development and administration by Airservices Australia of its contracts with the Solomon Islands Government for upper airspace management; assess the regularity of payments made under the contracts and steps taken by Airservices Australia in respect of any irregularities; and make recommendations for any improvements in the processes employed by Airservices Australia in developing and administering these and similar contractual arrangements.
Entity
Airservices Australia
Performance audit (Auditor-General Report No. 5 of 2003–04)
Published: Thursday 11 September 2003
Published
This report relates to the fourth audit of Financial Management and Accountability Act 1997 (FMA Act) agencies' compliance with the Order of the Senate for Departmental and Agency Contracts, (the Senate Order) to list, on the Internet, contract details for the reporting period 4 February 2002 to 3 February 2003. The audit was conducted in accordance with the Senate Order request for the Auditor-General to undertake twice-yearly examinations of agency contracts listed on the Internet, and to report whether there had been any inappropriate use of confidentiality provisions. The objectives of the audit were to assess agency performance in relation to compiling the Internet listings required by the Senate Order and the appropriateness of the use of confidentiality provisions in Commonwealth contracts.
Entity
Australian Federal Police (AFP);; Australian Greenhouse Office (AGO);; Department of Defence (Defence);; Department of Employment and Workplace Relations (DEWR);; Department of Family and Community Services (FaCS);1 and; National Capital Authority (NCA)
Performance audit (Auditor-General Report No. 50 of 2005–06)
Published: Tuesday 27 June 2006
Published
The objective of the audit was to assess the framework being put in place to manage and account for aid funds provided under the AIPRD. In particular, the audit addressed: structures for oversighting the development and delivery of the AIPRD; planning and risk management (including those relating to fraud and corruption); financial management; and arrangements for ongoing monitoring and reporting. The audit focussed on the arrangements being established to monitor, evaluate and report on AIPRD implementation, rather than the management of activities and outcomes achieved. This reflects the fact that the long lead times associated with establishing such a large programme of assistance had meant that only limited activities were underway at the time of audit fieldwork. The ANAO anticipates undertaking an audit in the future of the management of activities and outcomes achieved, when more funds have been expended. It was not the purpose of this audit to examine Australia's immediate emergency and humanitarian response to the tsunami crisis.
Entity
Australian Agency for International Development; Department of Foreign Affairs and Trade
Performance audit (Auditor-General Report No. 31 of 2003–04)
Published: Wednesday 25 February 2004
Published
This report relates to the fifth audit of Financial Management and Accountability Act 1997 (FMA Act) agencies' compliance with the Senate Order for Departmental and Agency Contracts, (the Senate Order) to list, on the Internet, contract details for the Financial Year 2002-2003 reporting period. The audit was conducted in accordance with the Senate Order request for the Auditor - General to undertake twice - yearly examinations of agency contracts listed on the Internet, and to report whether there had been any inappropriate use of confidentiality provisions. The objectives of the audit were to assess agency performance in relation to compiling the Internet listings required by the Senate Order and the appropriateness of the use of confidentiality of provisions in Commonwealth contracts.
Entity
Australian Industrial Registry; Australian Taxation Office; Department of Communications Information Technology and the Arts; Department of the Environment and Heritage; Federal Court of Australia; National Office for the Information Economy
Request for audit
Responded: Friday 20 March 2020
Response provided
The Auditor-General responded on 20 March 2020 to correspondence from Senator Larissa Waters dated 25 February 2020, requesting that the Auditor-General consider the process followed in approving the Adani Carmichael Coal Mine and Rail Project when conducting the audit Referrals, assessments and approvals of controlled actions under the Environment Protection and Biodiversity Conservation Act 1999.
Contact
Please direct enquiries relating to requests for audit through our contact page.
Performance audit (Auditor-General Report No. 14 of 2015–16)
Published: Monday 14 December 2015
Published
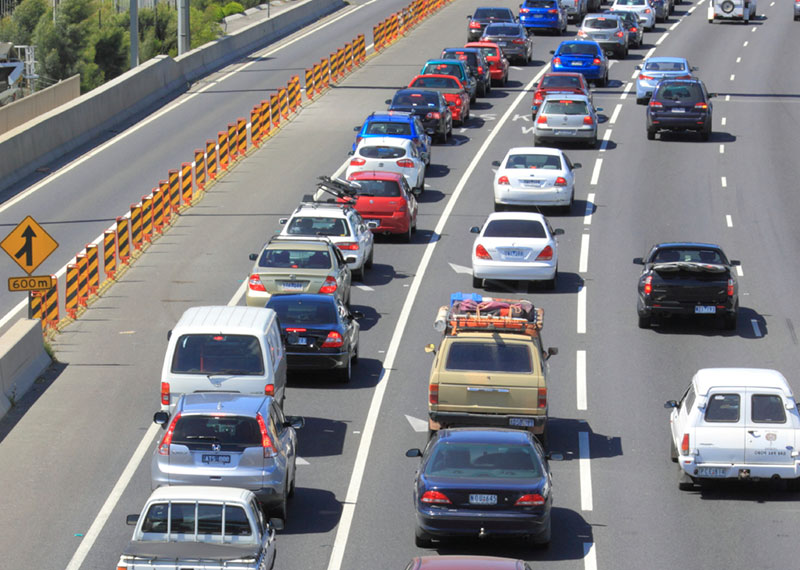
The objective of the audit was to assess whether appropriate steps were taken to protect the Commonwealth’s interests and obtain value for money in respect to the:
- approval of $1.5 billion in Commonwealth funding for stage one of the East West Link project, and the June 2014 payment of $500 million of this funding; and
- approval of $1.5 billion in Commonwealth funding for stage two of the East West Link project, and the June 2014 payment of $1 billion of this funding.
Entity
Department of Infrastructure and Regional Development; Infrastructure Australia; Department of the Treasury; Department of the Prime Minister and Cabinet; and Department of Finance.
Contact
Please direct enquiries relating to reports through our contact page.
Performance audit (Auditor-General Report No. 17 of 2006–07)
Published: Tuesday 23 January 2007
Published
The Department of the Treasury (the Treasury) manages Australia's relations with the International Monetary Fund (IMF) and various development banks. As of
30 June 2006, the Treasury's administered assets in the IMF and other international financial institutions totalled A$7.1 billion. Liabilities totalled A$4.8 billion. In addition to the liabilities of A$4.8 billion, there were contingent liabilities of A$7.3 billion, comprising uncalled share capital subscriptions.
In October 2002 a performance audit of the Treasury's management of international financial commitments (ANAO Audit Report No.10 of 2002–03 Treasury's Management of International Financial Commitments) was tabled in the Parliament. This audit is a follow-up to that audit. The objective was to assess the progress made by the Treasury in addressing the four major audit findings and two recommendations of the 2002 audit report.
Entity
NO-DEPTS-LISTED
Request for audit
Responded: Thursday 28 September 2023
Response provided
The Auditor-General responded on 28 September 2023 to correspondence from Senator the Hon Michaelia Cash dated 5 September 2023, requesting that the Auditor-General conduct an investigation to assess the adequacy of data collection, performance monitoring and other governance arrangements under the National Legal Assistance Partnership (NLAP) in the Attorney-General’s portfolio.
Contact
Please direct enquiries relating to requests for audit through our contact page.
Performance audit (Auditor-General Report No. 2 of 1999–2000)
Published: Thursday 15 July 1999
Published
The effective use of financial information is a critical component of an organisation's performance management framework. The appropriate combination of financial and non-financial data reflects overall organisational performance, and performance at program and work unit levels. The objective of this audit was to assess what financial information is currently used, who uses it and how well it is used. The audit also assessed whether the current processes for defining, accumulating and producing financial information were appropriate for the new accrual based performance management framework, which is to be in place for 1999/2000.
Entity
Across Agency
Insights: Audit lessons
Published: Tuesday 20 June 2023
Published
This edition of Audit Insights is targeted at Australian Government officials who have responsibility for the management and reporting of executive remuneration. The aim of Audit Insights is to communicate lessons from our audit work to make it easier for people working within the Australian public sector to apply those lessons. It is drawn from audit reports tabled between 2019–20 and 2022–23.
Contact
Please direct enquiries through our contact page.